The insurer already filed the rate.
The household still pays a number that may not match it.
That gap is the product.
The idea mills keep minting an insurance chatbot, a premium-comparison app, and a ratecheck.ai.
Three names.
One object.
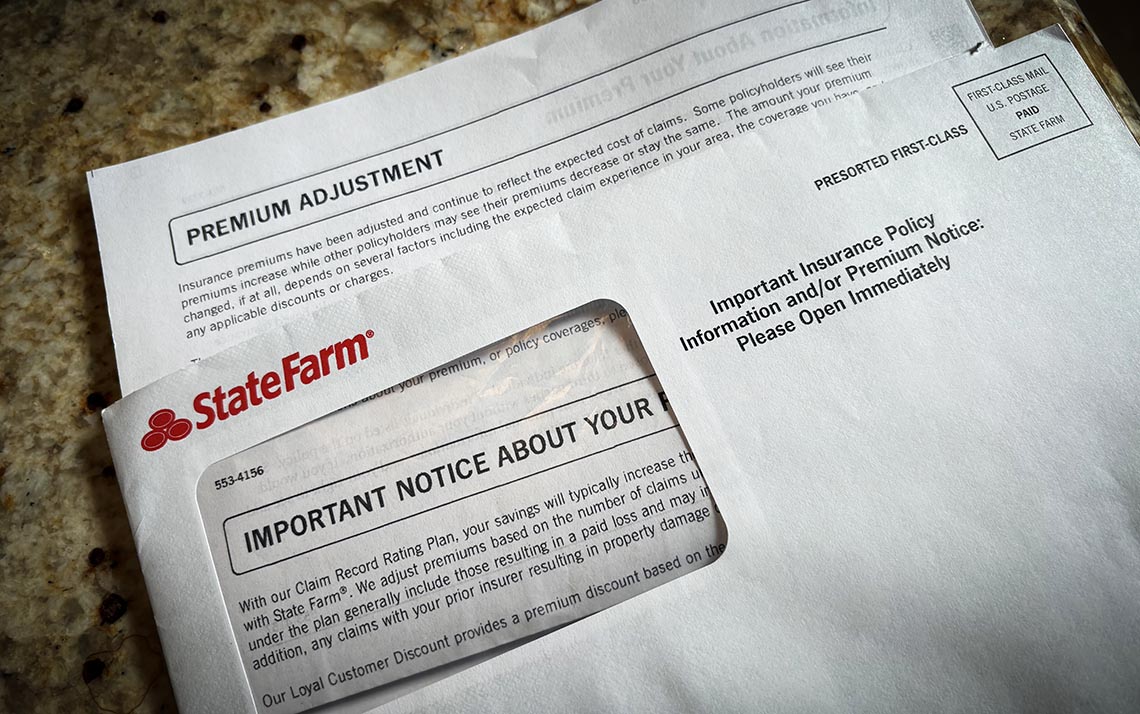
A renewal notice or declaration page that does not sit next to the rate filing the state already accepted through SERFF or the department of insurance portal.
Greg Isenberg’s stream and the daily micro-SaaS accounts keep splitting the same reader.
One post wants a usage coach that nags you to shop.
Another wants a letter filler that drafts a complaint.
A third wants a photo upload that becomes a “save on insurance” dashboard.
The owner does not wake up wanting a new dashboard.
They wake up because the bill went up and they cannot see the filed number it is supposed to match.
Two primitives, one wedge
Primitive one is photo-and-PDF review.
The mills have been shipping receipt readers for months.
The input here is the renewal notice, the declaration page, or the premium adjustment letter.
Carrier name in the header.
Policy type on the line.
Effective date of the increase.
Dollar amount of the change.
Primitive two is the public rate filing.
Most states make personal auto and homeowners filings public through SERFF Filing Access or a state portal once they are approved or, in some cases, when they are received.
Texas makes them public information on filing under Insurance Code §2251.107.
California lists them in weekly notices and, as of October 19, 2026, posts the department’s own expert analysis of rate requests under the new Comprehensiveness Review Regulation.
Florida’s Office of Insurance Regulation announced on October 29, 2026 that more than 824,300 homeowners received rate decreases of up to 12.1 percent in October, with roughly 450,000 more decreases pending through January.
New York’s 2026 budget law, effective August 24, 2026, requires an automatic explanation on any renewal increase above 10 percent—the dollar amount and the reason—without the policyholder having to ask.
The mills keep these apart: a reader, a shopper, an explanation letter.
The household needs them on one page.
The wedge is a free checker.
Paste the renewal text or upload the PDF this week.
The tool extracts carrier, product, state, and the stated percentage or dollar change, then looks up the matching public filing.
It returns three lines: the filed overall rate impact, the effective date for renewals, and whether the notice you received is consistent with that filing or whether a decrease was approved but has not yet reached your renewal cycle.
No account required.
No phone call.
If the join fails, it says so.
If the join holds, you see the gap.
Why now is checkable
Florida’s October 29 announcement is not a forecast.
It is a count of policies already adjusted and a list of carriers and percentages.
Universal Property & Casualty applied roughly 5 percent decreases on about 512,000 policies.
Cypress applied 12.1 percent.
Those decreases reach a policy only at the first renewal on or after the filing’s effective date.
A renewal that arrived the week before the cut still carries the old rate for another year unless someone notices and shops or asks.
New York’s rule is already in force.
An increase above 10 percent must arrive with the explanation attached.
An increase below 10 percent must arrive with a prominent notice that the explanation is available on request.
The law does not require the carrier to show the statewide filing next to the individual notice.
That join is still missing.
California’s October 19 regulation makes the department’s pre-filing analysis public.
The analysis shows what the department challenged and what projected savings it claimed.
The policyholder still holds a renewal that does not cite that analysis.
These are not vibes.
They are dated agency announcements and enacted statutes with effective dates inside 2026.
The map after volume
The free checker is not the company.
The company is the labeled map that accumulates after volume.
Each successful join records the carrier, the SERFF tracking number or state filing ID, the filed percentage, the renewal date, and the variance between the notice and the filing.
Over thousands of renewals the map shows which carriers systematically apply decreases late, which ones add surcharges not visible in the overall rate impact, and which states’ public portals are complete enough to support an automated check.
That map is useful to three parties the mills never mention.
The household that wants to know whether to call before paying.
The independent agent who can show a client the filed number next to the renewal.
The state market-conduct unit that receives a pattern instead of a single complaint.
Models draft the comparison.
People own the send.
Any formal rate challenge, market-conduct complaint, or request for a hearing is signed by the policyholder or their agent.
The tool produces the packet.
It does not file it.
What the mills get wrong
The mills keep proposing a new .ai name for each carrier’s portal.
Ignore the names.
Join the line.
Keep the map.
Someone will own the labeled map of renewed versus filed.
The household will paste one notice this week because the action is free and the alternative is paying the number that arrived in the mail.
The volume that follows is not a dashboard.
It is the dataset of where the filed rate and the billed rate diverge.
Will Tygart — Tygart Media.
This is the idea-mill series.