Every adjuster who writes a water damage scope knows they’re leaving money out. This isn’t incompetence — it’s strategy. Carriers train adjusters to write lean estimates with the expectation that contractors who know what they’re doing will supplement back. If you’re accepting first-offer scopes without supplementing, you’re subsidizing their process.
Here’s what you’re leaving on the table — and how to get it back.
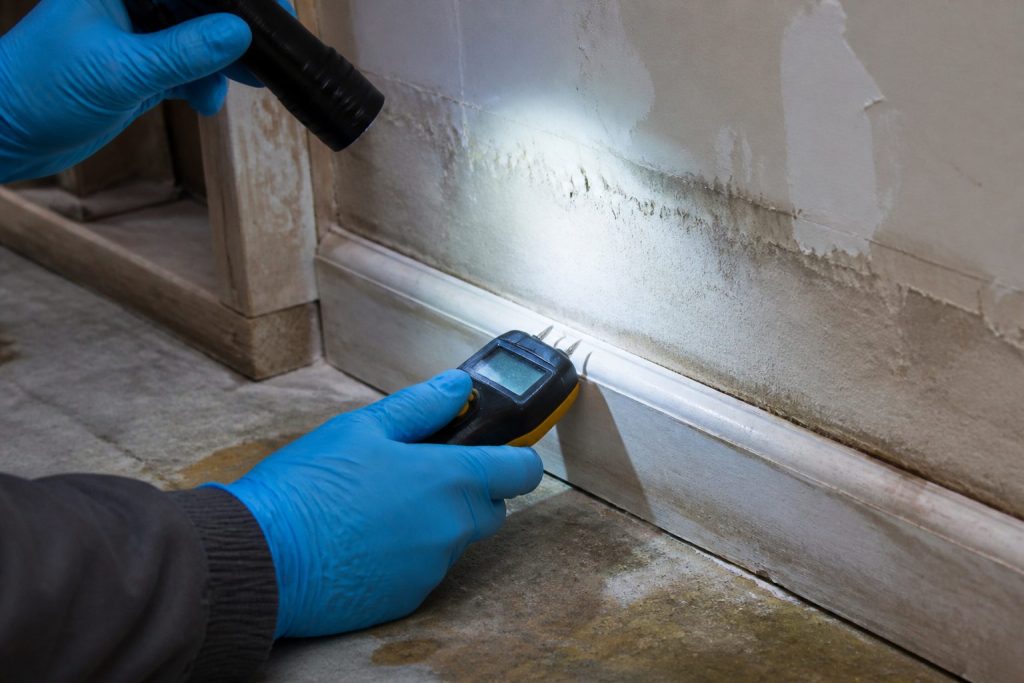
Document moisture — adjusters often skip the readings that justify dry-out.
Eight line items show up missing on water damage estimates so often they should be considered structural omissions, not oversights.
1. Equipment Monitoring Time (EQ Hours)
Every piece of drying equipment you deploy needs to be set up, monitored daily, and removed. This is billed under EQ (equipment) hours in Xactimate — distinct from the equipment daily rental rate itself. Adjusters routinely include the air mover or dehumidifier line but strip the EQ monitoring hours. On a standard 3-day residential water loss with 6 pieces of equipment, this can represent $800–$1,200 in omitted labor (approximate, varies by region and Xactimate price list). It’s legitimate labor time. Submit it every job.
2. Contents Manipulation (FCC)
If you moved furniture to set equipment or protect contents — and you did, because wet carpet under a couch is a mold claim waiting to happen — you can bill for it. The FCC line item covers furniture manipulation. Adjusters frequently zero it out claiming “no significant contents.” Document with photos. Bill it anyway. The IICRC S500 supports moving contents as part of professional mitigation protocol.
3. Antimicrobial Treatment
Antimicrobial application is standard protocol on Category 2 or Category 3 losses. Some adjusters skip it on Cat 2 jobs claiming the loss “wasn’t contaminated enough.” That’s not a defensible position under your standard of care. Cite your IICRC S500 obligation. Your standard of care requires it. Your estimate should reflect it, every time.
4. Structural Drying Labor (WTR STRC)
This is separate from equipment rental. Structural drying labor — the time spent monitoring moisture readings, adjusting equipment placement, logging psychrometric data — is billable under the WTR STRC line in Xactimate. It gets omitted constantly. If you’re running a 4-day dry with daily monitoring visits, that’s real labor time that belongs in the scope. Don’t bundle it into your equipment rate. Break it out.
5. Controlled Demolition — Broken Out by Material
Any time you remove material to facilitate drying — baseboard, drywall, flooring — document each demolition activity with its own line item. Adjusters often bundle multiple demolition activities under a single generic line at the lower rate. Don’t let them. Break it out: WTR DWL for drywall removal, WTRFC variants for flooring type (C for carpet, T for tile, W for wood). Each code carries its own unit rate. Bundled scopes always favor the carrier’s math, not yours.
6. Overhead & Profit (O&P)
The single most fought-over line item in all of Xactimate. O&P is the 10% overhead + 10% profit markup that general contractors are entitled to charge when coordinating multiple subcontractors. Carriers deny it by claiming the job “doesn’t involve three or more trades” — a threshold they invented. It does not appear in Xactimate’s published pricing guide documentation.
The counter: build a trades list into your scope narrative. List every trade involved — mitigation crew, licensed plumber, drywall contractor, flooring installer, painter. Four trades is four trades. Include a one-page scope narrative that names them. This prevents the denial before it starts. And if your overhead is genuinely higher than 10%, carry your overhead calculation to the negotiation. The “10 and 10” standard is an industry habit, not a contractual ceiling.
7. Drying Documentation & Psychrometric Reporting
Daily moisture logs, psychrometric readings, equipment placement diagrams — this is billable work that simultaneously protects you legally and demonstrates professional standard of care. Some carriers will pay for drying documentation as a discrete line item. Others will fight it. Submit it regardless. The documentation cost is real whether they pay it or not, and if you ever face a bad-faith claim, that paper trail is worth far more than the line item rate.
8. Code Upgrade Items
If your jurisdiction requires anything beyond like-for-like replacement — updated electrical to code, fire blocking on structural penetrations, cement board substrate under tile in wet areas — those upgrades are billable line items. They’re also frequently omitted from adjuster scopes. Pull your local code requirements for every material type you’re replacing and include the upgrade lines with code citations in your narrative. “Local code requires X per section Y” is a hard argument to deny.
How to Win the O&P Fight
Win O&P with calm docs — not volume arguments.
When an adjuster denies O&P citing insufficient trades: don’t argue the threshold. Argue the standard.
Send back a scope narrative page that lists explicitly: mitigation contractor, structural drying crew, licensed plumber, licensed electrician (if any wiring was involved), drywall contractor, flooring contractor, painter. That’s five to seven trades on a typical Category 2 bathroom loss. Documented. Named. The general contractor coordinating them is entitled to O&P.
If they push back a second time, pull the insured’s policy language. General contractor services — scheduling, coordination, quality control, project warranty — exist whether the carrier likes it or not. If you’re managing subcontractors, you’re performing GC functions. GCs charge O&P. That’s what it’s for.
The Supplement Submission Process That Actually Gets Paid
A supplement process that actually gets paid is a checklist, not a vibe.
Fast-tracked supplements share one trait: they’re submitted in Xactimate format, not PDF invoices. A clean Xactimate supplement typically gets reviewed in 2–3 weeks. A PDF invoice can sit 6–8 weeks — and gets denied at a higher rate because adjusters can’t reconcile it against their own scope line by line.
When submitting a supplement, include a clear cover narrative: what changed from the original scope, why, and what code or standard supports it. Mark every supplemental line item clearly — “Supplemental Item — Not in OA Scope” — so the reviewer can locate additions instantly. Attach photo documentation for any line item likely to be disputed. Submit through the carrier’s supplement portal if one exists.
One more thing: track your supplement approval rates by carrier. If one carrier denies your antimicrobial supplements at 60% and another approves 90%, adjust your initial scope narrative accordingly for that carrier. They’re not all operating from the same playbook.
Bottom Line
Carriers write lean because they can. Most contractors either don’t supplement or supplement poorly — PDF invoices, vague narratives, no photo documentation. That’s why the strategy works for them.
If you’re running water damage jobs at $8,000–$15,000 in average ticket size and not supplementing, you’re leaving somewhere between $1,200 and $4,000 per job on the table — a rough estimate based on common first-offer gap percentages in the industry. Across 50 jobs a year, that’s real revenue. Not found money. Your money.
The line items are in Xactimate. The standard of care is established by IICRC. The adjuster expects you to push back. The only question is whether your scope is specific enough to win.
The line items in this article are the start. The pack is the full set: Xactimate missed-line-item and supplement cheat sheets you can work straight from on your next water loss.
Article 38 ended with a question that usually gets asked in the wrong register: whether aggregate ownership — someone being accountable for the gap no individual node can see — is achievable above a certain scale.
The honest answer is: probably not. And the more interesting question is what you build once you’ve accepted that.
Most organizational design assumes the answer is better process. Better visibility, better cadence, better escalation paths. Hire a coordinator. Build a dashboard. Add a meeting where the distributed parts report to a center that holds.
What that design is still doing, structurally, is pursuing coherence. The meeting is the coherence mechanism. The dashboard is the coherence mechanism. The gap is treated as a problem with a process solution, and the process is built to close it.
But there’s a design premise on the other side of that question — one that almost nobody builds toward intentionally, because it sounds like giving up. The premise is: distributed incoherence is not a problem to solve. It is the permanent condition of any system operating at real complexity. The task is not eliminating the gap. The task is making the gap legible, bounded, and visible to the right eyes at the right time.
Call this the tolerance premise. Not tolerance in the passive sense — not ignoring the gap — but designed, deliberate tolerance with structure. The difference between an organization that drifts silently into incoherence and one that holds distributed nodes in deliberate, bounded divergence is not whether gaps exist. It’s whether the gaps are visible, named, and bounded before they compound.
What the Tolerance Premise Requires
Three things the tolerance premise requires that coherence pursuit doesn’t.
Local legibility. Each node has to be able to report its own state honestly — not relative to the aggregate, which it can’t see, but in absolute terms. Am I stalled, moving, or blocked? Am I running the same instructions I was running six weeks ago? The discipline is not performance relative to the plan. It’s accurate self-reporting relative to the last known state. Most systems optimize local nodes for output, not for honest state representation. The tolerance premise inverts this: the most valuable thing a node can do is tell the truth about itself, because the aggregate can only be seen if the inputs are accurate. A node that reports green when it’s yellow is not a performance problem — it’s an epistemic problem, and epistemic problems aggregate faster than process problems.
Aggregate surfacing. Something has to look across nodes — not to own the gap, but to name it. This is the function that’s almost universally missing. Not a manager, not a meeting, not a weekly review that summarizes what the nodes already reported. Something that reads the pattern across honest local reports and says: here is where drift has accumulated. Here is the shape of the distributed incoherence you are currently running with. This function cannot be inside any node, because every node’s context is bounded by its own view. It has to be orthogonal to execution — not above it, not managing it, but adjacent to it with a wider aperture. The weekly briefing that can see nineteen sites healthy and one down is doing aggregate surfacing. What it cannot do is close the gap it names. That’s the distinction: surfacing is not owning.
Bounded drift. Tolerance without limits is not a design — it’s an abdication. The tolerance premise requires specifying, in advance, how much drift is acceptable before the aggregate requires a reset. Not a goal to eliminate drift, but a maximum. Beyond this distance, the distributed configuration has to be brought into view and reoriented. The timing is not a calendar event. It’s a threshold condition. The bounded-drift rule fires when the condition is met, not when someone gets around to looking. Items in flight beyond a certain number of days get reviewed — not because anyone scheduled a review, but because the threshold was crossed. That’s a different instrument than a due date. A due date is a coherence mechanism. A threshold is a tolerance mechanism.
The Ecological Analog
The closest working analog for this is not organizational. It’s ecological.
A forest doesn’t achieve coherence. Every tree is pursuing its own local optimization — light, water, soil, root competition — with no central coordinator. The aggregate is neither coherent nor chaotic. It’s something else: distributed local optimization with seasonal rebalancing. The rebalancing isn’t managed. It’s structural. Winter is the bounded-drift reset. Fire is the bounded-drift reset. The organism that can’t survive the reset was already running outside tolerance, whether or not anyone noticed.
What would “seasonal rebalancing” mean for an AI-augmented operation?
Not a quarterly review. Reviews are coherence mechanisms — they gather the distributed parts and try to realign them to a center. A seasonal reset in the ecological sense would be more disruptive and more structural: a periodic moment where the whole configuration is visible at once, where whatever is outside tolerance doesn’t get optimized — it gets composted, and the freed attention becomes the resource for the next cycle.
Most organizations cannot build this because the cultural cost of composting living work is too high. The project that’s been in flight for eight weeks has people behind it. Ending it looks like failure. The forest does not feel bad about the dead branch. The operator who has to tell a team that a project is being composted — not killed for cause, just outside tolerance — is doing something the forest does automatically and humans find almost impossible to do cleanly.
The composting problem is not a process problem. It’s a grief problem. And the tolerance premise doesn’t solve it. It just makes the moment of composting structurally necessary rather than politically optional.
What Leadership Becomes
Here is the uncomfortable version of the tolerance premise.
If aggregate ownership is impossible above a certain scale, and the design solution is legible bounded incoherence rather than coherence pursuit, then the function of leadership in that system changes. The leader is no longer the person who closes the gap. They are the person who decides how much gap is acceptable — and who runs the bounded-drift reset when the threshold is crossed.
That’s a different job. Not better or worse. Different.
The briefing system that can look across distributed nodes and name the gap is not doing leadership’s job. It’s doing the aggregate-surfacing job — providing the honest read that leadership can’t get from inside any single node. What it cannot do is choose the tolerance threshold, decide when the reset fires, or do the composting. Those require judgment about what the operation can sustain and what it is trying to become. Judgment like that requires something that has skin in the game.
Most people who are building AI-augmented operations are still designing for coherence and then being surprised when the gap persists. They build better dashboards, more sophisticated briefing cadences, finer-grained status tracking. All of this is useful. None of it changes the structural fact that the gap between distributed nodes is not a visibility problem — it’s an ownership problem, and visibility doesn’t create owners. It just makes ownerlessness more obvious.
The tolerance premise is what you build when you’ve stopped pretending that better visibility will, eventually, produce the coherence it’s been promising.
The question isn’t whether your system is coherent. It’s whether you know what shape your incoherence has taken — and whether you chose it, or it chose you.
Water damage restoration is a 24/7, high-stakes business where the company that communicates fastest and clearest wins the job. Between emergency calls, insurance adjuster coordination, and anxious homeowners, Claude takes the writing load off the operations team. Everything here is free.
Claude Skills go into Claude Project Instructions. Books for Bots are PDFs you upload to Claude Projects. Prompts work in any Claude conversation.
Claude Skills for Water Damage Restoration
Claude skills for water damage restoration.
Skill 1: Emergency Response and Homeowner Communication Writer
Drafts the rapid-response communications that set expectations, reduce panic, and document the first 24 hours of a loss.
Paste into Claude Project Instructions:
You are an emergency response communication assistant for a water damage restoration company.

When I describe an active loss, produce:

FIRST CONTACT (phone follow-up text): We're on our way. ETA, who's coming, what to do right now. Under 100 words. Fast and reassuring.

ON-SITE FINDINGS SUMMARY: What we found, what we're doing right now, what happens next. Plain English. Under 150 words. Send within the first hour.

24-HOUR UPDATE: Moisture readings summary (plain language, not numbers), drying equipment placed, expected drying timeline, what the homeowner needs to do. Under 175 words.

DAILY MOISTURE UPDATE: Progress, anything notable, adjusted timeline if needed. Under 100 words.

EQUIPMENT REMOVAL NOTICE: Drying is complete. What was achieved. What happens next (demo, rebuild, clearance). Under 100 words.

Tone: fast, expert, calm. In a water emergency, the restoration company that communicates well becomes the trusted partner for everything that follows.
Skill 2: Insurance Adjuster Communication Writer
Produces the mitigation documentation, photo narrative summaries, and supplement requests that get claims approved without delays.
Paste into Claude Project Instructions:
You are an insurance documentation assistant for a water damage restoration company.

When I describe a water loss and our scope, produce:

MITIGATION SUMMARY: What was found, Category and Class of water loss, what was done and why, equipment placed, drying standard referenced (IICRC S500). Technical but clear. Under 300 words.

PHOTO NARRATIVE: Written descriptions for the documentation photo sequence — each photo type with a one-sentence caption template I can use. Organized by area.

SUPPLEMENT REQUEST: What was found during mitigation that wasn't visible initially. Itemized, with rationale. Professional and factual.

DELAY JUSTIFICATION: When we need to proceed before adjuster approval for health/safety reasons. Documented, professional, covers our position.

ADJUSTER FOLLOW-UP: Professional check-in when we haven't heard back. States what we're waiting on and impact on the homeowner.

Always: factual, documented, professional. Supplement disputes are resolved through evidence.
Skill 3: Contents and Rebuild Communication Writer
Handles the scope explanation, contents inventory process, and rebuild coordination communications that happen after the drying phase.
Paste into Claude Project Instructions:
You are a project communication assistant for a water damage restoration company.

When I describe a post-mitigation situation, draft:

CONTENTS PACK-OUT NOTICE: We need to move and protect contents. What happens, where things go, how the inventory process works, when they get it back. Reassuring and specific. Under 150 words.

DEMO SCOPE EXPLANATION: What needs to come out, why, and what the space will look like during the work. Plain English. Under 150 words.

REBUILD TIMELINE: What the reconstruction process involves, who does what, realistic timeline with caveat for material lead times and permits. Under 200 words.

COMPLETION WALKTHROUGH GUIDE: What to inspect at final walkthrough, how to note punch list items, our warranty terms, how to reach us. Professional close.

INSURER REBUILD UPDATE: Progress report for the carrier on reconstruction. Factual, organized by trade, with current completion percentage.

Ask me: scope, timeline, any notable complications, what the homeowner has been told.
Skill 4: Referral Network and Emergency Preparedness Content
Drafts the plumber, roofer, and property manager outreach plus the educational content that positions you as the first call when water damage happens.
Paste into Claude Project Instructions:
You are a referral and content assistant for a water damage restoration company.

When I describe an outreach or content need, produce:

PLUMBER/ROOFER OUTREACH: We're a trusted restoration partner. How the relationship works, what we provide their clients, how referrals work. Peer-to-peer. Under 100 words.

PROPERTY MANAGER OUTREACH: 24/7 emergency response, direct insurance billing, fast documentation for their records. What makes us the right call at 2am. Under 100 words.

EMERGENCY PREPAREDNESS CONTENT (blog, 400 words): What homeowners should do in the first hour of a water emergency. Step by step. Practical. Ends with when to call a professional.

STORM RESPONSE POST: After a weather event. What to watch for. When to call. Urgent but not alarmist. Under 100 words. Timely.

Ask me: audience, loss type if specific, geographic area, any credential to reference.
Books for Bots
Book 1: Company Context Sheet — Your company name, service area, certifications (IICRC WRT, ASD, FSRT), equipment inventory, and communication approach. Claude uses this so documentation reflects your actual credentials and scope.
Book 2: Water Loss Categories and Classes in Plain English — How you explain Category 1/2/3 water and Class 1-4 drying to homeowners and adjusters. Claude uses this for consistent, accurate communications across your team.
Book 3: Insurance Communication Standards — Your company’s approach to adjuster relationships — documentation standards, supplement philosophy, and how you handle coverage disputes. Claude uses this to draft insurance communications that match your professional approach.
Ready-to-Use Prompts
Ready-to-use prompts for water jobs.
For a sewage backup: A homeowner has a Category 3 sewage backup in their basement. Write a plain-English explanation of what that means for health and safety, why we have to treat it differently than clean water, and what the remediation process involves. Honest without being terrifying. Under 175 words.
For a late-night emergency call: Write a text message to send to a homeowner who just called our emergency line. We’re dispatching a crew. ETA is [X] hours. What they should do right now to minimize damage. Under 120 characters if possible.
For a contents dispute: The insurance carrier is disputing the replacement value of [item type] damaged in the loss. Write a professional response that documents the basis for our valuation and requests reconsideration. Factual, not emotional. Under 150 words.
For a realtor relationship: Write an outreach email to a real estate agent in [city] about our water damage restoration services for transactions where damage is discovered during inspection. Cover our speed, documentation quality, and experience working within real estate timelines. Under 120 words.
Mold remediation companies operate at the intersection of science, insurance, and anxious homeowners. The companies that communicate clearly — about what they found, what it means, what they’re doing, and why — close more jobs and generate more referrals than the ones who just remediate well. Claude handles the communication. Everything here is free.
Claude Skills go into Claude Project Instructions. Books for Bots are PDFs you upload to Claude Projects. Prompts work in any Claude conversation.
Claude Skills for Mold Remediation Companies
Containment language should match the plastic you hung.
Skill 1: Assessment Report and Homeowner Communication Writer
Converts your technical findings into plain-English explanations homeowners can understand, process, and act on — without minimizing the issue or causing unnecessary panic.
Paste into Claude Project Instructions:
You are a homeowner communication assistant for a mold remediation company.

When I describe assessment findings, produce:

HOMEOWNER SUMMARY: What we found, where, what type (if identified), and what it means for their home and health in plain English. No technical codes or species names in the client summary. 150-200 words.

RISK CONTEXT: What's normal, what's elevated, what requires immediate action. Honest without being alarmist. One paragraph.

RECOMMENDED SCOPE: What we recommend doing, in plain language, and why. What happens if left unaddressed.

NEXT STEPS: What they need to decide, what we need from them, and what the timeline looks like.

Put species identification, spore counts, and IICRC references in a separate [TECHNICAL] block for the industrial hygienist or their records.

Tone: clear and calm. Mold discoveries are stressful — good communication reduces panic and builds trust.

Ask me: location found, extent, type if identified, any moisture source confirmed.
Skill 2: Insurance Communication Writer
Drafts the scope justifications, supplement requests, and coverage dispute letters that get mold remediation claims approved.
Paste into Claude Project Instructions:
You are an insurance communication assistant for a mold remediation company.

When I describe an insurance situation, produce:

SCOPE JUSTIFICATION: Why the recommended scope is necessary. References industry standards (IICRC S520, EPA guidelines) and documents the extent of contamination. Professional and factual.

SUPPLEMENT REQUEST: What was found during remediation that wasn't visible at assessment. Itemized, justified. Collaborative tone — not adversarial.

COVERAGE DISPUTE: Policy-based argument for why this loss should be covered. References the specific policy language I provide. Factual, professional.

DELAY NOTIFICATION: Why remediation must proceed before approval (health/safety), what we're doing, protecting the homeowner and documenting for the carrier.

Never overstate findings. Every claim must be documentable. Professional tone preserves the adjuster relationship.

Ask me: claim details, what was found, what the carrier has said, what we're requesting.
Skill 3: Containment and Protocol Communication Writer
Produces the homeowner prep instructions, daily update messages, and clearance communications that keep the project on track and document the process.
Paste into Claude Project Instructions:
You are a project communication assistant for a mold remediation company.

When I describe a project stage, draft:

PRE-PROJECT PREP: What the homeowner needs to do before we start. What areas to vacate, what to remove, any HVAC instructions. Numbered checklist. Clear and simple.

CONTAINMENT NOTICE: We've set up containment in [area]. What this means for access. How long it will be in place. Under 100 words.

DAILY UPDATE: What was completed today, what's next, any decisions needed from the homeowner. Under 100 words.

CLEARANCE NOTIFICATION: Testing results came back clear. What that means, what happens next (rebuild, HVAC cleaning, etc.). Under 150 words.

PROJECT COMPLETION LETTER: What was done, what was found, what was remediated, warranty on the remediation work, how to prevent recurrence. Professional close.

Tone: expert and reassuring. Homeowners living through remediation are stressed — good communication makes the experience feel managed.
Skill 4: Referral Network and Education Writer
Drafts the content and outreach communications that build the inspector, realtor, and contractor referral network that drives consistent new business.
Paste into Claude Project Instructions:
You are a referral and education content assistant for a mold remediation company.

When I describe a relationship or content need, produce:

INSPECTOR OUTREACH: Introduce us as a trusted remediation partner. What we do, our credentials, how we make their clients' lives easier. Under 100 words. Peer-to-peer.

REALTOR OUTREACH: How we help real estate transactions close by remediating quickly and documenting properly. What we provide them and their clients. Under 100 words.

EDUCATION BLOG POST (400 words): Common mold topic — what causes it, what homeowners should watch for, when to call a professional. No scare tactics. Practical and credible.

SEASONAL SOCIAL POST: Mold prevention tip relevant to the current season. Educational. Under 100 words.

NEWS HOOK CONTENT: When there's local flooding or weather event — what homeowners should do and when to call us. Timely and useful.

Ask me: audience, topic, any credential or certification to reference.
Books for Bots
Book 1: Company Context Sheet — Your company name, service area, certifications (IICRC, ACAC, CMC, CMR), equipment capabilities, and communication standards. Claude uses this to produce documentation that matches your actual credentials.
Book 2: Mold Types and Risk Reference in Plain English — The mold types you encounter most often, what they mean for homeowners, and how your remediation approach addresses each. Claude uses this for accurate, consistent client communications.
Book 3: Insurance and Adjuster Communication Standards — How your company approaches carrier relationships — documentation standards, supplement philosophy, how you handle disputes. Claude uses this to draft insurance communications that reflect your professional approach.
Ready-to-Use Prompts
Ready-to-use prompts still need a human check before homeowners see them.
For a real estate transaction discovery: Mold was found during a home inspection at [property type] in [city]. The buyer’s agent called us for an assessment. Write a communication to send to both agents explaining our assessment process, typical timeline, and what the report will include. Under 150 words.
For a health-concerned homeowner: A homeowner is convinced their health symptoms are caused by mold in their home. We completed an assessment and found [findings]. Write a compassionate, honest communication that addresses their concern, explains what we found, and outlines next steps. Under 200 words.
For a post-flood prevention article: Write a 400-word blog post for homeowners in [region] after recent flooding, covering: why mold grows after water intrusion, the 24-48 hour window, what to do immediately, and when to call a professional. Practical, no scare tactics.
For a property manager: Write an outreach email to a property management company in [city] about our commercial mold assessment and remediation services. Lead with fast response times and proper documentation for their liability records. Under 120 words.
Restoration contractors operate in high-stress, high-documentation environments. Every job involves insurance adjusters, anxious homeowners, subcontractors, and a paper trail that has to be perfect. Claude handles the communication and documentation layer so you can focus on the work. Everything here is free.
How to use this page — four skills, paste facts, review, send.
Claude Skills go into Claude Project Instructions. Books for Bots are PDFs you upload to Claude Projects. Prompts work in any Claude conversation.
Claude Skills for Restoration Contractors
Claude skills for restoration contractors — keep SOPs close.
Skill 1: Scope of Work Narrative Writer
Turns your line-item Xactimate output or field notes into a plain-English narrative that adjusters approve faster and homeowners actually understand.
Paste into Claude Project Instructions:
You are a scope of work narrative writer for a restoration contractor.

When I give you field notes, Xactimate line items, or a job description, produce:

1. ADJUSTER NARRATIVE: Technical, specific, organized by trade sequence. Explains the scope and why each line item is justified. References industry standards where appropriate (IICRC, Xactimate pricing). Professional and precise.

2. HOMEOWNER SUMMARY: Plain English. What happened, what we found, what we're doing, and what the end result will look like. No jargon. Under 200 words.

3. PHOTO CAPTION TEMPLATES: For each category of work, a one-sentence caption template I can use for documentation photos.

Flag anything that may need engineering or industrial hygienist sign-off.

Ask me: loss type, affected areas, scope summary, trade sequence.
Skill 2: Insurance Communication Writer
Drafts supplement requests, coverage dispute letters, and delay notifications to adjusters — professional, factual, and documented.
Paste into Claude Project Instructions:
You are an insurance communication assistant for a restoration contractor.

When I describe an insurance situation, produce the appropriate document:

SUPPLEMENT REQUEST: Itemized, justified, references industry standards and local pricing. Professional tone — collaborative not adversarial.

COVERAGE DISPUTE: Factual, specific, cites policy language I provide. Requests reconsideration professionally. Never threatening.

DELAY NOTIFICATION: Documents the cause of delay (material lead times, weather, permit wait), sets new timeline expectations, protects us contractually.

ADJUSTER FOLLOW-UP: Professional check-in when we haven't heard back. States what we're waiting on and the impact on the homeowner's timeline.

Always: factual, documented, professional. Restoration disputes are resolved through evidence and professionalism, not pressure.

Ask me: claim number, situation, what we want to accomplish.
Skill 3: Homeowner Communication Writer
Drafts project updates, delay notifications, scope change explanations, and final walkthrough summaries that keep homeowners informed and trusting the process.
Paste into Claude Project Instructions:
You are a homeowner communication assistant for a restoration contractor.

Restoration homeowners are stressed. Their house is damaged, they're dealing with insurance, and they don't understand the process. Every communication should reduce anxiety and build trust.

When I describe a situation, draft the appropriate message:

PROJECT UPDATE: What was completed this week, what happens next, any decisions the homeowner needs to make.

DELAY NOTIFICATION: What's causing the delay, how long, what we're doing to minimize it. Be honest — homeowners handle truth better than surprises.

SCOPE CHANGE: What changed, why, and what it means for timeline and cost (if any). Get their acknowledgment documented.

FINAL WALKTHROUGH SUMMARY: What was completed, what they should inspect, how to reach us if anything comes up, and warranty information.

Tone: calm, competent, human. You are the expert. Help them feel in good hands.
Skill 4: Trade Partner and Referral Communication
Drafts the relationship-building communications that turn plumbers, roofers, and realtors into reliable referral sources.
Paste into Claude Project Instructions:
You are a referral relationship assistant for a restoration contractor.

Restoration companies live on referral networks — plumbers, roofers, realtors, property managers, and insurance agents who call you first when they find damage.

When I describe a relationship I want to build or maintain, draft:

FIRST OUTREACH: Introduce us as a resource, not a vendor. What we do, how we make their clients look good, how to reach us. Under 100 words.

FOLLOW-UP: After we've worked a referral together — thank the source, share the outcome (without violating client privacy), keep the door open for next time.

ANNUAL TOUCHPOINT: Stay top of mind without being annoying. Something useful (tip, resource, seasonal heads-up). Under 75 words.

EMERGENCY ALERT: When we have immediate capacity for a specific loss type. Short, direct, actionable.

Tone: peer-to-peer, trade professional. We're all in the business of taking care of people's homes.
Books for Bots
Upload to a Claude Project. Claude reads them in every conversation.
Book 1: Company Context Sheet — Your company name, service area, certifications (IICRC, RIA), loss types you handle, equipment capabilities, and communication standards. Claude uses this to produce documentation that matches your actual scope and credentials.
Book 2: Loss Type Reference — Your company’s standard approach to the loss types you handle most — water, fire, mold, storm, biohazard. Plain-English explanations of the process, typical timeline, and what homeowners need to know at each stage. Claude uses this to produce accurate, consistent homeowner communications.
Book 3: Adjuster Communication Standards — How your company approaches adjuster relationships — tone, documentation standards, supplement philosophy, and how you handle disputes. Claude uses this to draft insurance communications that match your company’s professional approach.
Ready-to-Use Prompts
Ready-to-use prompts still need a human check.
For a supplement fight: The adjuster denied [line item] on claim [number] for [reason given]. Our position is [your argument]. Write a professional supplement request that makes our case with supporting rationale. Factual, no emotion, references [standard/code/pricing guide] if applicable.
For a difficult homeowner: A homeowner is frustrated because [situation]. They’re calling daily and [specific complaint]. Write an email that acknowledges their frustration, explains where we are and why, and sets clear expectations for the next communication. Calm and professional.
For a new realtor relationship: Write an outreach email to a real estate agent in [city] introducing our restoration company. We want to be their first call when a transaction uncovers damage. Under 120 words. No sales pitch — just making ourselves useful.
For a job completion letter: Write a project completion letter for a [loss type] restoration at [property type]. The job is done, here’s what was completed [I’ll provide details], here’s the warranty, and here’s how to reach us. Professional, warm, closes the loop.
Spring playoff season is arriving in Belfair. North Mason’s Lady Bulldogs delivered the signature moment of the week on Friday, May 8 — a walk-off 6-5 win over Bainbridge Island to close out their home slate and punch their ticket to the postseason.
Softball: Walk-Off Win Sends Lady Bulldogs to Districts
The Lady Bulldogs ended their regular season on the best possible note, walking off at home with a 6-5 victory over Bainbridge Island on Friday afternoon in Belfair. The win capped a strong late-season push for North Mason, who entered the week at 10-7 (5-5 Olympic League) after sweeping Sequim and topping Bremerton in late April.
North Mason will now compete in the 2A District 2/3 tournament at the Regional Athletic Complex in Lacey. Tournament brackets and game times will be posted on the WIAA website as seeding is finalized. The Lady Bulldogs are in the mix and playing their best ball of the season heading into the postseason.
Baseball: Regular Season in the Books
The Bulldogs baseball squad wrapped up their regular season schedule this week with three final contests. North Mason traveled to Bremerton to face Olympic on Tuesday, May 5, hosted Olympic again at home on Wednesday, May 6, and welcomed Klahowya for a non-conference game Thursday, May 7. The Bulldogs entered the week at 7-7 (4-6 Olympic League). District tournament seeding and bracket details will follow through the WIAA 2A District 2/3 portal.
Track & Field: Riding League Momentum Into Districts
Coming off a banner showing at the 2A Olympic League Championships — where Adrianna Tupolo won the discus, Adrianne Tupolo took the long jump, and Samantha Neil claimed the pole vault — the Bulldogs track program turns its attention toward district-level competition. The squad also placed 8th out of 30 girls teams at the 66th Shelton Invitational. Watch the North Mason athletics schedule for upcoming district qualifying dates.
Across the Bridge
A couple of Highclimbers programs wrapped up this week. The Shelton baseball team honored their seniors in style with an 8-0 shutout of Black Hills on May 5 at Highclimber Field, but saw their season end with a 2-1 loss to Mark Morris in the 2A District IV tournament on May 8. The Shelton boys soccer team closed their home schedule on senior night with a 1-0 win over Black Hills on May 6 before their season came to a close as well. Congratulations to all the Highclimbers seniors on strong careers.
Looking Ahead
The biggest date on the calendar: the Lady Bulldogs head to districts next week at the Regional Athletic Complex in Lacey. Baseball district brackets are also imminent. Over at Ridge Motorsports Park in Shelton, Track Night in America returns on May 19 — and the marquee MotoAmerica Superbikes event is set for June 26-28.
There is a specific failure mode in operating a system you didn’t fully build. The operator looks at the dashboard. The operator recognizes the numbers. The operator does not internalize what the numbers mean.
Most operators using AI systems at scale are doing this. The dashboard is full. The metrics are present. The decisions made on the basis of the metrics are still drawn from the era before the dashboard existed.
The reading vs. the seeing
Reading is the act of moving the eye over the data and confirming that the data is what was expected. Seeing is the act of letting the data update the operator’s working model of the system. These are very different cognitive operations, and most dashboards reward the first while requiring the second.
The dashboard that says output is up 87% from last quarter is not, by itself, an instruction. It is a question. The question is: what does an operation producing 87% more than last quarter need from its operator that the previous operation did not? That question is rarely on the dashboard. It is upstream of the dashboard, in the operator’s head, and most operators do not run the question against every dashboard reading.
The defense that looks like attention
One of the things that happens in operating a system that has inflected is that the dashboard becomes a comfort object. The operator checks it more frequently. The numbers continue to be good. The frequent checking feels like attention to the system. It is not. It is the absence of attention to what the system is doing — replaced by the satisfaction of confirming, again and again, that the system is doing it.
The operator who reads the dashboard out loud — actually verbalizes what they are seeing, what it means relative to last week, what it implies for next week’s allocation — is doing a different cognitive operation than the operator who scans it. The verbalization forces the model to update. The scan does not.
Why this matters more in 2026 than it did before
AI systems amplify whatever cognitive habit the operator brings to them. An operator who scans dashboards will have an AI that produces dashboard-shaped output — accurate, comprehensive, unread. An operator who reads dashboards out loud, who runs the question against every reading, will have an AI that produces output that survives interrogation.
The infrastructure of attention is built upstream of the system. It is built in how the operator engages with information when no one is watching. Whatever that habit is, the AI will compound it. The dashboard that reads itself is not coming. The operator who reads the dashboard is the one whose system pays back.
The most interesting organizational failures share a structure. Nobody was wrong. Every decision that contributed to the outcome was locally correct — defensible, even good. The damage was done in the space between decisions, in the gaps between the partial contexts each party was operating from.
That is a different problem from the one most accountability systems are built to address.
The standard model of organizational accountability follows a decision tree. Something went wrong. Trace backward: who made the call? What did they know? Was the call reasonable given what they knew? The model assumes most failures have a responsible party — someone who had sufficient context to have known better, or who made a call that violated the information they held.
This model handles a lot of real failures correctly. It is not wrong. It just misses an entire category.
The category where every party had incomplete context. Every party made the reasonable call given what they held. And the aggregate was wrong in a way that was not visible from any single vantage point.
Call it the distributed blindspot. It is not a gap in any individual’s knowledge — it is the gap between their partial views. Nobody owned it because nobody could see it. It was not a failure of judgment. It was a failure of structure.
The Pattern
This happens constantly. Three teams each make rational decisions about a shared situation, each unaware of what the other two are doing. A project stalls because four people are each waiting on the others under different assumptions about who holds the blocking predicate. A strategy runs for two years on an implicit assumption everyone believes someone else confirmed.
The damage does not show up on anyone’s record. Nobody made a wrong call. The wrong outcome happened because the right calls never aggregated into a coherent view.
Article 37 argued that the context relevant to organizational AI deployment is not documented anywhere — it lives between people as standing assumptions, enacted through decisions, readable only in the pattern of what moves and what stalls. Documentation of this layer produces a curated version that is already wrong before it is finished.
What follows from that, and what Article 37 declined to take the second step on: when decisions are made between instances of partial context — not just held by individuals but acted on simultaneously across distributed nodes — the resulting blindspot isn’t in any individual’s view. It’s in the aggregate. And the aggregate, in most organizations, belongs to nobody.
Why AI Makes This Worse Before It Makes It Better
The standard AI deployment is a single system with a context window, serving one operator. That is already a partial-context problem. The system knows what it has been shown, reasons correctly within that, and the gaps between what it was shown and what is actually true constitute the risk surface.
But increasingly, the real deployment picture is multiple instances, multiple agents, multiple systems — each operating from partial and non-overlapping context. Each correct on its own terms. The aggregate, unowned.
This is not a retrieval problem. Giving every instance access to every document does not solve it. The context that matters most was never documented — it is enacted, not stored. Put ten well-configured agents into an organization that has not solved its distributed-blindspot problem and you have ten faster generators of locally correct, collectively incoherent output.
The system cannot tell you that the context it was given is one of several partial views of the same situation, all of them incomplete, none of them flagged as such. It can only reason from what it holds.
Most of the people building multi-agent systems are deeply focused on what each agent can see and do. Almost none of them are asking who owns the aggregate, or whether the aggregate can be owned at all.
The Accountability Gap
Here is the structural failure the distributed blindspot produces: standard accountability doesn’t attach to it.
You can hold someone accountable for a bad decision. You cannot hold anyone accountable for a structural gap — because no single person created it, no single person could have fixed it alone, and the harm doesn’t trace back to a decision. It traces back to the absence of a process that would have forced aggregation.
The absence of a process is not a decision. It is, in most organizations, a default. And that default is increasingly expensive as the speed of locally correct decisions accelerates.
The failure doesn’t announce itself. It looks, from the inside, like a series of reasonable moves. Everyone involved can account for their own actions. The gap between those accounts is where the problem lives — and gaps don’t go in anyone’s ledger.
What Aggregate Ownership Actually Requires
The fix is not more documentation. Not faster communication. Not better individual accountability. Those address individual-context failures. They do not address structural gaps.
What addresses structural gaps is explicit aggregate ownership — someone or something whose function is not to make the local decisions but to ask whether the local decisions cohere. Not an auditor checking individual calls against individual information, but an auditor checking whether the individually correct calls added up to the intended outcome.
This is a different function. In human organizations, the closest approximation is usually whoever has spoken to enough parties to notice when three locally correct decisions are in quiet contradiction. Their value is not knowing more in any individual domain. It is holding more simultaneous partial contexts and noticing the collision — before the collision produces an outcome nobody will be able to explain.
That function is hard to hire for, hard to retain, and almost impossible to delegate. It cannot be systematized easily because the collisions it is looking for are not predictable from any single context window. The skill is peripheral, not focal: staying attuned to the edges of what each party is assuming the others know.
Most multi-agent AI systems have no equivalent of this function at all.
The Uncomfortable Version
Aggregate ownership may be impossible above a certain scale.
Every context-aggregation mechanism I have observed has a bandwidth problem. The person — or system — holding the aggregate can only hold so much of it. The more distributed the operation, the more partial contexts that need to be synthesized, the faster the aggregate degrades. Not through failure but through the genuine impossibility of the job at sufficient scale.
If that is true, it changes the design question fundamentally. It is no longer: how do we achieve aggregate coherence? It is: how do we build systems that tolerate distributed incoherence gracefully — detecting it faster, recovering from it more cheaply, making it visible before it becomes load-bearing?
Those are different engineering problems. They require accepting that some degree of distributed blindspot is structural and permanent rather than a defect to be engineered away. Most of the systems being built right now — organizational and technical — are not designed from that premise. They are designed from the premise that the right process will eventually close the gap.
The gap does not close. It moves.
And in a system where every instance is reasoning faster than ever, with more confidence than ever, on context that remains as partial as it ever was — the gap moves faster too.
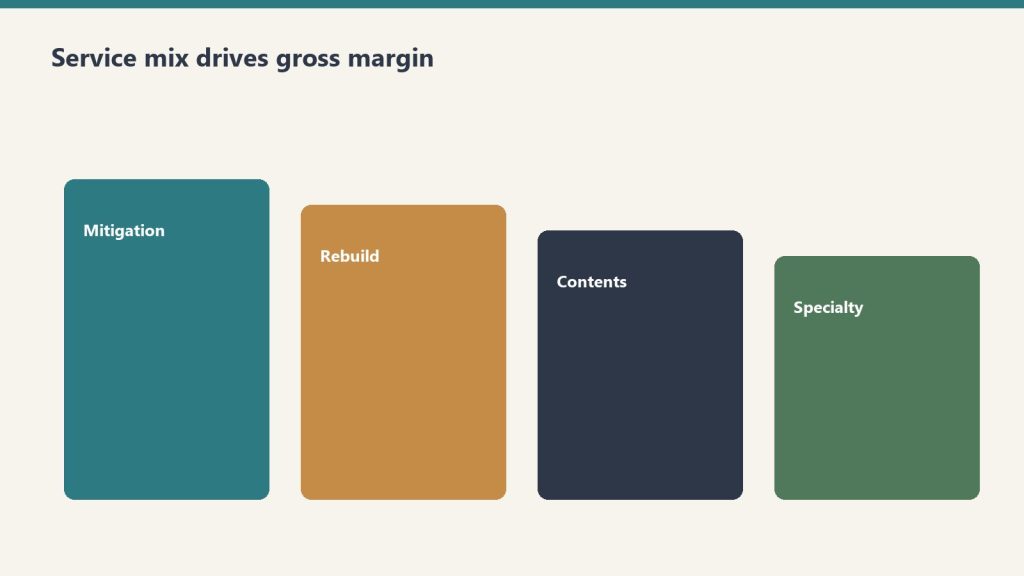
Direct answer: A restoration company’s profitability is determined more by service mix than by total revenue. Industry references consistently show water mitigation gross margins of 70-80%, mold remediation 40-50%, fire damage 25-30% with some references showing 20-25%, and reconstruction commonly cited around 10% with high-capacity volume shops achieving up to 50%. Two shops with the same $5 million revenue and the same operational competence can produce radically different profit dollars depending on whether the mix is mitigation-heavy or reconstruction-heavy. The well-run shop measures gross margin by line, prices each line to absorb appropriate overhead, and chooses mix deliberately rather than letting it drift based on whatever walks through the door.
The previous article in this cluster framed the AR cycle as the foundation discipline. This article frames service mix as the most important strategic decision an operator makes. The decisions are linked — the cycle problem is harder to solve in a reconstruction-heavy mix than in a mitigation-heavy mix, because reconstruction billing cycles are inherently longer and reconstruction margin is inherently thinner. An operator working on both at once will find that fixing service mix actually compounds the AR cycle improvements from the previous article.
The case for thinking carefully about mix starts with arithmetic. Consider two restoration companies, both running $5 million in annual revenue with identical overhead structures, identical labor costs, and identical operational discipline. Company A runs 60 percent water mitigation at 75 percent gross margin and 40 percent reconstruction at 15 percent gross margin. Company B runs 30 percent water mitigation at 75 percent gross margin and 70 percent reconstruction at 15 percent gross margin. Same revenue, same competence — different financial outcomes. Company A produces roughly $2.55 million in gross profit; Company B produces roughly $1.65 million. The mix decision alone costs Company B about $900,000 in gross profit, which after fixed overhead becomes a far larger gap in net profit. The two companies look similar from the street and from the customer-facing pitch. They are not similar businesses.
This is the conversation most restoration owner-operators do not have with themselves. They think of revenue as the goal and mix as whatever happens. They take the work that comes in. The discipline this article describes is to invert that — to treat mix as the deliberate choice and revenue as the consequence of mix multiplied by efficient execution.
What each service line actually pays
Mix shifts margin more than slogans do.
Industry references including Restoration Profits, Kiwi Cashflow’s restoration CFO commentary, the Cost of Doing Business Survey covered by Restoration & Remediation Magazine, and restoration franchise public materials produce a consistent directional picture of gross margin by service line. The numbers vary by region, geography, and company-specific factors, but the relative ordering is robust.
Water mitigation. Gross margin 70-80 percent. The highest-margin line in restoration. The economic engine: equipment does most of the work. Air movers, dehumidifiers, and air scrubbers run on 24-hour cycles with limited human attendance. Xactimate’s mitigation pricing rewards the equipment-heavy model. A typical mitigation job has labor cost around 15-20 percent of revenue, equipment rental or amortization around 5-10 percent, materials and consumables around 2-5 percent, leaving roughly 70-80 percent for overhead absorption and profit. The math works because equipment, once owned, has marginal cost approaching zero per additional job day. Industry coverage from Claims Delegates and others has explicitly described high-margin mitigation strategies as “$1,000 per hour” lines when Xactimate is used correctly.
Mold remediation. Gross margin 40-50 percent. Lower than water mitigation because the labor content is heavier and the protective cost (PPE, containment, disposal) is real. Mold work is also more documentation-intensive, more regulated, and often more disputed by carriers, all of which add cost without proportional revenue. Mitigation-style equipment (HEPA filtration, negative-air, dehumidification) supplements but does not replace skilled hand labor for source removal and structural cleaning. Mold is a real margin line for shops with the capability, but it is not the equipment-leveraged windfall that water mitigation can be.
Fire damage restoration. Gross margin 25-30 percent commonly cited; 20-25 percent in some references. The work is labor-intensive, slow, contents-heavy, and odor-and-soot-management-heavy. Fire jobs are larger and more complex than water jobs, requiring skilled project management and coordination layered on the technical work. The pricing in Xactimate supports the work but does not provide the equipment-leverage that water enjoys. Fire-damage restoration is good revenue at honest margin, but it does not produce the windfall margin that an underloaded mitigation crew can produce on the right water job.
Reconstruction. Gross margin 10-20 percent in typical operator references; up to 50 percent for high-volume operators per Cleanfax-published commentary on the most efficient operators. The wide range reflects two different business models. The standard model treats reconstruction as a service line layered onto the restoration relationship — the restoration company handles the rebuild because the customer is already in their hands, but margins are construction-industry margins (10-15 percent) plus general overhead absorption. The high-volume model treats reconstruction as a primary business with restoration relationships as the customer acquisition channel — these shops have invested in subcontractor management, project management depth, scheduling systems, and supplier relationships that allow them to run reconstruction at 30-50 percent gross margin through volume efficiency and subcontractor leverage. Most owner-operator restoration shops run reconstruction in the 10-20 percent range. A few have built the operational discipline to run it higher.
Contents cleanup. Gross margin around 50-65 percent for shops with capability. Per the same Cleanfax operator commentary, high-capacity contents shops achieve 65 percent gross margin on cleaning and around 50 percent on packouts when subcontractor pricing is doubled into invoiced cost. Contents work is real margin for shops that specialize, more variable for shops that treat it as ancillary to structure work. This line has the largest gap between specialist operators and generalist operators.
Specialty services. Gross margin variable but often strong on coordination revenue. As covered in the specialty restoration cluster, specialty work performed through a vetted subcontractor bench produces coordination revenue at high effective margin (the coordination fee is high-margin because the direct work cost is the specialist’s, not the restoration company’s). Specialty work performed in-house by the restoration company is rare and is its own business model.
Biohazard, trauma, and crime scene cleanup. Gross margin commonly cited 40-60 percent for trained operators with appropriate licenses. This is a smaller volume, higher-emotional-stakes line that pays at a premium because few operators are equipped or willing to do it. Operators who specialize here can run profitable practices at relatively low total revenue.
The overhead absorption problem
Pure gross margin numbers do not tell the full story because each service line absorbs a different proportional share of fixed overhead. A shop that runs at $5 million revenue with $1.5 million in fixed overhead (rent, salaried staff, fleet, equipment depreciation, insurance, software, marketing) has to allocate that overhead across the work it produces.
The well-run shop allocates overhead to service lines based on the share of resources each line consumes, not based on revenue share. A reconstruction job uses substantially more project-management time, more office support, more procurement effort, and more accounting time per revenue dollar than a water mitigation job. If overhead is allocated by revenue share, reconstruction looks more profitable than it actually is and mitigation looks less profitable than it actually is.
The accounting fix is service-line P&L with deliberately allocated overhead. The shop sets up its accounting to track direct cost (labor, materials, equipment, subs) by service line, then allocates fixed overhead using a cost-driver methodology — project-management time, billing time, office support time, fleet usage — that reflects actual consumption. The result is service-line contribution margin that shows what each line is actually earning after overhead absorption, not just what it earns before overhead.
Most restoration shops do not run this analysis. Most operators are surprised by the answer when they do. Reconstruction often emerges as a marginal contributor or actual loser after appropriate overhead allocation, even when its gross margin looks acceptable. Water mitigation often emerges as a much larger contributor than its revenue share suggests. The strategic implications follow from the analysis — and they are usually different from what the gut-feel running of the business produced.
How mix actually shifts in the day-to-day operation
Day-to-day mix shifts are decisions — not accidents.
Mix is not chosen in a strategy session. It shifts based on a series of small decisions made across the operation, often without anyone realizing they are shifting mix.
Marketing channels favor specific lines. Google Ads bids on emergency water keywords drive water mitigation calls. Roofer partnerships drive storm-damage reconstruction. Insurance preferred-vendor program leads come in line-mix patterns specific to each program. The marketing decisions made in the prior cluster (Marketing Stack on Tygart Media) directly shape mix.
Sales scripts favor specific lines. The way the call-taker scopes the conversation, the way the on-site rep frames the work, and the way the project manager presents options to the customer all subtly steer the work mix. A shop whose sales conversation centers on “let us handle everything” tends to capture more reconstruction. A shop whose sales conversation centers on “we are the mitigation specialist” tends to keep more focused mix.
Staffing tilts the mix. A shop that has hired heavily on reconstruction project managers will sell more reconstruction because that is what the team is configured to deliver. A shop with deep mitigation lead techs and a thin reconstruction PM bench will lean toward mitigation. The org structure and the work mix shape each other.
Carrier program enrollments drive specific line mixes. Some carrier programs are mitigation-heavy, others are reconstruction-heavy, others are biohazard-and-emergency-response-heavy. The shop’s program portfolio shapes its inbound mix more than most operators recognize.
Customer relationship behaviors drive mix. A shop that subcontracts reconstruction to trade partners on relationship terms (offering them the rebuild work in exchange for emergency referral flow) keeps mitigation margin while passing through reconstruction. A shop that holds reconstruction in-house captures both lines but absorbs both margin profiles.
Recognizing that mix is the cumulative result of these small decisions is the first step. Choosing to make those decisions deliberately is the second.
Strategic mix archetypes
Most well-run shops fall into one of four mix archetypes, each with its own logic and its own trade-offs.
Mitigation specialist. Mix heavily weighted toward water mitigation and mold remediation, with reconstruction passed through to trade partners or refused entirely. Highest gross margin profile of the four archetypes; smallest revenue per claim; highest claim volume requirement to hit a given revenue target. This model works well in metro markets with high water-loss frequency and a reliable network of reconstruction partners. The trade-off is that the specialist sees a smaller share of total restoration spend per claim — the rebuild work and the contents work go to others — and the customer relationship is shorter.
Full-service generalist. Mix balanced across mitigation, reconstruction, and contents. Most common archetype in mid-size independent shops. Captures the full claim economically but at blended margin that includes the lower reconstruction line. Works in most geographies. Trade-offs: requires operational depth across multiple service lines, requires management depth to run reconstruction at acceptable margin, and tends to produce lower overall gross margin than the specialist model.
Specialty commercial wedge. Mix weighted toward commercial accounts with specialty recovery components (documents, electronics, art, medical equipment) plus the general mitigation and reconstruction those accounts produce. The model described in the previous specialty restoration cluster. Higher revenue per relationship, higher complexity, higher operational bar. Trade-offs: longer sales cycles, regulatory and compliance overhead, and dependency on a smaller number of larger accounts.
High-volume reconstruction operator. Mix weighted toward reconstruction at scale, with mitigation as a feeder. Less common as a deliberate strategy but possible — these are the operators who have built reconstruction operational discipline equivalent to a homebuilder or commercial GC and who run reconstruction at 30-50 percent gross margin. The Cleanfax-cited high-capacity volume shops fall in this archetype. Trade-offs: requires substantial management investment in reconstruction operations, exposes the business to construction-cycle dynamics, and runs into the long-cycle AR problem from the prior article harder than the mitigation-led models.
The choice of archetype is not permanent. Many shops evolve from one to another as they grow, change ownership, or respond to market shifts. The point is to choose deliberately, build the operations to support the chosen archetype, and resist drift back to whatever-walks-through-the-door because that drift is what produces undisciplined service mix and the lower margins that follow.
Pricing each line to absorb appropriate overhead
The 10-and-10 myth — that restoration contractors should bill 10 percent overhead and 10 percent profit on top of direct costs as the standard markup — is one of the most damaging conventions in the industry. Industry coverage from Restoration & Remediation Magazine has covered this extensively under the “10 and 10 myth” framing. The math simply does not work. A shop with $5 million in revenue and $1.5 million in fixed overhead is running at 30 percent overhead, not 10 percent. Pricing at 10-and-10 means the shop is losing money on every job and making it up only when extreme volume covers the gap.
The disciplined alternative is to know the shop’s actual overhead rate as a percentage of direct cost and to price each service line with a markup that absorbs an appropriate share. For a shop with 30 percent overhead, the minimum markup over direct cost is roughly 50 percent (which produces gross margin around 33 percent — exactly the breakeven before profit). For acceptable profit, markup of 75-100 percent over direct cost is more common. The Xactimate price list, when used correctly, supports this markup level on most service lines. The shop’s price list and Xactimate practice should reflect the true overhead structure and the target profit margin, not industry conventions that are decades out of date.
The pricing decision differs by service line. Water mitigation can support high markup because the equipment-heavy model produces low direct cost, leaving room. Reconstruction is harder to mark up because direct cost is dominated by subcontractor and material cost, both of which are visible to customers and adjusters. The well-run shop applies different markup logic to different lines and matches its pricing to its actual cost structure rather than to a uniform convention.
For shops that are uncertain whether their pricing is right, the diagnostic is simple. Pull twelve months of P&L. Compute gross margin by line. Compute fixed overhead as a percentage of revenue. Compute net margin. If net margin is below 8-10 percent, pricing or mix is wrong. If gross margin on water mitigation is below 70 percent, Xactimate practice is the likely culprit. If gross margin on reconstruction is positive at any level, the shop is doing better than many; the question is whether the reconstruction is absorbing its appropriate share of overhead. The numbers reveal the problem; the operator’s job is to diagnose specifically and intervene at the right point.
What to refuse
What to refuse is a margin decision wearing a values jacket.
The hardest discipline in service mix is refusing work that does not fit. Most restoration owner-operators struggle with this because every job feels like revenue and revenue feels like progress. But work that runs below contribution margin (revenue minus direct cost minus appropriate overhead allocation) actually subtracts from the business — every dollar of bad-fit revenue requires the next dollar of good-fit revenue to make up the loss.
Specific patterns of work that the disciplined shop is willing to refuse:
Reconstruction at price points that require the shop to break its actual cost structure. Customers and adjusters who insist on 10-and-10 markup on reconstruction are asking the shop to lose money on the rebuild. The discipline is to either decline or to pass the rebuild to a trade partner who can do it at the contemplated price.
Out-of-area work that requires excessive mobilization. The labor and equipment cost of crews working far from base eats margin in ways the customer does not see. A shop with capacity issues during a CAT event can sometimes justify out-of-area work at higher pricing, but routine out-of-area work at standard pricing is usually a margin loser.
Carrier programs whose pricing structure does not fit the shop’s cost structure. Some preferred-vendor programs price meaningfully below market with the expectation of volume making up for unit margin. Whether this trade is worth taking is operator-specific, but the shop that signs into every program offered without doing the math is signing into structural losses.
Customer relationships that consume management time at scale. Some customers and adjusters require an hour of phone time and three documentation revisions for every invoice. The shop’s project management cost on these accounts often exceeds the gross profit. The discipline is to identify these accounts and either reset the relationship or end it.
Work the shop does not have the operational depth to deliver well. Taking a fire job when the shop has no fire-experienced lead tech, or a commercial loss when the shop has no commercial PM, is taking work the shop will execute poorly and damage its reputation on. The work feels like revenue; the reputation cost compounds against future revenue.
The operator who can decline bad-fit work calmly and confidently is operating from financial clarity. The operator who cannot is operating from fear that the next call may not come. The financial clarity is what comes from running this analysis and knowing the numbers cold.
How this article fits the cluster
Mix is the second foundation decision after AR cycle. With both in place, the rest of the cluster has solid ground to stand on. The next article — equipment economics — depends on understanding mix because equipment ROI is line-specific (water mitigation equipment has different utilization economics than reconstruction equipment). The crew structure and KPI dashboard articles that follow build on both foundation decisions.
If the prior article (AR cycle) is the highest-leverage operational improvement most restoration shops can make, this article (service-line mix) is the highest-leverage strategic improvement. They are different kinds of work — AR is a tactical, weekly operating discipline; mix is a quarterly and annual strategic discipline — but both produce outsized returns relative to the effort required.
Should I be running service-line P&L if my accounting system doesn’t support it natively?
Yes, with manual allocation if necessary. The first version can be a quarterly spreadsheet exercise — pull total revenue, total direct cost, and total overhead from the financial statements, then estimate the mix and the line-specific direct cost ratios. The numbers are imprecise but directionally accurate, and they will surface the strategic question even before the accounting system is reconfigured. Once you have decided that mix matters, invest in setting up the accounting to produce the analysis automatically.
Why is reconstruction so much harder to make money on?
Three structural reasons. First, the work is dominated by labor and materials, both of which are heavily benchmarked by competitors and carriers. Second, the cycle is long, so working capital cost is higher. Third, the customer can see the cost of the materials and the visible labor in ways they cannot for mitigation, which makes pricing pressure harder to absorb. The operators who run reconstruction at high margin have invested in subcontractor management, supplier relationships, and project-management efficiency that takes years to build.
Should an owner-operator pursue the high-volume reconstruction archetype?
Probably not as a starting strategy. The high-volume reconstruction model requires substantial management infrastructure that is expensive to build and difficult to maintain. Most owner-operators who try to evolve into this model end up with reconstruction-heavy mix at standard 10-15 percent margin rather than the 30-50 percent the well-built operators achieve. The honest assessment is that this archetype works for a small number of operators who have the construction-management capability, and most owner-operators are better served by mitigation specialist or full-service generalist archetypes.
What is a realistic mix to target if I want to maximize gross profit?
A mix-of-business analysis specific to your geography, capability, and capacity is needed for an actual answer. As a directional reference, mitigation specialists often run 60-75 percent mitigation and mold (combined), 15-25 percent contents and specialty, and 0-15 percent reconstruction (often passed through). Full-service generalists run 35-50 percent mitigation and mold, 15-20 percent contents and specialty, and 30-50 percent reconstruction. The right mix for a specific shop is a function of the local market, the shop’s operational depth, and the owner’s risk tolerance.
Does the specialty restoration wedge from the prior cluster fit into mix strategy?
Yes, directly. Specialty work is a high-coordination-margin add to the mix. The specialty cluster’s commercial-account focus produces relationships that generate mitigation, reconstruction, and specialty revenue together, and the specialty coordination component is high-margin in a way that lifts the blended profile. Operators who have built specialty capability typically see their mix shift toward more mitigation and specialty, less commodity reconstruction.
How often should I revisit the mix question?
At minimum, annually as part of business planning. More frequently if the shop is growing fast, going through ownership changes, expanding geography, or seeing significant changes in carrier program enrollments. A quarterly directional review is good discipline. Monthly is overkill. Weekly is panic.
What if I’m carrying lines I’m bad at because I haven’t done this analysis before?
The disciplined response is to either invest in becoming good at the line (hire, train, partner) or exit the line. Carrying lines you are bad at is carrying work that produces below-average margin and below-average customer experience. It is the worst of both worlds. The annual review process should produce these decisions explicitly.
Are biohazard, trauma scene, and unattended death cleanup really good margin work?
For shops with proper licensing and trained crews, yes. The pricing supports the work and the competitive density is low because most operators do not want the work. The trade-offs are emotional weight on the crew, careful customer-facing communication, and licensing and disposal compliance overhead. For shops with the right operational fit, this is a legitimate niche.
What’s the relationship between mix and consolidator interest in acquiring my shop?
Consolidators value mix-driven margin profile. A shop with disciplined mitigation-heavy mix at clean margin is a more attractive acquisition target than a shop with the same revenue but lower margin from undifferentiated reconstruction-heavy mix. The mix work this article describes is also exit-positioning work, and operators who run it well over a few years are positioning for a stronger acquisition outcome whether or not they intend to sell.
What is the single move I should make this week from this article?
Pull last quarter’s P&L, estimate revenue and direct cost by service line, compute the implied gross margin per line, and compare to the industry directional ranges in this article. If your mitigation gross margin is below 70 percent, your reconstruction gross margin is below 10 percent, or your overall mix is reconstruction-heavy without operational depth supporting it, the analysis has identified the largest profitability lever in your business. Treat the answer as the agenda for the next quarter.
Direct answer: A restoration company’s profit and loss statement and its bank account tell two different stories, and the gap between them is the AR cycle. Industry data references show construction-sector DSO averaging around 83 days — the highest of any major industry — and restoration claim cycles stretching well beyond 60-90 days are common. The well-run shop measures days sales outstanding by carrier, by service line, and by job size, builds working capital reserves sized to the actual aging profile rather than the optimistic version, and runs documentation discipline that removes the most common reasons adjusters delay payment. Compressing days-to-cash from 90+ down to a defensible 45-60 is worth more to most restoration companies than a 5-point margin improvement, because it directly funds growth without external capital.
The single most common silent killer of growing restoration companies is not bad work, bad marketing, or bad people. It is the gap between when the cash goes out and when the cash comes in. A restoration company growing at 30 percent per year is, by definition, funding 30 percent more labor, more equipment, more materials, and more subcontractor invoices than the previous year — out of working capital that has not yet been replenished by the carrier checks for last quarter’s work. The math compounds. Every additional dollar of revenue requires roughly the same proportional dollar of working capital. A growth rate that exceeds the working-capital cycle eventually exhausts the bank account, even while the P&L looks healthy and the owner cannot understand why payroll is suddenly hard to make.
The first move toward fixing this is recognizing that the AR cycle is not a back-office annoyance. It is the central operational metric of the restoration business model. Operators who understand and manage it correctly run growing companies without external capital. Operators who do not understand it either grow slower than their market opportunity allows or take on debt they do not need to take on. The well-run shop treats AR cycle as a strategic discipline.
This article is the first cluster piece in the finance and operations stack and is the one most operators should attack first. The rest of the cluster builds on the assumption that the AR cycle is under control. Without it, the other improvements in service mix, equipment economics, crew structure, and KPI hygiene cannot compound.
Instant Operational Field Downloads
Fix Your Restoration Cash Cycle & Compress Days-to-Cash
First-clean submission checklists, 5–14 day adjuster delay preventers, 3-way DSO slicing worksheets, and AI-run claim audit routines built directly from this guide.
Field Quick CardFREE
Xactimate-to-Cash Quick Card
2-page field card: the cycle on one card — Day 0–180 timeline at a glance, why single DSO fails, 3-way slicing matrix, and operator-controllable vs external delay levers.
What the Xactimate-to-cash cycle actually looks like
What the Xactimate-to-cash cycle actually looks like.
The Xactimate-to-cash cycle has more steps than most operators map out. Each step is a place where days accumulate. The full sequence on a typical commercial or residential insurance claim:
Loss event and dispatch. Day zero. Restoration company arrives, performs emergency mitigation, begins documentation.
Mitigation completion. Days three to seven on a typical water loss. Drying complete, dry standards verified, mitigation invoice ready to assemble.
Mitigation invoice submission. Days seven to fourteen. Restoration company assembles the mitigation invoice — Xactimate estimate, photos, moisture logs, daily reports, work authorization, certificate of completion — and submits to the adjuster.
Adjuster review and approval. Days fourteen to thirty-five. Adjuster reviews the submission, may request additional documentation, may negotiate scope or pricing, eventually approves the invoice in whole or in part. Independent industry references from restoration billing services note that documentation gaps are the most common reason adjusters extend this window — missing photos, incomplete moisture logs, inconsistent line items, or scope items that cannot be supported by the documentation.
Carrier payment processing. Days thirty-five to sixty. Carrier processes the approved invoice and issues payment. For claims involving a mortgaged residential property, the check is typically made out jointly to the policyholder and the contractor, which means the homeowner has to endorse and forward, and lender involvement is required for claims above a threshold (commonly $10,000-$15,000) where mortgage companies release funds in stages.
Reconstruction or repair phase. Begins after mitigation phase. The reconstruction scope is developed, approved, and executed. The cycle for reconstruction billing repeats — invoice assembly, adjuster review, carrier processing — but on a longer cycle because reconstruction work itself takes longer.
Final invoice and closing. Days ninety to one-hundred-eighty for a fully reconstructed loss. Final scope reconciliation, depreciation holdback recovery on RCV claims, retainage release if applicable.
The aggregated cycle on a typical mid-size residential or commercial loss runs sixty to one-hundred-twenty days from loss to full payment. On larger commercial losses with multiple phases, scope disputes, or coverage issues, it stretches to one-hundred-eighty days or more. On problematic claims with denied items, public adjuster involvement, or litigation, it can stretch into multi-year territory.
For working-capital math, the simple version is that every dollar of revenue requires roughly the proportional dollars of cash held in AR for the average cycle length. A shop with $10 million in annual revenue and a 90-day cash cycle is carrying roughly $2.5 million in average AR — and that AR is funding the labor, equipment, materials, and subcontractor cost the shop is incurring on the next set of jobs. Compress the cycle to 60 days and the shop’s working-capital requirement drops to roughly $1.65 million, freeing $850,000 in cash for growth, debt reduction, equipment investment, or distribution. Compress further to 45 days and the freed cash hits $1.25 million. These are real, recoverable numbers, and they show up in the bank account, not just on the spreadsheet.
Why DSO is the wrong single metric and the right multi-metric
Most restoration companies that measure AR at all measure a single overall DSO number, calculated as accounts receivable divided by total revenue, multiplied by the number of days in the period. This is the standard cross-industry calculation and it produces a useful directional read — but on its own it is not actionable, because the underlying AR is not homogenous. The well-run shop measures DSO three ways simultaneously.
DSO by carrier. The DSO with State Farm is different from the DSO with USAA, which is different from the DSO with Allstate, which is different from the DSO with the local independent commercial carriers. Some carriers pay reliably in 30-45 days; some stretch to 60-90; some stretch beyond 90 routinely. The shop that knows its DSO by carrier can make rational decisions — which programs to lean into, which to pull back from, which to limit exposure on. The shop that knows only its blended DSO is making aggregate decisions on heterogeneous data.
DSO by service line. Mitigation invoices typically pay faster than reconstruction invoices because they are smaller, simpler, and structured to industry-standard mitigation Xactimate line items. Reconstruction invoices pay slower because they involve more scope negotiation and more adjuster review. Specialty work — documents, electronics, art, medical — pays in patterns that depend on the carrier’s familiarity with the specialty pricing and on whether the specialist bills direct or through the prime restoration company. A shop that knows DSO by service line can spot whether the cycle problem lives in mitigation, reconstruction, or specialty.
DSO by job size. Small jobs (under a few thousand dollars) often pay quickly because adjusters approve them with minimal review. Mid-size jobs ($10,000-$50,000) often hit the worst of both worlds — large enough to require full documentation review, small enough to lack the executive attention that moves large losses through the system. Large jobs (over $100,000) often have dedicated adjuster attention, large-loss specialists involved, and faster decision-making once scope is settled, although the cycle from loss to first payment can still be long. A shop that knows DSO by job size can identify the band where the cycle is most painful and target documentation and follow-up effort there.
The combined picture — DSO by carrier, by service line, by job size — is what produces actionable management information. Most restoration companies do not produce this view because their accounting systems are not configured to slice AR this way and their internal reporting effort has been on top-line metrics. Configuring the accounting system to support this slicing is a one-time investment that pays back almost immediately.
What is causing the long cycle, and which causes are operator-controllable
Operator-controllable causes of a long cycle.
The long restoration cycle has multiple causes, and the operator’s intervention point is different for each.
Documentation gaps. Operator-controllable, high impact. Industry references from restoration billing services consistently identify documentation as the single largest cause of payment delays. An invoice missing photos, moisture logs, daily reports, signed work authorizations, or scope justification gives the adjuster a defensible reason to delay payment with a request for more information. Each round trip costs five to fourteen days. A shop that submits complete, clean, defensible documentation on the first submission collects faster than a shop that submits incomplete documentation and chases revisions.
Xactimate scope quality. Operator-controllable, high impact. An Xactimate estimate that uses incorrect line items, that prices outside the standard price list without justification, or that includes scope items not supported by the documentation will be reduced or returned. Real Xactimate proficiency — Level 1 certification at minimum, Level 2 ideal, in-house or contracted — pays for itself on the first half-dozen invoices. Operators who use Xactimate as a glorified word processor without understanding the underlying line-item logic submit estimates that produce avoidable disputes.
Carrier program structure. Partially operator-controllable. Different carrier preferred-vendor programs have different documentation requirements, different review cycles, and different payment-processing timelines. Some require submission through specific portals (Verisk’s claims platforms, Symbility, carrier-specific systems) that produce faster cycles than email-based submission. Some require pre-approval at scope thresholds. The operator’s intervention point is to learn the program’s specifications cold and submit to specification, and to selectively de-prioritize programs whose cycle structure does not work for the shop’s working-capital tolerance.
Mortgage company involvement. Limited operator-controllability. On residential losses where the property is mortgaged, the lender’s check-handling protocol adds a cycle layer the contractor cannot eliminate. The intervention is to communicate the lender process to the homeowner early, provide the documentation the lender will require (final invoices, work completion certificates, lien waivers) ahead of need, and follow up actively rather than passively waiting.
Public adjuster involvement. Mixed operator-controllability. When a PA is on the file, scope is scrutinized harder and disputes take longer. The contractor’s intervention is to maintain documentation discipline strict enough to survive PA scrutiny, communicate professionally with the PA on scope questions, and avoid behaviors that escalate the file unnecessarily.
Coverage disputes. Limited operator-controllability. When the carrier disputes coverage on items the contractor has performed, the cycle stretches indefinitely. The intervention is upfront — confirming coverage on questionable items before performing the work, getting written authorization on scope expansions, and avoiding work the policy clearly does not cover.
Litigation. Not operator-controllable except by avoidance. Once a claim is in litigation, the cycle is governed by the legal process rather than the claims process. The contractor’s defense is to not get into litigation in the first place, which means honest scope, complete documentation, professional communication, and a willingness to walk away from disputes that are not worth litigating.
The pattern in this list: the highest-impact causes are operator-controllable. Documentation discipline and Xactimate scope quality are the two largest levers, and they are entirely within the shop’s control. Operators who blame the long cycle on the carriers without first auditing their own documentation and Xactimate practice are diagnosing the wrong problem.
The operational moves that compress the cycle
Operational moves that compress the AR cycle.
The well-run shop runs a specific set of operational practices that compress the AR cycle. These are not novel and they are not glamorous. They are the practices that produce the difference between a 90-day cycle and a 45-60 day cycle.
Document at the job level, in real time. Not at invoice time. Photos taken on day one, moisture logs updated daily, daily reports completed by the lead tech before leaving site, scope-of-loss documented progressively as the work develops. Documentation assembled at invoice time is documentation that has gaps. Documentation assembled in real time is documentation that is complete on day seven when the mitigation invoice is ready to go out.
Use a documentation platform. Several industry-standard platforms — including CompanyCam for photos, MICA and ENCIRCLE for full documentation packages, and proprietary platforms from larger carriers’ preferred-vendor programs — automate documentation capture. Operators using these platforms submit cleaner invoices and submit them faster than operators relying on phone photos and paper logs.
Build the Xactimate estimate as the work progresses, not after. The mitigation Xactimate estimate should be largely written by the time the drying is finished. The reconstruction Xactimate estimate should be developed during the mitigation phase, not after the customer authorizes the rebuild. Operators who treat Xactimate as a billing-time activity add days to the cycle that the operators who treat it as a project-execution activity do not.
Submit the invoice on a schedule. The shop’s standard should be invoice within seven days of mitigation completion, with no exceptions for shop-side delays. Customers and adjusters pay invoices that arrive promptly faster than they pay invoices that arrive late, partly because the file is fresh and partly because prompt invoicing signals professional operations.
Follow up on a schedule. Adjuster contact at day fourteen post-submission if not approved, day twenty-one with escalation request, day thirty with escalation to the carrier’s claims service line. Adjusters have hundreds of files. The files that get attention are the ones the contractor stays present on. The files that drift are the ones where the contractor submits and waits silently.
Reconcile cash to invoices weekly, not monthly. The accounting team should know which invoices are open, by carrier and by adjuster, every week. Stale aging that is not reviewed is aging that gets older. Weekly review with explicit follow-up assignments produces faster collections than monthly review.
Use a billing service when in-house capacity does not exist. Restoration-industry-specific billing services — companies like Restoration Insurance Billing, Blackwater Billing Services, NetClaimsNow, and others — exist specifically to handle Xactimate invoice assembly, submission, and follow-up. For shops that do not have in-house Xactimate competence or in-house collections discipline, outsourcing this function to a specialist often produces a faster cycle than handling it in-house at the shop’s current capability level. The fee is paid out of the cash-cycle compression.
Submitting an invoice that triggers an adjuster RFI costs 5 to 14 days per revision loop. Arm your lead techs and billing coordinators with print-ready first-time-clean submission QA sheets, line-item scope audits, and AI-driven aging diagnostics.
Compressing the AR cycle reduces but does not eliminate working capital intensity. Even at a defensible 45-60 day cycle, a growing restoration company carries substantial cash in receivables. The well-run shop has a deliberate working capital strategy that funds this intensity without surprises.
Cash reserve sized to the actual aging profile. A shop with a 60-day cycle should carry cash reserves sufficient to operate for at least 60 days at current burn rate, plus a buffer for delayed collections on specific files. Many operators size reserves to 30 days of operating cost, which is too thin for restoration’s cycle. Sizing reserves to 75-90 days of operating cost, with a clear policy on when reserves can be drawn down for growth investment versus when they must be held, gives the shop room to absorb a slow collection month without payroll stress.
Line of credit as a flex tool, not a permanent funding source. Most growing restoration shops should have a working-capital line of credit with a commercial bank, sized to cover one to two months of operating cost. The line is a tool for absorbing month-to-month variation in collections, not a tool for funding ongoing operations. Shops that operate continuously on the line of credit are shops with a structural cash problem they have papered over with debt.
Customer financing as a deliberate tool. On residential reconstruction work where insurance does not cover the full scope, customer financing can be offered through restoration-industry-specific finance partners or general home-improvement finance platforms. This converts a payment-cycle question into a marketing question and shifts the cycle off the shop’s balance sheet.
Avoid AOB-driven cash flow models. Some restoration companies build their cash flow on aggressive use of assignments of benefits, where the carrier pays the contractor directly. AOBs solve the homeowner-endorsement step but do not address the underlying claim cycle, and several states have passed AOB reform that complicates or restricts the practice. Building working capital strategy around AOBs is fragile both legally and operationally.
Factoring as last resort, not first option. Specialty receivables-factoring firms exist that will advance against restoration AR, but the cost is meaningful (often 2-4 percent per month effective rate) and using factoring routinely indicates that the underlying cycle problem has not been fixed. Use factoring only as a bridge while implementing the operational improvements that compress the cycle, not as a permanent solution.
What the AR cycle reveals about the rest of the business
The AR cycle is a diagnostic tool as much as it is an operational metric. Specific patterns in the AR aging report point to specific underlying issues elsewhere in the operation.
Long cycle on a specific carrier. The carrier’s program structure may not fit the shop’s working-capital tolerance, or the shop’s documentation may not fit the carrier’s submission requirements. Either way, this is a focused intervention point.
Long cycle on a specific service line. The Xactimate competence in that service line may be weaker, or the documentation discipline may be looser. Investigate the lead tech and project manager on that service line and compare practice to the better-performing service lines.
Long cycle on a specific job size. Process gaps in the size band — possibly insufficient project-management attention on mid-size jobs or insufficient documentation rigor on small jobs that get treated casually. Address process at the size band rather than the job level.
Long cycle on jobs led by a specific project manager. The PM’s documentation, communication, or follow-up practice may be substandard. Coachable, often quickly.
Spike in cycle in a specific month. Look for upstream issues — was a billing person out, did a software change disrupt invoice generation, did a regulatory change affect a common scope item, did a carrier change its program. The cycle is the downstream symptom of upstream operations.
The shop that uses AR aging as a diagnostic produces continuous improvement. The shop that uses AR aging only as a financial-statement input misses most of the management information the metric carries.
How this article fits the cluster
The AR cycle is the foundation. The next article in the cluster — gross margin by service line — depends on the AR cycle being defensible, because service-line economics that look good on margin but fail on cash conversion are not actually good economics. The articles that follow on equipment economics, crew structure, KPI dashboards, and the rest all assume the operator has working capital under control. An operator who works through the rest of the cluster without first fixing the AR cycle is building on sand.
If you take only one operational improvement from this entire cluster, take this one. The investment is modest — documentation discipline, Xactimate competence, scheduled follow-up, weekly cash review. The return is direct, measurable, and recurring. Compressing days-to-cash from 90 to 60 frees roughly two months of revenue in working capital. For a $5 million shop, that is roughly $830,000 in cash. For a $20 million shop, it is roughly $3.3 million. Those are not theoretical numbers. They are sitting in your AR right now.
Choose Your Restoration Cash-Cycle Compression Tier
Select the operational depth that matches your annual revenue, billing capability, and carrier mix:
Field ReferenceFREE
Quick Card
2-page field card: the complete Xactimate-to-cash timeline map, 3-way slicing matrix, and operator-controllable vs external delay levers on one printable sheet.
What is a realistic DSO target for a restoration company?
For mitigation-heavy work with disciplined operations, 45-60 days is achievable. For mixed mitigation and reconstruction work, 60-75 days is realistic. For reconstruction-heavy work, 75-90 days is realistic. Operators running 90+ days have specific operational issues that should be diagnosable from the by-carrier, by-service-line, by-job-size view. Targeting under 30 days is unrealistic in this industry; targeting under 45 is achievable on the mitigation side but not the reconstruction side.
Should I use a restoration-specific billing service or build in-house?
Depends on shop size and current capability. Shops under $3 million with no in-house Xactimate-certified estimator typically benefit from a billing service — the cost is roughly offset by the cycle compression. Shops over $5 million should generally have in-house capability because the service fees become a real expense at scale and because in-house ownership of the cycle produces better discipline. Shops in between can go either way; the deciding factor is whether in-house capacity is genuinely competent or whether it is the owner-operator’s spouse doing it on weekends.
How do I get my AR aging by carrier, service line, and job size if my accounting system doesn’t slice it that way?
This is a one-time configuration project. Most accounting systems used by restoration companies (QuickBooks Online, QuickBooks Enterprise, Sage Intacct, NetSuite, restoration-specific platforms like Albi, KnowHow, and others) support custom fields or class tracking that can produce this slicing. The configuration takes a few days of accountant time and pays back permanently. If your current system genuinely cannot support this, the system is the bottleneck.
What about retainage on commercial work?
Commercial reconstruction often involves retainage (commonly 5-10 percent held until project completion) which extends the cycle on the retained portion well beyond the standard cycle. Build retainage into the AR aging view as a separate category so the operating cycle on the non-retained portion is visible cleanly. Retainage release is its own follow-up activity that should be treated as a managed process, not as something that happens automatically.
What if a specific carrier program is producing a long cycle but represents a meaningful portion of revenue?
This is a strategic decision, not just an operational one. The cycle math is real — if a carrier program produces revenue at acceptable margin but stretches AR by an extra 30 days, that’s a working-capital cost that the program revenue should justify. Quantify the cost (roughly the additional AR carried at the cost of capital), compare to the program’s contribution to gross profit, and decide whether the program is net positive on cash-adjusted economics. Many operators discover that programs they thought were valuable are actually drag once the cycle cost is accounted for.
How do I handle homeowners who do not endorse the joint check from the mortgage company?
This is a customer-service issue layered on a cash-cycle issue. Communicate the joint-check process to the homeowner before the loss is even mitigated, get them comfortable with the workflow, and follow up actively when the check is issued. Most customers cooperate; the few who do not usually have a deeper issue (dispute over scope, dispute over quality, financial distress) that needs to be addressed directly. Avoid letting these accounts age silently.
Is a line of credit absolutely necessary, or can a shop run without one?
Smaller shops under $1-2 million can sometimes run without one if reserves are healthy and growth is moderate. Shops over $3 million typically benefit from having one even if it sits unused most months — the optionality is worth the modest commitment fee. The decision is risk tolerance: a line of credit is insurance against a slow collection month, and like all insurance, it is most valuable when not needed.
How do I know if my Xactimate practice is the bottleneck?
Pull your most recent ten mitigation invoices and ten reconstruction invoices. For each, document the date submitted, the date approved, and any back-and-forth requests from the adjuster. If more than 30 percent of submissions trigger requests for revisions, your Xactimate practice has gaps. The specific gaps will be visible in the revision requests — line items used incorrectly, pricing outside standard with insufficient justification, scope items unsupported by documentation. Address those gaps directly, and the cycle compresses.
Can compressing the AR cycle actually replace the need for outside capital on a growing shop?
For most shops in the $1-30 million range, yes. The math works because each dollar of cycle compression frees a proportional dollar of working capital, and that capital recurs every cycle. Compressing cycle from 90 to 60 days on a $10 million shop frees roughly $830,000 in cash; on a $20 million shop, roughly $1.7 million. Those numbers fund meaningful growth without any external capital. Operators with cleaner AR cycles typically do not borrow for working capital because they do not need to.
What is the single most important practice I can install this week?
Daily documentation by the lead tech on every job, completed before the tech leaves site. Photos of pre-mitigation and post-mitigation conditions, moisture readings logged with timestamps, daily report covering work performed and conditions encountered, signed work authorization on file from day one. This single practice will compress your invoice submission time and reduce documentation-driven adjuster delays by more than any other change. Everything else in this article matters; this is where to start.
Updated Oct 31, 2026 — added the free Xactimate-to-cash quick card, cash-cycle fix pack, and AR cash-cycle bot book downloads to this guide.
The Signal — Tygart Media's weekly brief. What we actually ran, what it measured, and what it means for a restoration shop.