Tag: Industry Commentary

  • The Best Pharmacy Product Reads the Receipt Against the File

    The Best Pharmacy Product Reads the Receipt Against the File

    The pharmacy already has a public acquisition file.

    The counter still charges a number that may not sit next to it.

    That gap is the product.

    The idea mills keep minting a pharmacy chatbot, a coupon-clipper app, and an rxcheck.ai.

    Three names.

    One object.

    A register receipt, or the sticker on the bag, that does not sit next to the acquisition file the Centers for Medicare and Medicaid Services already publishes every week, or next to the maximum fair price file that took effect on January 1, 2026.

    Greg Isenberg’s stream and the daily micro-SaaS accounts keep splitting the same reader.

    One post wants a refund radar that studies why people ask for money back.

    Another wants a bill auditor that gets paid only when the client saves.

    A third wants a photo of a medical bill dropped into a chat, with a letter on the other side.

    Cute.

    Wrong cut if you stop at the chat.

    The customer does not wake up wanting a PBM explainer.

    They wake up because the bag was $47 and the same capsule was $9 at the pharmacy across the street, or because a Part D claim in 2026 still does not look like the price CMS already posted.

    Why this year, not a white paper

    Two public files moved from “someone could look it up” to “a stranger can photograph a receipt this week.”

    The first is NADAC, the National Average Drug Acquisition Cost.

    CMS posts it weekly on data.medicaid.gov.

    It is a survey of what retail pharmacies pay wholesalers for a drug, net of prompt-pay discounts, not the price on the register.

    A markup over that file is not automatically a rip-off.

    A pharmacy has rent, a pharmacist, and a dispensing fee.

    The product is the join, not the sermon.

    The Federal Trade Commission made the scale of the join hard to ignore.

    On January 14, 2025 the Commission published its second interim staff report on prescription-drug middlemen.

    Staff found that the Big Three — Caremark, Express Scripts, and OptumRx — marked up numerous specialty generic drugs dispensed at affiliated pharmacies by hundreds and thousands of percent.

    Those affiliated pharmacies generated more than $7.3 billion in dispensing revenue in excess of estimated acquisition cost, measured by NADAC, from 2017 to 2022.

    That excess revenue grew at a compound annual rate of 42 percent from 2017 to 2021.

    The top 10 specialty generics accounted for $6.2 billion of it, 85 percent of the total in the study window.

    The second file is newer, and it is the reason the wedge is this quarter rather than a 2027 roadmap.

    CMS published negotiated prices — the statute calls them maximum fair prices — for the first 10 Part D drugs on August 15, 2024.

    Those prices took effect January 1, 2026.

    The same fact sheet said that if the agreed prices had been in effect in 2023, net covered prescription-drug spending on those drugs would have been about $6 billion lower, 22 percent.

    About 9 million people with Medicare use at least one of the 10.

    Under the projected defined standard benefit, CMS estimated $1.5 billion in out-of-pocket savings for people with Part D in 2026.

    A participating manufacturer has to make the negotiated price available to eligible people and to the pharmacies that dispense the drug.

    The file is public.

    The receipt is in the bag.

    Almost nobody puts them on the same page before the card is charged.

    Two primitives, one wedge

    Primitive one is photo-and-PDF review.

    The mills have been shipping receipt readers for months.

    The input here is the thing already in the bag.

    Register receipt.

    Bag label.

    Part D explanation of benefits, if one exists.

    NDC if it printed.

    Drug name and strength if it did not.

    Quantity.

    Amount paid.

    Date.

    Pharmacy name.

    Cash, coupon, or plan.

    Primitive two is the public file join.

    NADAC for the NDC in the week of the fill.

    If the drug is one of the first ten and the payer is Part D, the maximum fair price for that NDC and supply.

    The output is three words, not a coach.

    Match.

    Mismatch.

    File too thin.

    File too thin is a real answer.

    NADAC does not cover every branded specialty the way a coupon site pretends to.

    A maximum fair price is not a cash price for a person who is not in Part D.

    Saying so is the product working.

    The wedge is a free checker.

    Not a platform.

    No account for the first answer.

    Photograph the receipt.

    Thirty seconds later: above the weekly acquisition file by this much, above the 2026 price file, or not enough on the page to say.

    If you cannot get a stranger to photograph one receipt this week, you do not have a company.

    You have a policy thread.

    What the checker is not allowed to do

    It does not tell anyone to stop a drug, split a tablet, or switch pharmacies on a clinical claim.

    It does not file an appeal.

    It does not move money.

    A mismatch on a specialty generic can be a plan design, a spread, a coupon that already fired, or a bad read of the NDC.

    The model drafts the comparison.

    A person owns the send.

    Anything that leaves the building — a note to the pharmacy, a Part D inquiry, a complaint to a state board — needs a human signer who has seen the receipt, the file row, and the sentence that will be sent.

    Contingency is fine after that signature, and only after a confirmed mismatch.

    Charge them when the file proves the gap, or do not charge them.

    Do not sell a subscription to a dashboard of adherence.

    The map is the company

    The first hundred receipts are a demo.

    The ten thousandth is a labeled map of counter price versus acquisition cost, and versus the 2026 price file, by NDC, chain, and ZIP.

    That map is the moat.

    Coupon sites already show a cash offer.

    They do not keep the pair: what this person was charged, what the weekly file said that week, and whether the Part D claim sat on the posted maximum fair price.

    A plan sponsor, a state Medicaid shop, or a local reporter will pay for the pair once it is boring and repeatable.

    They will not pay for another chatbot that explains formularies.

    Start narrow.

    Week one and two: one checker.

    Photo or PDF in.

    Cash generics with a stable NADAC row.

    One state.

    No account.

    Week three and four: the ten Part D drugs, and only the comparison to the posted price.

    A draft inquiry pack with the file row cited, held until a person signs.

    Do not start with oncology markups and a letter to a PBM.

    That is how the first customer becomes an exhibit.

    Why this cut, not the last one

    The leakage essay was tariffs, seats, and subscriptions.

    The rebate essay was a nameplate.

    The recall essay was a label.

    The short-pay essay was a contractor packet.

    The bill essay was an EOB against a hospital file.

    The tax essay was a notice against the roll.

    The utility essay was a statement against a filed tariff.

    The housing essay was a unit against a score.

    The delay essay was an itinerary against a cause code.

    The HOA essay was an assessment against a study.

    The 401(k) essay was a fee against a filing.

    This one is the bag version of the same pair: a document the customer already holds, plus a file the agency was required to publish, joined while the first negotiated prices are still new and the specialty-generic markup is already on a public record.

    The hospital file was a chargemaster.

    This file is an acquisition cost and a negotiated price.

    Different object.

    Same habit.

    Someone will own the labeled map of charged versus filed.

    The mills will keep proposing a new .ai name for each receipt.

    Ignore the names.

    Join the line.

    Keep the map.

    Will Tygart — Tygart Media.

    This is the idea-mill series.
  • Don’t Build the Deck. Own the Dashboard.

    Don’t Build the Deck. Own the Dashboard.

    The news hook: on September 10, OpenAI put its Agents API into public beta — the Codex harness as a service. One API call spins up a production agent, OpenAI running the loop. That’s what got me thinking about 1990s car stereos.

    In the 90s, you didn’t just buy a Kenwood deck and drop it in. CD players were thicker than the cassette decks they replaced, so you needed a dash kit, a wiring harness, and somebody who knew how to make it all fit your specific car without setting the electrical system on fire. The deck was the exciting part. The harness was the part that determined whether it worked.

    AI is having its car-stereo decade right now, and the stack rhymes perfectly:

    • The decks are the models. They all play the discs now. Commoditized.
    • The harnesses are the agent frameworks — the loop that manages context, tools, subagents, sandpapers the rough edges between model releases. This is where the fight moved. OpenAI just productized theirs.
    • The connector kits are the universal adapters. In the 90s, one company owned this layer: Metra Electronics. Their entire brand was “the Installer’s Choice” — because we are installers — and they won by abstracting every car’s weird factory wiring so any shop could install any deck. Seventy years of winning by serving the installer, not the driver.
    • The installers are who actually gets paid. The shop on the corner with the soldering iron.

    Platforms are won by installer armies

    This is the oldest play in enterprise tech. Microsoft didn’t win on Windows alone — it won on the MCSE army, thousands of certified installers who made Windows the safe recommendation. Cisco did the same with its certification ladder. The vendor that recruits the most installers wins, because the installer chooses the harness for the customer, and the customer just wants music.

    Watch what’s happening now through that lens and everything snaps into focus. The Grokbot events. The ambassador programs. Everybody is recruiting installers — grassroots adoption, a visible market, and a career pivot for the people who learn the wiring first. The vendors aren’t selling to end users. They’re selling to the shops.

    The wiring diagram decides before the features do

    Here’s the detail that matters more than any launch demo. The managed harnesses come with constraints: where your data lives, who retains it, what residency you get. One prominent new offering is US-only with no zero-data-retention option — which rules it out for client-data workflows before you ever evaluate the features.

    Same lesson as the 90s: the harness that doesn’t fit your car is worthless no matter how good the deck is. The wiring diagram — data residency, retention, tenant boundaries — decides the purchase before the spec sheet does. Contractors figured this out fast: they won’t upload their estimates to a startup they found on social media, but they’ll run the same analysis inside their own Microsoft tenant. The tenant boundary might be the whole moat.

    The operator’s math

    So here’s the build-vs-buy for the AI age, and it’s the same math as the estimate-auditing tools: the intelligence is commoditized, so you’re never paying for smarts. You’re paying for the pipe and the paperwork — or in this case, the harness and the install.

    If a managed harness fits your wiring diagram and costs less than the engineering hours to maintain your own loop, buy it. If your data can’t leave your tenant, or the harness’s constraints disqualify it, build the loop yourself — the models are all CD players, and a good installer can wire any of them into the dash.

    Either way, notice where the money actually pools. Not with the deck makers. Not even with the harness makers. With the installers — the people who show up, learn the specific car, and make the music play.

    That’s the game. Don’t build the deck. Own the dashboard.

    The public tools behind that storefront are listed on Open Source Installer Tools.

  • The Arms Column, Field-Tested

    The Arms Column, Field-Tested

    “We said you’re not buying minutes — you’re buying arms. Then the calls started flowing. Here’s what the bill actually taught us.”

    A while back I argued that voice-AI pricing is a lie: the per-minute number on the pricing page isn’t the product. The product is a stack of arms — the voice intelligence, the carrier connection, the infrastructure around them — and the per-minute price is just the costume they wear.

    That was the theory. This is the field test.

    What the bill actually says

    Run a real week of calls and read the invoice the way an owner reads it — not the headline rate, the total. The per-minute number is almost never the biggest line. The arms are.

    The voice model doing the talking. The carrier moving the audio. The platform orchestrating the whole thing — the number, the recording, the transcript, the handoff. Each arm bills its own way, on its own meter, and the “per minute” quote only ever described one of them.

    Nobody lied to you. They just priced the costume and shipped the wardrobe.

    A bundled cable fanning out into many separate colored wires

    The concurrency math nobody shows you

    Here’s what the field test really exposes: minutes are linear, arms are not.

    Ten simultaneous calls isn’t ten times the per-minute rate in value — it’s ten arms, all live at once. The pricing page shows you a single call’s minute. Your Monday morning shows you ten calls overlapping, each holding its own model session, its own carrier leg, its own recording pipeline open.

    The vendor priced the minute. You bought the rush hour. Those are different products, and only one of them shows up when the phones light up.

    You pay for arms even when the call goes nowhere

    The wrong number. The three-second hangup. The caller who wanted the pizza place. The silence where someone pocket-dialed you.

    Minutes barely moved. The arms all fired anyway — the model spun up, the carrier connected, the platform recorded forty seconds of nothing and transcribed it faithfully. You paid for the whole stack to handle a call that never existed.

    This is the line the per-minute lie can’t survive: the bill doesn’t care whether the call mattered. The arms do the work either way. Price the arms, or the junk calls price you.

    The only math that matters

    Stop dividing by minutes. Start dividing by outcomes.

    Take a real week: total voice bill, all arms included, divided by minutes — that’s the advertised number, and it’s trivia. Now divide the same total by resolved calls. Then by booked jobs. That last number is the only one that touches revenue, and no vendor puts it on the pricing page because no vendor controls it — you do, with your harness.

    A vendor quoting two cents a minute against a vendor quoting five is a meaningless comparison until you know whose stack resolves the call. The cheap minute that books nothing is the most expensive minute you’ve ever bought.

    A headset resting on a desk next to a glowing phone with blurred charts behind

    What to ask a vendor now

    After the field test, there are three questions, and a vendor’s answers tell you everything:

    Break the bill into arms. What’s the model cost, the carrier cost, the platform cost — separately? If they can’t or won’t, you’re buying a bundle, and bundles hide margin.

    What does my rush hour cost? Not a minute — my Monday at 8 AM, ten calls deep. If the answer is “the same per-minute rate,” they haven’t thought about it, which means you will.

    What do I pay for the call that goes nowhere? The hangup, the wrong number, the silence. If everything bills the same whether the call mattered or not, the arms are priced — the minute is just the label.

    The close

    Minutes were never the product. The product is an answered call that ends in a booked job — and that’s built from arms, priced in arms, and won or lost in the harness around them.

    The pricing page will keep selling minutes. Let it. You know what you’re buying now.

    Buy the arms. Price the outcomes. Own the harness that turns one into the other.

  • The Switchboard, Not the Traveler

    The Switchboard, Not the Traveler

    “I’m the switchboard, not the traveler.”

    It’s the sentence that explains the whole business model. Most people never get a sentence like that. I got one, and everything since has been commentary on it.

    The traveler

    The traveler goes somewhere, does the thing, collects the fee. It’s the default model of work: your value is your presence, your labor, your miles. It’s honest and it’s linear. When the trip ends, the value ends — until the next trip.

    Most businesses are travelers. They sell hours, jobs, deliverables. They go, they do, they invoice. Nothing wrong with it. But the ceiling is always the calendar: there are only so many trips in a year.

    The switchboard

    The switchboard doesn’t travel. It sits at the center and completes circuits.

    Person A needs person B. They don’t know each other, or they know each other but the timing’s never been right, or they need a reason to trust the connection. You make the introduction. The circuit lights up. Value flows — a deal, a job, a partnership — and you were the reason it flowed.

    Then you do it again. And again. Every completed circuit makes you more central, because both sides remember who lit it up. The next time A needs someone, they call you first. The next time B has an opening, you hear about it before anyone else.

    Wealth denominated in access

    Money is one currency. Access is another — and it compounds faster.

    A fee gets spent. Access gets reinvested automatically: every circuit you complete buys you the next one. The seat at the table, the early phone call, the “hey, before I talk to anyone else” — that’s wealth, denominated in something no bank tracks and no competitor can undercut.

    Travelers collect miles. Switchboards collect circuits. When the map gets big enough, the switchboard is the most valuable thing on it — because every traveler eventually needs a connection they can’t make themselves.

    A circuit board with a glowing golden trace completing a connection

    Why it works in this trade

    Restoration runs on trust and timing. The right adjuster, the right contractor, the right facility manager, at the right moment — that’s the whole game. Nobody can hold all of it. The territory is too big, the relationships too many, the timing too tight.

    So somebody has to be the one who knows who to call. Not the one who does every job — the one who knows who should. The trade doesn’t need another traveler. It needs the switchboard.

    The discipline

    A switchboard has three obligations, and they’re non-negotiable:

    Be neutral. You don’t take sides in the circuit — you complete it. The moment an introduction serves you more than the two people you’re connecting, the switchboard starts corroding. People can feel a self-serving connector within minutes.

    Be reliable. Answer. Remember. Follow through. The switchboard that drops circuits gets routed around, and routing around is permanent.

    Be fast. A connection delayed is a connection denied. Timing is half the value — the right introduction at the wrong time is just a nice conversation.

    And one more, the quiet one: never make the introduction about you. The light belongs on the circuit, not the switchboard. Your name comes up because the connection worked, not because you announced it.

    A hand plugging a brass patch cord into a switchboard jack

    The close

    I didn’t set out to be the switchboard. I set out to be useful — and usefulness, compounded over enough years and enough people, turns into a position at the center of the map.

    The travelers will always have the miles. I’ll keep the circuits.

    If you’re building something, ask yourself which one you are. There’s no wrong answer — but there’s a wrong assumption, which is thinking you’re the traveler when you’re actually the switchboard, or vice versa. Know which one you are. Then be it on purpose.

  • 90% of SEO Agencies Will Be Irrelevant by 2026 — Good. The 10% Won’t Sell Pages.

    90% of SEO Agencies Will Be Irrelevant by 2026 — Good. The 10% Won’t Sell Pages.

    A vendor just published the obituary for my industry. “90% of SEO agencies will be irrelevant by 2026.” It’s a sales pitch dressed as a prophecy — they’re selling their own “hyper-intelligent SEO,” so of course the old model has to die first.

    Here’s the uncomfortable part: they’re half right.

    The steelman

    Their argument, at full strength: AI has already absorbed keyword research, content outlines, and technical audits. The page-minting labor — the thing agencies billed hours for — is now a commodity any contractor can run from their own AI stack. And niching down doesn’t save you, because AI flattens execution across every niche equally. A restoration-only agency mints pages the same way a dental-only agency does: same models, same prompts, same output.

    Then the sharpest line, aimed straight at a $995/month retainer like ours: monthly payments masked declining perceived value while clients stayed only because switching felt risky. Inertia as a business model. And inertia collapses the moment the contractor’s own AI handles the page work in-house.

    Read that twice. It’s the most dangerous true thing anyone’s said about my business this year.

    Industrial printing press rolling out endless identical glowing sheets

    Where they’re wrong

    Execution was never the product. It was the packaging.

    Nobody ever paid an agency for pages. They paid for the judgment about which pages, in which order, aimed at which questions — and for someone to notice when the game changed and change with it. The page was the receipt, not the purchase.

    What actually died is the retainer that sold counts: X city pages, Y blog posts, Z “optimizations” per month. Count-based selling trained clients to audit deliverables instead of outcomes, and it trained agencies to manufacture deliverables instead of outcomes. AI didn’t kill that model. It just made the manufacturing free — which exposed that the model was already hollow.

    What survives is the part AI can’t commoditize: being present inside the answer. When a homeowner asks their AI assistant who to call for a flooded kitchen, somebody’s name comes out of its mouth. That presence isn’t won by page counts. It’s won by being the source the answer engines trust and cite — clear answers, real proof, a consistent identity across the web. That’s judgment work. It has a human gate. It doesn’t scale into a commodity, because trust doesn’t scale into a commodity.

    The re-anchor

    So we’re re-anchoring the sprint to the only number that matters: cited pages. Not pages published — pages the answer engines actually cite, tracked by identity over time. Five cited today plus five different tomorrow is churn, not growth. The metric is persistence: which of our pages keep showing up inside answers, month after month.

    One page glowing gold in a spotlight among hundreds of dim floating pages in a dark library

    The $995 doesn’t buy GBP tweaks and city-page counts anymore. It buys a standing position inside the answers your customers are already asking for — and the judgment to keep it there as the engines change the rules. That’s a strategy partner, not a page vendor.

    What changes Monday

    If you run an agency, or you buy from one, here’s the Monday-morning version:

    1. Kill count-based reporting. If your monthly report leads with pages published, posts written, or “optimizations completed,” you’re reporting manufacturing output. Nobody buys that anymore — they can manufacture it themselves.
    2. Report cited presence instead. Which questions do your clients show up inside? Which pages got cited, by which engines, and are the same pages still cited next month? That’s the report worth paying for.
    3. Price the judgment, not the labor. The labor is free now. What’s scarce is knowing which questions are worth winning, what proof earns a citation, and when to change course. Put that on the invoice or someone else will.

    The 10%

    The vendor’s prophecy ends with 90% irrelevant. Fine. Let them have the 90% — they were selling page counts, and page counts are free now.

    The 10% that survive won’t be the ones with the best AI stack. Every agency will have the same models. They’ll be the ones who stopped selling execution before the market forced them to — and started selling the one thing the models can’t mint: being the answer.

  • Who Pays Before the Work: The Deposit Fight Every Restoration Job Faces

    Who Pays Before the Work: The Deposit Fight Every Restoration Job Faces

    It started in a Facebook group in Anderson, Indiana: homeowners trading notes on 25–50% deposits, contractors answering that $12–15K in rental gear has to sit on site before the drying starts. The same fight is happening in public, all over the internet, and it’s worth reading in the combatants’ own words.

    Illustration of a homeowner and contractor in a tug-of-war over a repair contract
    The deposit debate, illustrated: both sides are protecting themselves from the same thing — getting burned.

    Camp one: the contractors

    Entrepreneur Nick Ayala’s reel (13K likes, 250 comments) takes on the client who says “I’ll pay you when it’s done.” His argument: starting work without a deposit “makes the freelancer the client’s bank — fronting labor, materials, calendar time, and 100% of the risk for free.”

    “Makes the freelancer the client’s bank — fronting labor, materials, calendar time, and 100% of the risk for free.”
    — Nick Ayala, Instagram

    A contractor posting as ProWall Paints & Plaster admits he “used to think asking for 50% upfront was ‘crazy,’ but now understands it is necessary” — the deposit covers materials, labor, scheduling, and mobilization. And John at Bluestone Construction puts it the way only a contractor can: “You pay 100% for any item at Canadian Tire… Yet in home renos where he locks the door and has complete control, he thinks he doesn’t have to pay!!”

    Camp two: the homeowners

    The rebuttal is just as vivid. One homeowner’s Instagram rant is captioned “A fool, and his money will soon be parted” — he will not pay half before work starts, period. A Facebook post that drew 500 comments is just a screenshot of a text exchange titled “No Deposit = No Work”: the contractor demands 50% by Zelle, the customer replies “Oh no I don’t pay no until the work is completed” and “That is unsafe.”

    “Oh no I don’t pay no until the work is completed.”
    — a customer, in a 500-comment Facebook thread

    And the fear isn’t abstract — a Moreno Valley community post with 810 comments documents a painter who took 50% cash upfront, missed days, asked for rent money, and quit.

    The law has opinions too

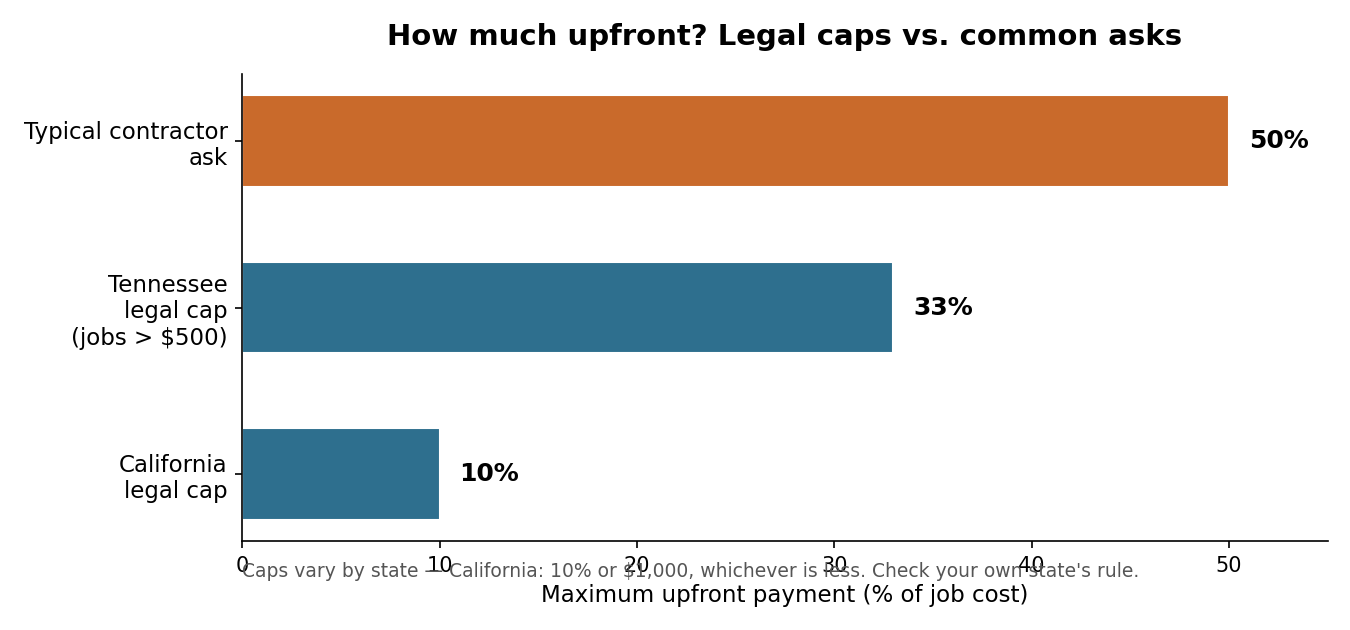
    Multiple states cap deposits by statute — California at 10% or $1,000, Tennessee at 33% for jobs over $500 — and UK prime minister Andy Burnham just weighed in on the same pattern (“take a big deposit, do half a job, then disappear”), backing escrow-style release: “Do the work, get paid. It’s as simple as that.”

    Bar chart comparing legal deposit caps in California (10%) and Tennessee (33%) against a typical contractor ask of 50%
    Legal caps vs. common asks. Caps vary by state — check your own state’s rule before you sign anything.

    Now the restoration spin

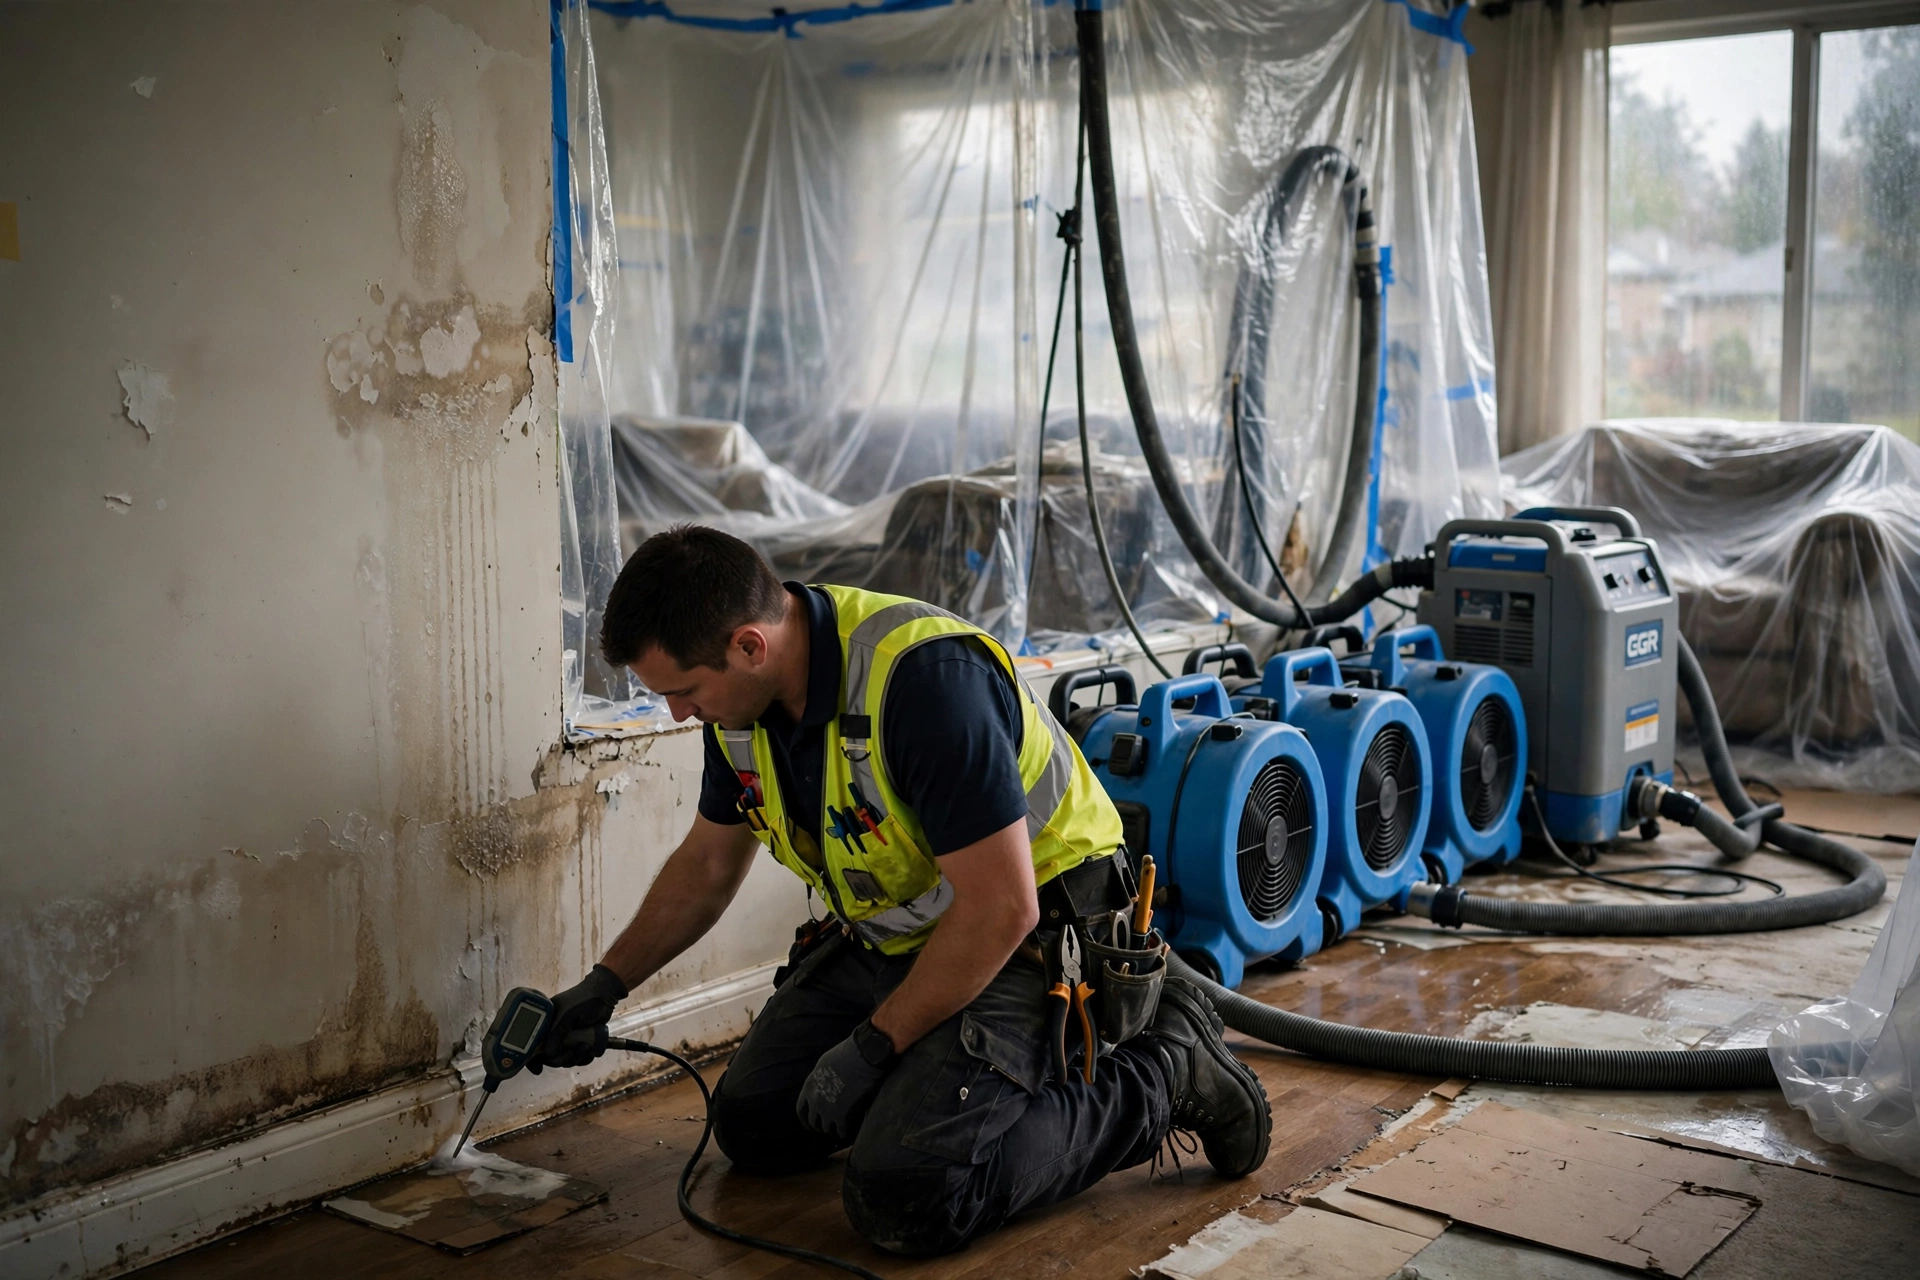
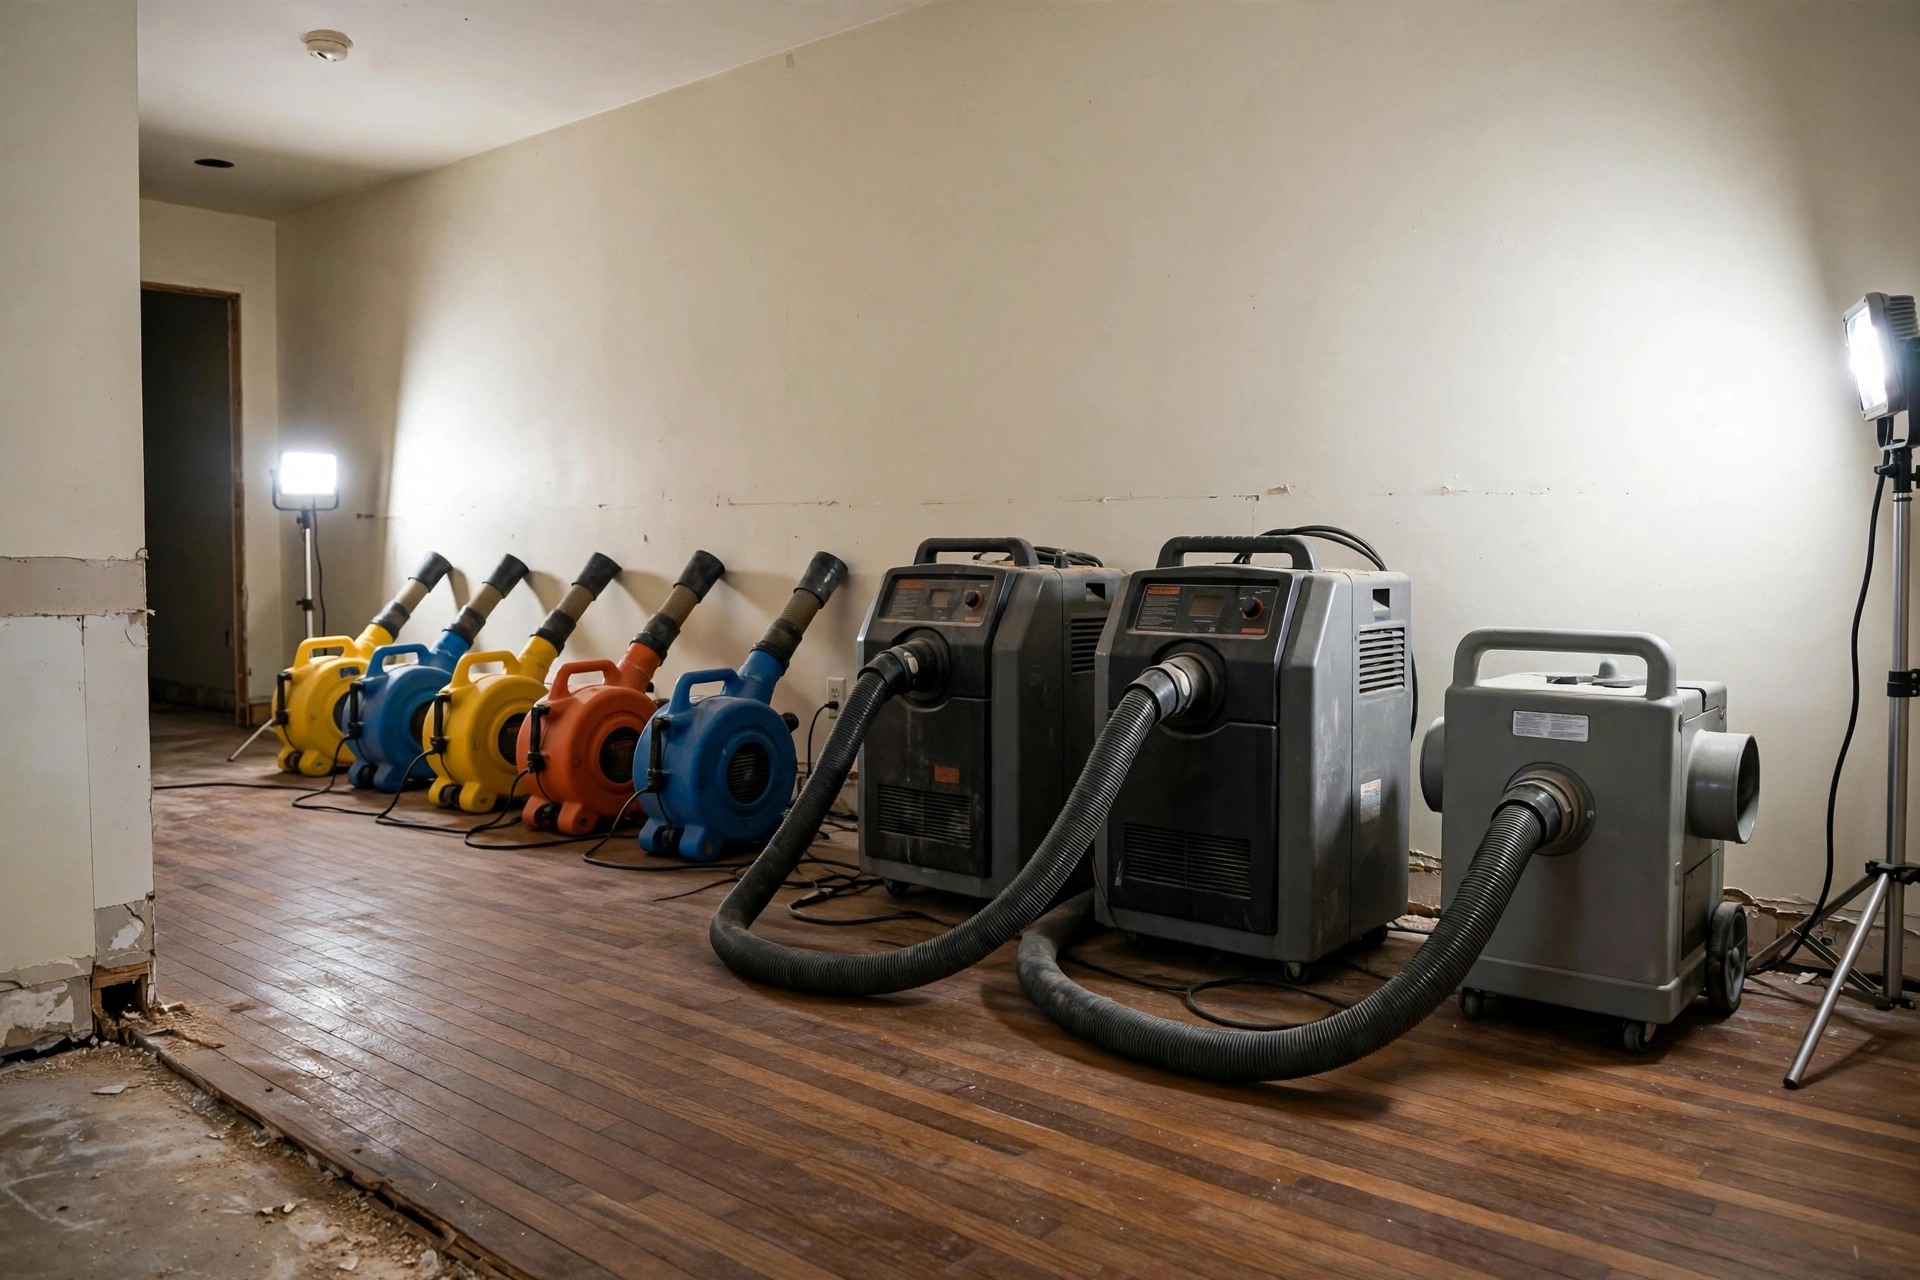
    This trade has a wrinkle the general debate misses. In restoration, the contractor’s number is real in a specific way: dehumidifiers, air movers, HEPA scrubbers, containment — the rental clock starts when the gear rolls off the truck, and a serious loss can mean twelve to fifteen grand of equipment sitting in your living room before the first board is cut. That’s mobilization cost, and a deposit against it is legitimate.

    Professional restoration drying equipment — air movers, dehumidifiers, and an air scrubber — lined up in a home
    Mobilization: this is what $12–15K of rental equipment looks like on day one — before the drying even starts.

    But here’s the part homeowners in that Anderson thread are really asking about: on an insured loss, the homeowner often isn’t the one paying — the carrier is. The deposit fight on a covered claim is about who fronts cash while the claim processes: the deductible, the first invoice, the gap between “work starts today” and “the check arrives in three weeks.” A good restoration contractor structures deposits around the claim, not against the homeowner.

    The middle ground

    Assembled from the sanest voices in these threads:

    • Tie the deposit to something real. A DIYnot commenter nailed it: “a reasonable deposit is the cost of the equipment to be installed plus the sundry materials.” In restoration, that means the deposit maps to mobilization — gear on site — not an arbitrary 50%.
    • Spell out the deposit rules in writing. Kevin Page on LinkedIn: “Spell out plainly whether the deposit is non-refundable, or exactly how it gets prorated if things end early.”
    • Pay by phase, not by percentage. A BiggerPockets investor: “You give some unscrupulous Contrs 1/3 up front and they’ll just take off.” His fix: invoice per phase, pay each phase in full when complete and inspected.
    • Remember who holds the leverage. “Whoever controls the money controls the job,” writes one builder — which is exactly why staged payments beat lump deposits. Money follows work.
    • Documentation is the tell. Daily moisture readings, psychrometric logs, photos at every stage. A contractor who documents is a contractor who finishes — and those are the same records your adjuster needs.

    The deposit isn’t the problem. The missing paperwork is. Both camps in this fight want the same thing — to not get burned — and the industry just hasn’t made the middle ground standard yet.

  • Cyber insurers are writing AI into policies — the fine print splits on whose AI it is

    Two specialist cyber carriers put affirmative AI wording on cyber cover within days of each other. CFC rebuilt the cyber section of its financial institutions insurance suite around its full cyber proactive response (CPR) policy, adding affirmative wording for AI-related cyber exposures, announced September 17. Beazley issued a comparable AI Clarifying Endorsement for its cyber product, stating explicitly that AI-driven cyber attacks fall within its existing cover.

    The announcements put a name on what the market has called silent AI — cyber policies absorbing AI-related risk for roughly two years without naming it, an echo of the silent-cyber problem that pushed cyber exposure into standalone products a decade ago. Note the contrast: in general liability, new ISO exclusion forms effective this January let carriers strip AI-related losses out of standard policies instead of affirming them.

    The split that matters: the affirmative wording confirms AI used against the policyholder — AI-driven deception, reconnaissance, intrusion — falls within cyber cover. It says nothing about AI the business itself runs — client-facing tools, trading models, vendor platforms. That exposure may sit under E&O, professional liability, or a gap between the two.

    For restoration contractors: this is the wording now being written into specialist cyber forms, not a rewrite of every contractor policy. If your operation runs AI on client work — intake bots, quoting tools, chatbots — that wording answers the attack-against-you question, not the your-AI-made-a-mistake question. That’s a broker conversation, and it’s new this month. The operator-side breakdown is on Restoration Intel.

    Sources: Insurance Business UK on CFC; Beazley’s AI Clarifying Endorsement

  • Cyber insurers are writing AI into policies — the fine print splits on whose AI it is

    Two specialist cyber carriers put affirmative AI wording on cyber cover within days of each other. CFC rebuilt the cyber section of its financial institutions insurance suite around its full cyber proactive response (CPR) policy, adding affirmative wording for AI-related cyber exposures, announced September 17. Beazley issued a comparable AI Clarifying Endorsement for its cyber product, stating explicitly that AI-driven cyber attacks fall within its existing cover.

    The announcements put a name on what the market has called silent AI — cyber policies absorbing AI-related risk for roughly two years without naming it, an echo of the silent-cyber problem that pushed cyber exposure into standalone products a decade ago. Note the contrast: in general liability, new ISO exclusion forms effective this January let carriers strip AI-related losses out of standard policies instead of affirming them.

    The split that matters: the affirmative wording confirms AI used against the policyholder — phishing, reconnaissance, intrusion — falls within cyber cover. It says nothing about AI the business itself runs — client-facing tools, trading models, vendor platforms. That exposure may sit under E&O, professional liability, or a gap between the two.

    For restoration contractors: this is the wording now being written into specialist cyber forms, not a rewrite of every contractor policy. If your operation runs AI on client work — intake bots, quoting tools, chatbots — that wording answers the attack-against-you question, not the your-AI-made-a-mistake question. That’s a broker conversation, and it’s new this month. The operator-side breakdown is on Restoration Intel.

    Sources: Insurance Business UK on CFC; Beazley’s AI Clarifying Endorsement

  • Azure Static Web Apps vs Firebase Hosting: A Dashboard on Each

    Azure Static Web Apps vs Firebase Hosting: A Dashboard on Each

    Azure Static Web Apps vs Firebase Hosting: A Dashboard on Each

    A static front-end — an internal dashboard, a docs site, a landing page — is the most thankless thing to host badly and the most satisfying thing to host well. You want a global CDN, free SSL, a custom domain, and CI/CD that redeploys when you push, all without standing up a server or paying a cent. Both Azure and Google have a purpose-built free product for exactly this, and they’re both genuinely excellent.

    We host the same internal dashboard on both Azure Static Web Apps and Firebase Hosting, on the free tiers, and compare. Short answer: this is a toss-up — both are excellent, pick by ecosystem. Azure Static Web Apps free tier gives you 100 GB of bandwidth, 2 custom domains, 0.5 GB per app, free managed SSL, and built-in CI/CD straight from GitHub. Firebase Hosting’s free Spark plan gives you 10 GB of storage, 360 MB/day of transfer, free SSL, and custom domains. The right answer is whichever cloud your other services already live in.

    This is the breakdown from the running lab on tygart.media — bandwidth and limits, CI/CD, auth and functions integration, custom domains, and the CDN.

    The free-tier ceilings

    Four pillars: headless agents, MCP tools, rules/memory, human review
    Free-tier ceilings for Static Web Apps vs Firebase.

    How we do it

    Azure Google Cloud Verdict
    Free bandwidth 100 GB total 360 MB/day (~10 GB/mo) transfer Azure on raw monthly headroom
    Free storage per app 0.5 GB 10 GB Firebase on storage
    Custom domains (free) 2 Multiple supported Firebase, slightly
    Free managed SSL Yes Yes Tie
    Built-in CI/CD Yes (GitHub Actions wired automatically) Yes (Firebase CLI / GitHub Action) Azure, slightly more turnkey

    The numbers favor different things. Azure leads on monthly bandwidth — 100 GB is a lot of dashboard traffic — while Firebase leads on storage, with 10 GB versus Azure’s 0.5 GB per app. For an internal dashboard, neither limit is close to binding: the assets are small and the audience is a handful of people. Firebase’s 360 MB/day transfer cap is the one to watch only if a dashboard goes unexpectedly viral, which an internal tool won’t.

    CI/CD, auth, and functions

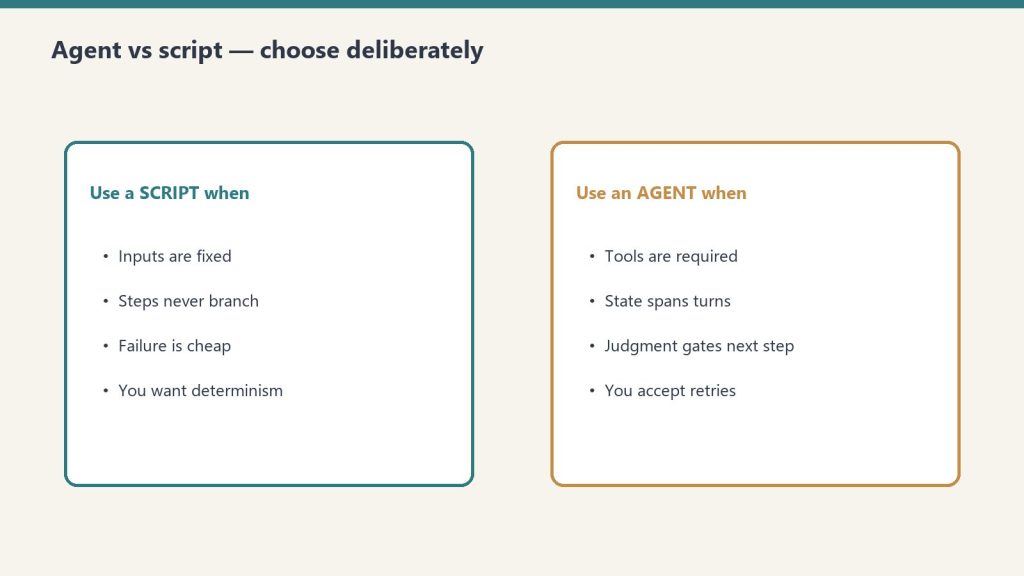
    Side-by-side when to use a script versus an agent
    CI/CD, auth, and functions on each host.

    This is where “static hosting” stops being just a CDN and starts being a platform.

    How we do it

    Azure Google Cloud Verdict
    Deploy on git push Auto-wired GitHub Actions Firebase CLI or GitHub Action Azure on zero-config setup
    Built-in auth Yes (Entra, GitHub, social — built in) Via Firebase Authentication Azure for bundled, Firebase for depth
    Serverless functions Built-in Azure Functions integration Cloud Functions / pairs naturally Tie — both have a backend path
    Staging environments Free preview environments per PR Preview channels Tie
    Setup friction Connect repo, done CLI init, done Azure, slightly

    Azure Static Web Apps’ standout is how much it bundles by default: connect a GitHub repo and it writes the Actions workflow for you, provisions preview environments per pull request, and offers built-in authentication (Entra, GitHub, and social providers) without you wiring an auth service. Firebase matches the capability but composes it from named products — Firebase Authentication and Cloud Functions — which is more à la carte and, if you’re already deep in Firebase, more powerful and familiar.

    Custom domains and the CDN

    How we do it

    Azure Google Cloud Verdict
    Custom domain setup 2 free, managed cert Add domain, managed cert Tie
    Global CDN Yes, included Yes, included (Fastly-backed) Tie
    Cache control Configurable Configurable Tie
    TTFB at our scale Fast Fast Tie

    Both put your dashboard behind a real global CDN with automatic SSL on a custom domain, and at our scale the time-to-first-byte was indistinguishable. This part is genuinely a wash — both clouds have solved static delivery.

    What surprised us

    Desk with laptop, checklist notebook, and billing card ready before creating an Anthropic API key
    What surprised us hosting the same dashboard.
    • Azure’s per-PR preview environments are a delight. Open a pull request and you get a live URL of that exact change, free, with no setup. For reviewing dashboard tweaks it’s better than we expected.
    • Firebase’s storage allowance is the bigger one. 10 GB versus 0.5 GB sounds dramatic, but for a static front-end neither limit matters — the assets are tiny.
    • Azure’s built-in auth saved real work. Adding GitHub login to an internal dashboard was nearly free of code on Azure; on Firebase it meant wiring Firebase Authentication, which is more capable but more steps.
    • The hosting itself is a non-event on both. Push, it’s live, it’s fast, it’s free. That’s the whole experience — exactly as it should be.

    The takeaway

    Pick Azure Static Web Apps if you want the most bundled experience — auto-wired GitHub CI/CD, free per-PR preview environments, and built-in authentication — and your stack already leans Microsoft. The 100 GB bandwidth is generous for any internal tool.

    Pick Firebase Hosting if you’re already in the Firebase/Google ecosystem and want its deeper, composable Authentication and Cloud Functions, or you value the larger 10 GB storage allowance. It pairs naturally with the rest of Firebase.

    Honestly, for a static dashboard you can’t go wrong. We run the dashboard on whichever cloud hosts the data and functions behind it — co-location beats cleverness. Both deliver the dashboard fast, on a custom domain, with free SSL, at $0.

    This is part of our “Two Clouds, One Site” series — we run the same media property on both Azure and Google Cloud on the free tiers, hosting the same dashboard on each to feel where the platforms differ. The lab lives on tygart.media; the findings publish here.

    Related on Tygart Media: $0 cloud stack · Functions vs Cloud Run · Cosmos DB vs Firestore.

    Frequently asked questions

    What do the free tiers of Azure Static Web Apps and Firebase Hosting include? Azure Static Web Apps’ free tier includes 100 GB of bandwidth, 2 custom domains, 0.5 GB of storage per app, free managed SSL, and built-in GitHub CI/CD. Firebase Hosting’s free Spark plan includes 10 GB of storage, 360 MB/day of transfer, free SSL, and custom domains. Azure leads on bandwidth; Firebase leads on storage.

    Which is better for hosting a static site or dashboard for free? Both are excellent and the choice comes down to ecosystem. Azure Static Web Apps bundles more by default — auto-wired CI/CD, per-PR preview environments, and built-in authentication. Firebase Hosting pairs naturally with Firebase Authentication and Cloud Functions and offers more free storage. Pick the one matching the rest of your stack.

    Does Azure Static Web Apps include built-in authentication? Yes. Azure Static Web Apps offers built-in authentication with Entra ID, GitHub, and social providers without wiring a separate auth service, which makes adding login to an internal dashboard nearly code-free. Firebase achieves the same through Firebase Authentication, which is more capable but takes more setup.

    Do both Azure Static Web Apps and Firebase Hosting give free SSL and custom domains? Yes. Both provide free managed SSL certificates and support custom domains on the free tier — Azure includes 2 custom domains, and Firebase supports adding custom domains with managed certificates. Both also put your site behind a global CDN at no cost.

    Will I hit the free hosting limits with an internal dashboard? Almost certainly not. An internal dashboard serves small assets to a few people, so neither Azure’s 100 GB bandwidth nor Firebase’s 360 MB/day transfer comes close to binding. Firebase’s daily transfer cap would only matter if a public site went unexpectedly viral.