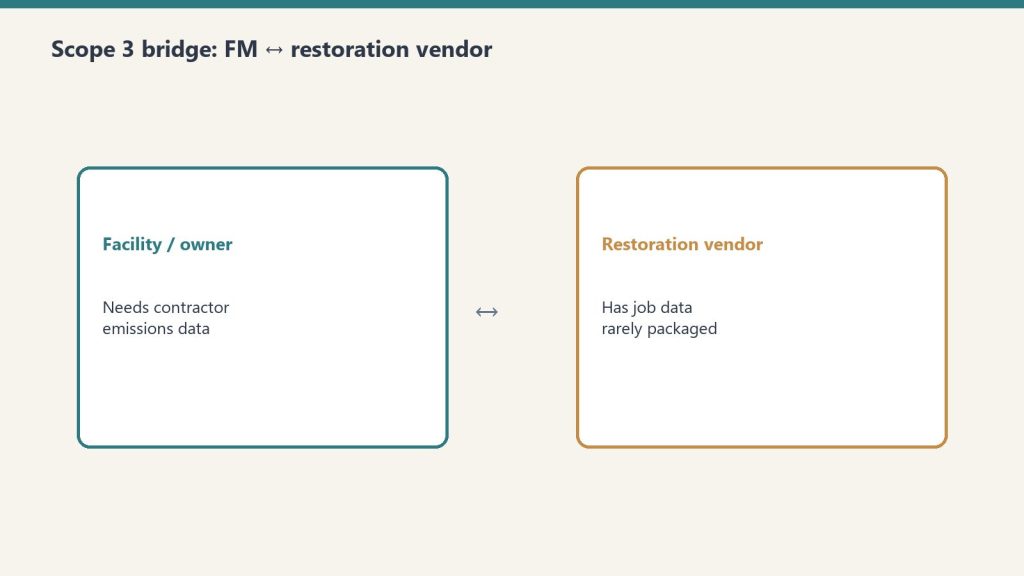
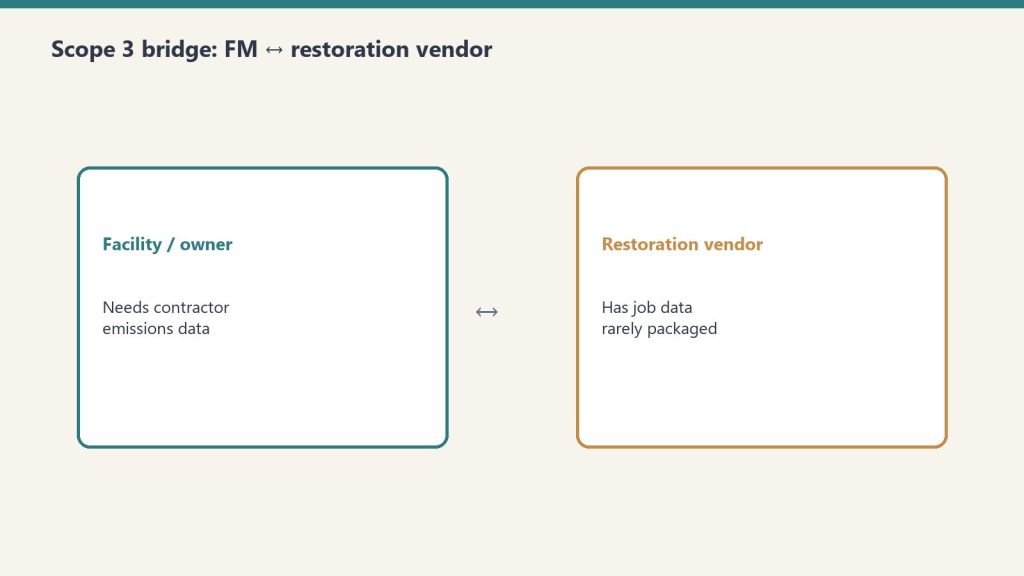
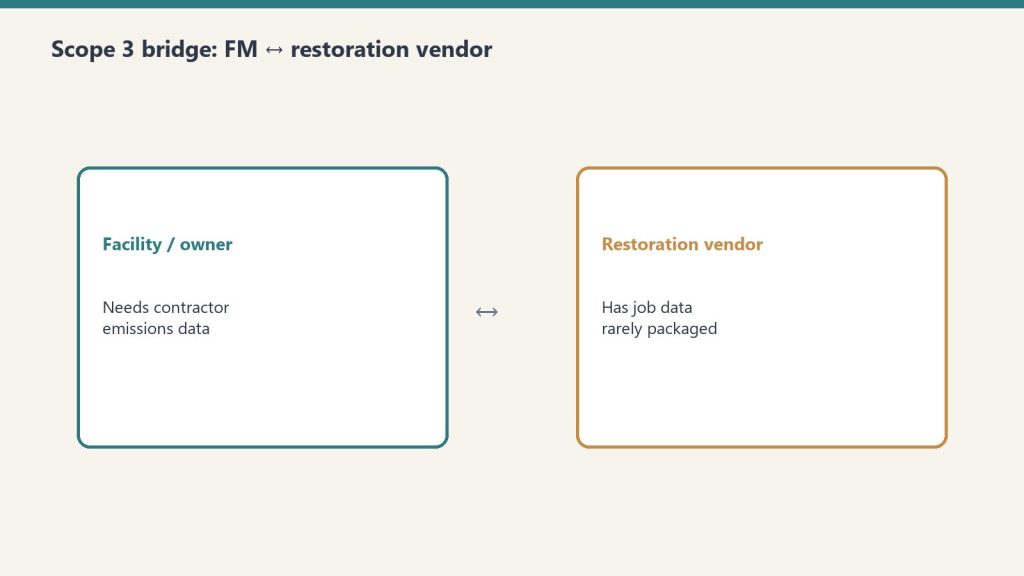
Scope 3 compliance for facility managers is fundamentally a vendor management problem. You cannot calculate your Category 1 emissions without data from your contractors, and you cannot get data from contractors without a systematic process for requesting, receiving, and storing it. This article provides a practical checklist for building that process — one that works for FM teams of any size and scales as your contractor pool grows.
Free Interactive Workbook
Use the live Scope 3 contractor compliance workbook
Map contractor categories, tier vendors, generate the contract clause, and export a program summary. Five phases. Live scoring. Work email unlocks the clause.
Before you can build a Scope 3 data collection process, you need to know which contractors generate material emissions on your behalf. Not all vendors are equal Scope 3 risks — prioritize based on emission intensity and spend.
Step 1: Map your contractor categories
List every category of contractor your FM program engages. For most corporate FM teams, the highest emission-intensity contractor categories are:
Construction and tenant improvements — embodied carbon in materials, significant waste
HVAC maintenance and retrofits — refrigerant handling, combustion equipment
Grounds and landscaping — fuel-burning equipment, fertilizer (N₂O emissions)
Janitorial and facility services — lower intensity but high volume
Step 2: Score by emission intensity × annual spend
Multiply each category’s estimated emission intensity (high/medium/low) by your annual spend in that category. The highest-scoring categories are your priority Scope 3 data gaps. Emergency restoration typically scores high on intensity even when annual spend is variable, because a single large water damage event can generate a meaningful emissions figure.
Phase 2: Vendor Qualification Updates
Step 3: Add Scope 3 capability questions to RFP and vendor qualification forms
For new vendor solicitations, add the following questions to your qualification criteria:
Does your organization track greenhouse gas emissions associated with individual project work?
Are you familiar with GHG Protocol Scope 3 Category 1 methodology?
Have you adopted the Restoration Carbon Protocol (for restoration vendors)?
Can you provide a per-project emissions summary upon project completion?
What job management system do you use, and does it support emissions data export?
Step 4: Tier your existing vendors
Survey your existing contractor pool with the same questions. Categorize vendors into three tiers: Tier 1 (already tracking emissions data), Tier 2 (willing to adopt a framework with support), and Tier 3 (unable or unwilling to provide data). Tier 3 vendors become a procurement risk factor — flag for transition to Tier 1 or 2 alternatives at contract renewal.
Phase 3: Contract Language
Phase 3 — contract language for Scope 3.
Step 5: Add Scope 3 data provisions to new contracts
For restoration contractors specifically, reference the Restoration Carbon Protocol as the accepted methodology standard. For other contractor categories, reference GHG Protocol Scope 3 Category 1 methodology and specify the data fields required. Include:
Obligation to provide a per-project emissions summary within 30 days of completion
Minimum data fields required (fuel, vehicle miles, waste type and weight, equipment hours)
Accepted methodology standard (RCP for restoration; GHG Protocol Category 1 for others)
Data format and delivery method (PDF report, CSV, or API-compatible format)
Right to audit contractor data collection processes during the contract term
Phase 4: Data Collection and Storage
Step 6: Establish a receiving process for contractor emissions reports
Decide where contractor emissions data will live in your FM systems. Options include: a dedicated folder in your CMMS work order system attached to each job record, a shared ESG data repository managed by your sustainability team, or a direct integration with your ESG reporting platform. The key is that every restoration job has an associated emissions record — not a separate tracking system you have to reconcile at year-end.
Step 7: Build a gap-filling protocol for missing data
Some contractors will not provide data even after you request it. Build a proxy calculation protocol for data gaps using spend-based or activity-based estimation. The RCP provides proxy tables for restoration jobs. For other categories, the GHG Protocol’s Scope 3 Calculation Guidance provides spend-based emission factors you can apply to invoice data.
Phase 5: ESG Inventory Integration
Phase 5 — ESG inventory integration.
Step 8: Integrate contractor data into your annual Scope 3 Category 1 calculation
At the end of each fiscal year, compile all contractor emissions reports and proxy estimates into your Scope 3 Category 1 input. Document your methodology, note which vendors provided primary data and which required proxy estimation, and flag any material gaps for disclosure in your ESG report. Most third-party ESG auditors will accept a documented methodology with known limitations more readily than an unexplained data gap.
The Checklist Summary
☐ Map contractor categories by emission intensity and annual spend
☐ Score and prioritize: emergency restoration at the top
☐ Add Scope 3 capability questions to vendor qualification forms
If you manage facilities for a corporate occupier and you have been trying to figure out how to get Scope 3 emissions data from your restoration contractors, the Restoration Carbon Protocol (RCP) exists to answer that question. This article explains what the RCP is, how it works, and what IFMA members specifically need to know about using it as a procurement and compliance tool.
What the Restoration Carbon Protocol Is
What the Restoration Carbon Protocol is.
The RCP is an industry self-standard published by Tygart Media that defines how restoration contractors should calculate, document, and report the greenhouse gas emissions associated with each project they complete. It is built on the GHG Protocol’s Corporate Value Chain (Scope 3) Standard — the same framework used by most corporate ESG reporting programs and required by SB 253 and CSRD.
The RCP fills a specific void: no restoration industry body — not IICRC, not RIA, not any trade association — had previously published a Scope 3 reporting methodology for restoration work. Commercial property managers and corporate FM teams asking their restoration vendors for emissions data were getting blank stares. The RCP gives contractors the methodology and gives FM procurement teams the standard to reference.
The Five Core Restoration Job Types and Their Scope 3 Mapping
Five core job types and their Scope 3 mapping.
The RCP maps each of the five primary restoration job types to the relevant GHG Protocol Scope 3 categories:
Water damage restoration: Category 1 (services purchased), Category 5 (waste from extracted water and contaminated materials)
Fire and smoke restoration: Category 1 (services), Category 5 (soot, char, and demolition debris waste streams)
In all five cases, the primary Scope 3 category for the FM client is Category 1 — Purchased Goods and Services. The emissions are generated by the contractor performing work on your behalf at your facility.
The 12 Data Points: What to Ask Your Contractor to Track
Twelve data points to ask your contractor to track.
The RCP defines 12 data points that a restoration contractor should capture on each job to enable a complete Scope 3 calculation. As an FM procurement professional, these are the data fields you should be requiring in your vendor agreements:
Total diesel consumed by drying and dehumidification equipment (gallons)
Total propane or natural gas consumed by heat drying equipment (cubic feet or gallons)
Total vehicle miles traveled to and from the site by all crew vehicles
Number of crew vehicle trips and vehicle types (van, pickup, box truck)
Total equipment operating hours (by equipment category)
Weight of water extracted and removed from the site (gallons or pounds)
Weight and type of contaminated materials removed (drywall, insulation, flooring, etc.)
Disposal method for each waste stream (landfill, recycling, hazardous waste facility)
Refrigerants used, recovered, or vented (for HVAC-adjacent work)
Materials installed by type and weight (for reconstruction phases)
Cleaning agents and chemical products used by product category
Total project duration in days
Not every data point is relevant to every job type. The RCP provides job-type-specific templates that pre-populate the relevant fields for water, fire, mold, hazmat, and biohazard jobs respectively.
How FM Teams Can Use the RCP Framework
There are three practical ways IFMA members can incorporate the RCP into their FM operations:
1. Vendor Qualification
Add RCP awareness to your restoration vendor qualification checklist. Ask prospective vendors whether they have adopted the RCP framework. Vendors who can demonstrate RCP familiarity are already capturing the data you need; vendors who cannot are a data gap risk for every job they complete.
2. Contract Language
Include a Scope 3 data provision clause in restoration vendor agreements referencing the RCP as the accepted methodology standard. This gives vendors a concrete deliverable (the RCP Job Carbon Report) rather than an open-ended “emissions data” request they have no idea how to fulfill.
3. Scope 3 Inventory Integration
Route the per-job RCP carbon reports from your restoration vendors into your Scope 3 Category 1 data collection system. Most ESG reporting platforms (Watershed, Persefoni, Salesforce Net Zero Cloud, etc.) accept Category 1 supplier data in standardized formats. The RCP report is designed to map directly to these platforms’ input requirements.
The RCP Is Free to Use
The Restoration Carbon Protocol is published as an open industry standard. There is no licensing fee, no certification requirement, and no vendor lock-in. FM teams can share the RCP framework directly with their restoration vendors at no cost. Contractors can adopt the RCP’s data capture templates and calculation methodology without purchasing anything.
The goal is adoption — the more restoration contractors who begin tracking RCP-compliant data, the more complete FM Scope 3 inventories become across the industry.
Frequently Asked Questions
Is the RCP recognized by IICRC or RIA?
The RCP is an independent industry self-standard published by Tygart Media. It is not currently endorsed by IICRC or RIA, as neither body has published a competing ESG standard. The RCP fills the void those bodies have not addressed. FM teams and restoration contractors can adopt it independently without waiting for official industry body endorsement.
How does a restoration contractor become RCP-certified?
The RCP v1.0 includes a self-certification checklist. Contractors complete the checklist to demonstrate they have implemented the required data capture processes and calculation methodology. Third-party verification is available for organizations that require audited certification. Details are published at tygartmedia.com/category/esg-restoration/.
California’s Climate Corporate Data Accountability Act — SB 253 — is the most consequential piece of corporate climate disclosure legislation in the United States. For facility managers at large corporate occupiers, its Scope 3 provision creates a specific and urgent vendor management problem that most FM teams have not yet fully reckoned with.
What SB 253 Actually Requires
SB 253 requires companies with annual revenues exceeding $1 billion that do business in California to publicly disclose their greenhouse gas emissions. The disclosure schedule is phased:
Scope 1 and Scope 2: First reports due in 2026 (covering fiscal year 2025 data)
Scope 3: First reports due in 2027 (covering fiscal year 2026 data)
The California Air Resources Board (CARB) is the administering body. Reports must be independently verified by a third-party auditor. The law applies to any company doing business in California — not just California-headquartered companies — which means the net is significantly wider than the state’s own corporate population.
This is not a voluntary framework. SB 253 carries penalties for non-compliance. The Scope 3 provision is the one that creates a direct operational problem for FM teams, because Scope 3 data lives outside your organization — in your contractors’ job management systems.
The Contractor Data Chain
The contractor data chain under SB 253.
Under the GHG Protocol’s Scope 3 framework — which SB 253 uses as its methodological basis — your restoration contractors are a Category 1 (Purchased Goods and Services) supplier. Every time you hire a restoration company to respond to a water intrusion event, a fire damage claim, or a mold remediation project, that contractor’s emissions for that job are technically part of your Scope 3 inventory.
The calculation is not optional. The GHG Protocol requires organizations to make a reasonable effort to quantify all material Scope 3 categories. For a large corporate occupier with a substantial real estate portfolio, emergency restoration is a recurring and quantifiable Category 1 exposure. Your ESG auditor will ask about it. Your SB 253 filing will need to account for it.
Why Most Restoration Contractors Cannot Provide This Data Today
Most restoration contractors cannot provide this data today.
The restoration industry has no Scope 3 standard. IICRC — the primary certification body for restoration professionals — has no ESG reporting guidance. RIA has no Scope 3 framework. Most restoration contractors manage their operations through job management software that tracks labor hours, materials, and job costs — not emissions.
This is not negligence; it is a gap that simply has not been filled until now. The Restoration Carbon Protocol (RCP) is the first industry self-standard that defines how restoration contractors should calculate and report their Scope 3 emissions data. It gives contractors the methodology, the data capture template, and the calculation framework — and it gives FM procurement teams the standard they can reference in vendor contracts.
What to Put in Your Vendor Agreements Now
Put requirements in vendor agreements now.
The most practical SB 253 preparation step for FM procurement teams is to update restoration vendor agreements to include a Scope 3 data provision clause. Here is the language framework:
“Vendor agrees to provide a per-project greenhouse gas emissions summary for each project completed at Client facilities, using a documented calculation methodology consistent with GHG Protocol Scope 3 Category 1 guidelines. The summary shall include: total fuel consumption by equipment type, vehicle miles traveled, waste materials removed by type and weight, and total equipment operating hours. Submissions shall be provided within 30 days of project completion.”
This clause does not require contractors to be ESG experts. It requires them to track and report the underlying data points from which a Scope 3 calculation can be made. Contractors who have adopted the RCP framework already capture this data as part of their standard job documentation.
The Retroactive Data Problem
SB 253 requires disclosure for fiscal year 2026 data, meaning the clock is already running. If your organization does business in California and exceeds the revenue threshold, your restoration vendors should be tracking Scope 3 data for jobs completed throughout 2026. Waiting until late 2026 to request this data will result in gaps that your ESG auditor will flag.
For restoration jobs already completed in 2025 and early 2026, proxy-based estimation is acceptable under GHG Protocol methodology when primary data is unavailable. The RCP provides proxy calculation tables for each restoration job type, allowing FM teams to estimate historical emissions from basic job records (square footage treated, job duration, equipment type). This is not ideal, but it is methodologically defensible and far better than a data gap.
The SB 253 Compliance Checklist for FM Teams
Confirm whether your organization meets the SB 253 threshold (>$1B revenue, does business in California)
Identify all restoration and specialty trade contractors in your vendor pool as Category 1 Scope 3 sources
Update vendor agreements with a Scope 3 data provision clause (language above)
Share the RCP framework with active vendors so they understand what data to capture
Establish a process for collecting and storing per-job emissions summaries in your FM system
Engage your ESG consultant to integrate contractor data into your Scope 3 Category 1 calculation methodology
Plan for third-party verification of your Scope 3 data — auditors will scrutinize Category 1 more than any other category
Does SB 253 apply if my company is not headquartered in California?
Yes. SB 253 applies to any company that “does business in California” and meets the revenue threshold. This is broadly interpreted to include companies with California employees, customers, or operations — even if they are incorporated and headquartered elsewhere.
What is the penalty for non-compliance with SB 253 Scope 3 provisions?
CARB has authority to assess administrative penalties for non-compliance. The specific penalty structure is being finalized through rulemaking. Consult your legal counsel for the current enforcement guidance applicable to your organization.
Can I use a spend-based methodology for restoration contractor Scope 3 data?
Spend-based estimation (using economic input-output data) is permitted under GHG Protocol methodology as a fallback when primary or activity-based data is unavailable. However, third-party auditors generally flag spend-based estimates as lower quality than activity-based calculations. For a recurring Category 1 source like restoration contractors, building toward activity-based data is the appropriate goal.
If you manage facilities for a large corporate occupier, you have almost certainly heard the phrase “Scope 3 emissions” from your sustainability team, your CFO, or your ESG consultant. What you may not have heard is a clear explanation of what that means for your day-to-day vendor management — and why the contractors who respond to your water damage and mold remediation calls are sitting in the middle of your most difficult compliance gap.
The Three Scopes: A Plain-Language Primer
Three scopes primer — contractors sit in Scope 3.
The GHG Protocol’s Corporate Standard divides greenhouse gas emissions into three categories based on where they originate relative to your organization’s operations:
Scope 1 — Direct emissions from sources your organization owns or controls. The combustion in your building’s boilers, the fuel in your company-owned fleet vehicles, the refrigerants in your HVAC systems.
Scope 2 — Indirect emissions from purchased electricity, heat, or steam. The power your facilities consume from the grid.
Scope 3 — All other indirect emissions across your value chain. Everything that happens upstream (your supply chain) and downstream (how your products or services are used) that generates emissions on your behalf.
Scope 1 and Scope 2 are manageable. You own the sources or the meters. You have the data. Scope 3 is where it gets hard — because Scope 3 data lives in other organizations’ systems, not yours.
The 15 Categories of Scope 3
The GHG Protocol breaks Scope 3 into 15 categories across upstream and downstream activities. For a corporate FM managing occupied facilities, the most relevant upstream categories are:
Category 1 — Purchased Goods and Services: The emissions associated with producing and delivering everything your organization buys from third parties. For FMs, this includes every contractor, vendor, and service provider who performs work at your facilities — including your restoration contractors.
Category 2 — Capital Goods: Emissions from the production of capital equipment and major building systems your organization purchases.
Category 4 — Upstream Transportation and Distribution: Relevant when contractors transport materials and equipment to your site.
Category 5 — Waste Generated in Operations: Emissions from waste your organization generates — relevant when restoration work produces debris, contaminated materials, or demolition waste disposed of on your behalf.
Why Contractors Are Your Hardest Data Category
Why contractors are your hardest data category.
Among all the inputs to a corporate FM’s Scope 3 inventory, contractor-generated emissions are consistently the most difficult to quantify. Here is why:
Contractors do not routinely track their own emissions. Most restoration, janitorial, maintenance, and specialty trade contractors have no internal system for calculating the greenhouse gas footprint of individual jobs. They track labor hours, materials costs, and square footage — not carbon.
Restoration work is episodic. Unlike your regular janitorial or HVAC maintenance contractor, your restoration vendors are called in during emergencies. There is no standing purchase order to attach emissions data to. Each job is a separate event, often managed by a different project manager.
No industry standard exists for restoration Scope 3 data. IICRC — the restoration industry’s primary certification body — has no ESG reporting standard. RIA has no Scope 3 guidance. There is no form, no template, no industry norm for what a restoration contractor should provide.
The emissions profile of restoration work is complex. A single water damage job involves diesel-powered drying equipment running 24/7 for days, hazardous material disposal, multiple material categories, and vehicle trips from multiple crew members. Calculating the emissions accurately requires a methodology most contractors have never seen.
The 2027 Problem
California SB 253 — the Climate Corporate Data Accountability Act — requires companies with over $1 billion in annual revenue doing business in California to disclose their Scope 3 emissions starting with the 2027 reporting year. The EU’s CSRD is already in effect and expanding. CDP and GRESB already request Scope 3 data from the organizations they track.
For FMs at large corporate occupiers, this creates a specific operational problem: your sustainability team needs contractor emissions data for the 2027 filing, your contractors do not have a system for providing it, and there is no industry standard to point them to. The gap between the regulatory requirement and the contractor’s current capability is the problem this publication addresses.
What Good Contractor Scope 3 Data Looks Like
What good contractor Scope 3 data looks like.
The Restoration Carbon Protocol (RCP) defines 12 data points that every restoration job ticket should capture to enable Scope 3 calculation. At a minimum, FM procurement teams should be asking their restoration vendors for:
Total fuel consumed by diesel-powered drying and dehumidification equipment (gallons)
Total vehicle miles traveled by contractor crews to and from the site
Weight and type of waste materials removed and method of disposal
Refrigerants used or recovered (for HVAC-adjacent restoration work)
Materials installed by type and weight (for reconstruction phases)
Total job duration and equipment operating hours
With these inputs, a standardized calculation using EPA emission factors can produce a per-job carbon estimate that satisfies Scope 3 Category 1 methodology. The RCP provides exactly that calculation framework — free for any contractor or FM team to use.
What to Do Now
If the 2027 Scope 3 deadline is on your radar, the most practical steps you can take today are:
Audit your vendor pool for contractors who perform Category 1 services. Restoration, abatement, specialty trades, and maintenance contractors are your highest-priority Scope 3 data gaps.
Include a Scope 3 data provision clause in new vendor agreements. Require contractors to provide a per-job emissions summary using a standardized methodology.
Share the RCP framework with your restoration vendors. It gives them the methodology, the data capture form, and the calculation tools — everything they need to start providing compliant data on the next job.
Start tracking now, even if imperfectly. A reasonable estimate based on available data is better than a data gap. Your ESG auditor would rather see a documented methodology with known limitations than a blank line item.
Frequently Asked Questions
Does every facility manager need to report Scope 3?
Mandatory Scope 3 reporting under SB 253 applies to companies with over $1 billion in annual revenue doing business in California. CSRD applies to large EU entities. Many FMs at smaller organizations will face voluntary disclosure pressure through CDP participation, GRESB assessments, or investor requirements. Regardless of regulatory mandate, proactively building Scope 3 data capability now reduces compliance cost later.
Are restoration contractors required to provide Scope 3 data?
Not yet — but their FM clients increasingly will be required to report it. The most practical approach is to contractually require Scope 3 data from restoration vendors as part of vendor onboarding, rather than trying to collect it retroactively after a job is complete.
Part of the IFMA Scope 3 series on tygartmedia.com.
When sustainability consultants talk about ESG in commercial real estate, they often treat IFMA and BOMA as interchangeable acronyms for “building people.” They are not. The distinction between these two associations is not a branding detail — it is a fundamental difference in who you work for, what buildings you manage, and which Scope 3 obligations land on your desk. Getting this wrong means applying the wrong compliance framework to the wrong problem.
The Core Difference: Occupier vs. Owner
Occupier vs owner — where each association lives.
IFMA — the International Facility Management Association — primarily serves facility managers who work for corporate occupiers. These are the FMs at a hospital system, a university, a Fortune 500 headquarters, or a government agency. They manage buildings that their organization uses to do its business. They do not own those buildings as an investment. They are the operational stewards of space their organization occupies.
BOMA — the Building Owners and Managers Association — primarily serves property owners and commercial property management firms. BOMA members typically work for organizations whose business model is real estate: they own or manage buildings as assets, lease space to tenants, and generate revenue from that occupancy. The building is the product, not the platform.
This single distinction — occupier vs. owner — changes everything about how Scope 3 ESG obligations flow.
Contractor supply chain data gaps (Category 1); purchased services
Tenant energy use; embodied carbon in renovation; asset-level GRESB
Restoration relevance
Every emergency restoration job generates Scope 3 data the FM must capture
Tenant improvement work; asset restoration after casualty
Reporting framework
GHG Protocol Corporate Standard; California SB 253; EU CSRD
GRESB Real Estate Assessment; ENERGY STAR; local building performance standards
Why This Matters for Scope 3 Specifically
Under the GHG Protocol’s Scope 3 framework, a corporate occupier’s emissions inventory must include the activities of every contractor who performs services at their facilities. Water damage restoration, fire and smoke remediation, mold abatement, asbestos removal — every one of these jobs generates greenhouse gas emissions that belong somewhere in the FM’s Scope 3 report. Specifically, restoration contractor activity typically falls under Category 1 (Purchased Goods and Services) or Category 14 (Franchises), depending on the contractual structure.
The BOMA member’s Scope 3 picture is different. A property manager’s primary Scope 3 exposure is Category 13 (Downstream Leased Assets) — the energy and emissions generated by the tenants who occupy their buildings. Restoration work on a BOMA member’s asset matters for GRESB and insurance, but it is not the core Scope 3 data gap they are trying to solve.
The IFMA member, by contrast, is the one whose sustainability team is currently trying to figure out how to get emissions data from their restoration vendor. They are the ones receiving questionnaires from CDP and GRESB asking about contractor emissions. They are the ones whose corporate ESG report will be incomplete without restoration job data. And right now, they have no standard way to get it.
The 2027 Deadline Is the IFMA Problem, Not the BOMA Problem
California’s SB 253 — the Climate Corporate Data Accountability Act — requires companies with over $1 billion in annual revenue doing business in California to disclose their Scope 3 emissions beginning in 2027. The EU’s Corporate Sustainability Reporting Directive (CSRD) is already in effect for large European companies, with phased expansion through 2026. Both frameworks require supply chain emissions data — which means contractor data.
For the corporate FM managing a large occupier’s portfolio, this deadline is operational. Their sustainability team is assembling the Scope 3 inventory now. They need contractor emissions data now. Every restoration company they have worked with in the past three years is a potential data gap in their 2027 filing.
BOMA members face a related but structurally different pressure: their tenants are the Scope 3 reporters. The property manager’s role is to provide energy use data to tenants, not necessarily to collect contractor emissions data for their own disclosure. This is a meaningful distinction. The compliance urgency for Scope 3 contractor data sits much more squarely with the IFMA member.
The Missing Bridge: Restoration Contractors and Scope 3 Data
The missing bridge: restoration contractors and Scope 3 data.
Here is the specific gap this publication exists to close: restoration contractors — the companies that respond to water damage, fire, mold, and environmental emergencies at commercial facilities — have no standardized way to provide Scope 3 emissions data to their FM clients. The International Institute of Cleaning and Restoration Certification (IICRC) has no ESG standard. The Restoration Industry Association (RIA) has no Scope 3 guidance. No industry body has built the framework that tells a restoration contractor what data to capture on each job ticket so their FM client can use it in a Scope 3 report.
This is the problem the Restoration Carbon Protocol (RCP) was built to solve. The RCP is a Tygart Media-published industry self-standard that maps restoration job types to the GHG Protocol’s 15 Scope 3 categories, defines the 12 data points every job ticket should capture, and provides the calculation methodology restoration contractors need to produce credible emissions data. It is the operational bridge between the FM’s Scope 3 disclosure obligation and the restoration contractor’s job management system.
What IFMA Members Should Be Asking Their Restoration Vendors Today
What IFMA members should ask restoration vendors today.
If you are a facility manager with Scope 3 reporting obligations, here are the five questions you should be putting to every restoration contractor in your vendor pool:
Can you provide a per-job emissions summary for each project you complete at our facilities? If the answer is no, that is a gap in your Scope 3 Category 1 data.
Do you track materials disposed of by type and weight? Waste stream data is a required input for Scope 3 calculation under GHG Protocol methodology.
Do you track vehicle and equipment fuel consumption for each project? Mobile combustion is a Category 1 input that most restoration contractors currently ignore.
Are you familiar with the Restoration Carbon Protocol? RCP-aware contractors are already capturing the data FMs need.
Would you be willing to complete a standardized carbon data form for each project? The RCP Job Carbon Report is a one-page form any contractor can complete without a sustainability consultant.
Why Tygart Media Covers This Beat
Tygart Media’s position in the restoration industry — through the Restoration Carbon Protocol, the Restoration Golf League network, and years of content production for restoration operators — gives us a direct view into the contractor side of this data gap. This IFMA Scope 3 category exists to build the FM side of the same bridge: to give facility managers the framework, vocabulary, and vendor guidance they need to close their Scope 3 contractor data gap before the 2027 deadline arrives.
This is not a BOMA story. It is not a property management story. It is a facility management story — about the corporate occupier’s FM team trying to satisfy a board-level ESG commitment with incomplete data from contractors who have never been asked for it before. We are building the source of truth for that problem.
What is the difference between IFMA and BOMA for ESG purposes?
IFMA serves facility managers who manage buildings for corporate occupiers — organizations that use the space for their own operations. BOMA serves property owners and managers who lease space to tenants as a business. For Scope 3 ESG, IFMA members must capture contractor emissions data as part of their corporate supply chain disclosure, while BOMA members primarily focus on tenant energy use and asset-level performance benchmarking.
Why do restoration contractors matter for IFMA Scope 3 reporting?
Restoration contractors perform services at IFMA members’ facilities. Under the GHG Protocol, the emissions from those services are part of the corporate occupier’s Scope 3 inventory — typically Category 1 (Purchased Goods and Services). Without standardized emissions data from restoration vendors, the FM’s Scope 3 report has a recurring gap every time an emergency occurs at a managed facility.
What is the Restoration Carbon Protocol?
The Restoration Carbon Protocol (RCP) is an industry self-standard published by Tygart Media that maps restoration job types to GHG Protocol Scope 3 categories and defines the data restoration contractors should capture to enable their FM clients’ Scope 3 reporting. It is the first framework of its kind in the restoration industry.
When does Scope 3 reporting become mandatory for large companies?
California SB 253 requires Scope 3 disclosure for companies with over $1 billion in annual revenue doing business in California beginning in 2027. The EU’s CSRD is already in force for large European entities, with phased expansion through 2026. Many voluntary frameworks (CDP, GRESB) already request Scope 3 data.
This article is part of Tygart Media’s IFMA Scope 3 category — the facility manager’s source of truth for Scope 3 ESG reporting and contractor data standards.
By Will Tygart• Long-form Position
• Practitioner-grade
When Google launched the Universal Commerce Protocol at NRF in January 2026, the announcement was framed as an e-commerce story. Shopify, Walmart, Target, Visa — merchants and payment processors getting their systems ready for AI agents that shop, compare, and execute purchases without human intervention. That framing is correct but incomplete. UCP is not just a commerce standard. It is a template for how open protocols create movements.
The Restoration Carbon Protocol is a different kind of standard in a completely different industry. But when you understand what UCP actually does architecturally — and why it succeeded where dozens of previous e-commerce APIs failed — you start to see exactly how RCP gets from a 31-article framework on tygartmedia.com to an industry-wide adopted standard that BOMA, IFMA, and institutional ESG reporters actually depend on.
The mechanism is the same. The domain is different. And there is a version two of RCP that plugs directly into the UCP trust architecture — if the restoration industry moves in the next 18 months.
What UCP Actually Does That Previous Commerce APIs Didn’t
What UCP actually does that previous commerce APIs didn’t.
The history of e-commerce is littered with failed attempts at standardization. Every major platform — Amazon, eBay, Shopify, Magento — built its own API. Merchants implemented each one separately. Integrators spent years building custom connectors. The problem was not technical. The problem was trust and authentication. Every API required a bilateral relationship: the merchant trusted this specific buyer’s agent, that agent trusted this specific merchant’s data. Scaling to the open web required n² trust relationships. It never worked.
UCP solved this with a different architecture. Instead of bilateral trust, it established a protocol layer — a shared standard that any compliant agent and any compliant merchant can speak without a pre-existing relationship. An AI agent that implements UCP can query any UCP-compliant catalog, check any UCP-compliant inventory, and execute against any UCP-compliant checkout — not because it has a relationship with that merchant, but because both parties speak the same authenticated protocol.
The authentication is the product. UCP’s standardized interface means that a merchant’s decision to implement the protocol is simultaneously a decision to trust any UCP-authenticated agent. The trust is embedded in the standard, not in the bilateral relationship.
Google’s Agent Payments Protocol (AP2), which sits alongside UCP, formalized this with “mandates” — digitally signed statements that define exactly what an agent is authorized to do and spend. The mandate is the credential. Any merchant who accepts UCP mandates accepts a verifiable statement of agent authorization without knowing anything specific about the agent that issued it.
That architecture — open protocol, embedded authentication, mandate-based trust — is exactly what the restoration industry needs for Scope 3 emissions data. And RCP v1.0 has already built the content layer. The question for v2 is whether to build the authentication layer.
The RCP Authentication Problem (That UCP Already Solved)
The RCP authentication problem UCP already solved.
RCP v1.0 produces per-job emissions records — JSON-structured Job Carbon Reports that restoration contractors deliver to commercial property clients for their GRESB, SBTi, and SB 253 reporting. The framework is solid. The methodology is sourced and auditable. The schema is machine-readable.
But right now, there is no authentication layer. A property manager who receives an RCP Job Carbon Report from a contractor has no way to verify that the contractor actually follows the methodology, uses the current emission factors, or has gone through any validation process. They have to trust the contractor’s word — which is exactly the problem that makes Scope 3 data from supply chains unreliable for ESG auditors.
This is the bilateral trust problem all over again. The property manager trusts this specific contractor’s data. That contractor trusts this specific property manager’s reporting process. It does not scale to a portfolio of 200 contractors across 800 properties.
UCP solved the equivalent problem in commerce. The RCP organization — whoever formally governs the standard — can solve the same problem in ESG supply chain reporting with an analogous architecture.
What RCP Certification Could Look Like in a UCP-Style Architecture
Imagine a restoration contractor completes an RCP certification process. They demonstrate that they collect the 12 required data points, apply the current emission factors, produce Job Carbon Reports in the RCP-JCR-1.0 schema, and maintain source documents for seven years. The RCP organization validates this and issues a cryptographically signed certification credential — an RCP Mandate.
The RCP Mandate is the contractor’s credential. It is not issued to a specific property manager. It is not dependent on a bilateral relationship. It is a verifiable statement, signed by the RCP authority, that this contractor’s emissions data meets the methodology standard. Any property manager, ESG platform, or auditor who accepts RCP Mandates can trust the data from any RCP-certified contractor — not because they know that contractor, but because the standard’s authentication is embedded in the credential.
This is precisely how UCP mandates work in commerce. The signed statement creates protocol-level trust that does not require a pre-existing relationship.
The downstream effects are the same as in commerce:
For contractors: RCP certification becomes a competitive signal that travels with the data. An RCP Mandate delivered with a Job Carbon Report tells the property manager’s ESG team: this data does not need to be validated separately. It has already been validated by a recognized standard.
For property managers: They can accept RCP-certified contractor data directly into their ESG reporting workflows without manual review. The certification is the audit trail. Measurabl, Yardi Elevate, and Deepki — the ESG data management platforms most of them use — can be built to accept RCP Mandate credentials alongside RCP JSON records and flag them automatically as verified-methodology data.
For ESG auditors: A property portfolio where all restoration contractor data comes from RCP-certified vendors is auditable without going back to each contractor. The mandate chain is the evidence. Limited assurance under CSRD or SB 253 becomes a single check — are these vendors RCP-certified? — rather than a vendor-by-vendor methodology review.
For the industry: Certification creates a selection mechanism. Property managers who require RCP-certified vendors in their preferred contractor agreements are no longer asking for a one-off document. They are asking for protocol compliance — the same way a merchant asking for UCP compliance is not asking for a custom integration, they are asking for standards adoption.
The Protocol Stack for RCP v2
Following the UCP architecture model, a complete RCP v2 would have three layers — matching the commerce, payments, and infrastructure layers of the agentic commerce stack:
Layer 1: The Data Layer (Already Built — RCP v1.0)
The methodology, emission factors, JSON schema, five job type guides, audit readiness documentation, and public API. This is the equivalent of UCP’s catalog query and inventory check layer — the standardized interface for what data is produced and how it is structured. RCP v1.0 is complete at this layer.
Layer 2: The Authentication Layer (RCP v2 Target)
The certification program, the mandate credential, the verification mechanism. This is the equivalent of UCP’s trust and authentication architecture — the layer that makes data from one party trusted by another without a bilateral relationship. Key components:
RCP Contractor Certification: documented audit of data capture practices, schema compliance, emission factor vintage, and source document retention
RCP Mandate: cryptographically signed certification credential, issued per contractor, versioned to the RCP release used, with an expiration and renewal cycle
Mandate verification endpoint: a public API (building on the existing tygart/v1/rcp namespace) where any platform can POST a mandate token and receive a verified/not-verified response with credential metadata
Certified contractor registry: a public directory of RCP-certified organizations, queryable by name, state, and certification status
Layer 3: The Infrastructure Layer (RCP v2 Target)
The machine-to-machine data exchange infrastructure — the equivalent of MCP and A2A in the agentic commerce stack. A contractor’s job management system (Encircle, PSA, Dash, Xcelerate) that natively implements RCP can transmit certified Job Carbon Reports directly to a property manager’s ESG platform without human intermediation. The report travels with the mandate credential. The platform verifies the credential, ingests the data, and flags it as RCP-verified — automatically. No email, no manual upload, no data entry.
This is what makes it a movement rather than a document standard. The data flows automatically between authenticated parties. The human steps are eliminated. The protocol becomes infrastructure.
Why Open Protocol Architecture Enables Movements
UCP didn’t succeed because Google built good documentation. It succeeded because Google made it open — any merchant can implement it, any agent can speak it, no license fee, no bilateral negotiation, no approval required. Shopify and a regional boutique retailer are equal participants in the UCP ecosystem because the protocol is the credential, not the relationship with Google.
That openness is what creates network effects. Every new UCP-compliant merchant makes the protocol more valuable for every agent. Every new UCP-compliant agent makes the protocol more valuable for every merchant. The standard grows because participation is self-reinforcing.
RCP v1.0 is already open. The framework is CC BY 4.0 — free to use, implement, and build upon. The API is public. The emission factors are published with sources. Any restoration company can implement it today without permission.
What RCP v2 adds is the authentication layer that makes open participation verifiable. The difference between “any company claims to follow RCP” and “any company can prove they follow RCP” is the difference between a document standard and a protocol. And the difference between a protocol and a movement is whether the infrastructure layer — the machine-to-machine data exchange — gets built.
The agentic commerce stack took 18 months from UCP’s launch to meaningful adoption in production commerce systems. The RCP timeline is not 18 months from today — it’s 18 months from the moment RIA, IICRC, or a major industry insurer formally endorses the standard. That endorsement is the equivalent of Shopify and Walmart signing on to UCP at NRF. It’s the signal that tells the rest of the ecosystem: this is the standard, build to it.
The Restoration Industry’s Unique Position
The restoration industry’s unique position.
BOMA and IFMA are working the problem from the property owner side — how do we get our vendor supply chains to report Scope 3 data? They don’t have the answer because the answer requires contractor-side infrastructure that commercial real estate organizations cannot build. They can mandate data. They cannot build the methodology.
The restoration industry can. The 12 data points are already defined. The five job type methodologies are already published. The JSON schema is live. The API is running. The audit readiness guide exists. The only missing component is the formal certification program and the mandate credential that makes all of it protocol-grade rather than document-grade.
This is what positions restoration as the leading industry in commercial property Scope 3 compliance — not just a participant but the infrastructure provider. The industry that built the standard that the property management industry depends on. That is a fundamentally different value proposition than “we report our emissions.”
The parallel to UCP is exact: Google didn’t just participate in e-commerce. They built the protocol layer that made agentic commerce possible at scale. The restoration industry, through RCP, can build the protocol layer that makes supply chain Scope 3 compliance possible at scale for commercial real estate. And unlike Google, the restoration industry doesn’t need to be invited to the table. The table was already set at tygartmedia.com/rcp.
What RIA Savannah Should Start
The conversation at RIA Savannah on April 27 isn’t about persuading the industry to care about carbon. It’s about presenting the infrastructure that already exists and asking whether the industry wants to formally govern it. The RCP v1.0 framework, the public API, the certification roadmap — these are things that exist today. The question for RIA leadership is whether they want the restoration industry to own the protocol layer for commercial property Scope 3 compliance, or whether they want to watch a property management trade association or a Canadian software company build something proprietary in their place.
The window is real. ESG data platforms are making vendor integration decisions now. Property managers are establishing preferred contractor Scope 3 requirements now. California SB 253’s Scope 3 deadline is 2027. GRESB assessments with contractor data coverage scoring are active this year. The infrastructure moment is not coming. It is here.
A movement needs three things: an open standard, an authentication layer, and a network effect. RCP v1.0 is the standard. The authentication layer is the RCP v2 roadmap. The network effect starts the moment an industry organization formally endorses the protocol and restoration contractors have a reason to get certified rather than merely compliant.
That is what UCP teaches us about RCP. The protocol is not the product. The authenticated, machine-readable, verifiable data infrastructure that emerges from the protocol is the product. And the industry that builds that infrastructure owns the category.
The RCP REST API endpoint allows software developers, ESG platforms, and job management systems to programmatically access the full Restoration Carbon Protocol framework — all articles, emission factors, schema documentation, and article relationships — without scraping the site. This endpoint is part of the Tygart Media REST API and is publicly accessible without authentication.
Base URL:https://tygartmedia.com/wp-json/tygart/v1/rcp
Endpoints
RCP API endpoints at a glance.
GET /wp-json/tygart/v1/rcp
Returns the complete RCP framework index: all published articles with metadata, their relationship type within the framework, and links to full content.
Request:
GET https://tygartmedia.com/wp-json/tygart/v1/rcp
Accept: application/json
Returns the full RCP-JCR-1.0 JSON Schema for a Job Carbon Report — the machine-readable data standard for per-job Scope 3 emissions records. This is the canonical schema endpoint for software developers implementing native RCP data capture.
Request:
GET https://tygartmedia.com/wp-json/tygart/v1/rcp/schema
Accept: application/json
Returns all RCP emission factors as structured JSON — vehicle emission factors, material factors, waste disposal factors, demolished building material factors, and the eGRID subregional table. This allows ESG platforms and carbon calculators to pull the current RCP factor set programmatically rather than hardcoding values.
Request:
GET https://tygartmedia.com/wp-json/tygart/v1/rcp/factors
Accept: application/json
Returns articles filtered by framework type. Valid type values: job_type_guide, regulatory, data_standard, technical, strategy, introduction, commercial.
Example — get all job type guides:
GET https://tygartmedia.com/wp-json/tygart/v1/rcp/articles/job_type_guide
Response: Array of article objects matching that type, with title, URL, excerpt, and job_types array (e.g., ["water_damage", "category_2", "category_3"]).
Existing WordPress REST API — RCP Queries
Existing WordPress REST API queries for RCP.
While the tygart/v1/rcp endpoints above are planned for v1.1 deployment, the existing WordPress REST API at /wp-json/wp/v2/ already supports filtered RCP queries using tag and category IDs.
Get all RCP articles
GET https://tygartmedia.com/wp-json/wp/v2/posts?tags=409&per_page=50
# Tag 409 = "RCP" — returns all 30 published RCP articles
Get RCP articles by sub-type
# Developer/technical articles only (tag 411 = Developer Reference)
GET https://tygartmedia.com/wp-json/wp/v2/posts?tags=409,411&per_page=20

# Regulatory articles (tag 369 = SB 253)
GET https://tygartmedia.com/wp-json/wp/v2/posts?tags=409,369&per_page=20
Get a specific article with full content
# RCP v1.0 Full Framework Document (post ID 2976)
GET https://tygartmedia.com/wp-json/wp/v2/posts/2976

# Returns: id, title, content.rendered, excerpt.rendered,
#          link, slug, date, modified, tags, categories
Get the RCP hub page
GET https://tygartmedia.com/wp-json/wp/v2/pages?slug=rcp
# Returns the hub page at /rcp/ with full content and navigation structure
Response fields available per post
Field
Type
Description
id
integer
WordPress post ID — stable across updates
slug
string
URL slug — permanent, do not rely on for API queries (use ID)
title.rendered
string
HTML-decoded article title
content.rendered
string
Full article HTML — includes all tables, methodology, worked examples
excerpt.rendered
string
Summary paragraph — suitable for search result snippets
link
string
Canonical URL
modified
datetime
Last updated — use to detect emission factor version updates
tags
array[int]
Tag IDs — use 409 (RCP), 411 (Developer) for filtering
RCP Tag ID Reference
RCP tag ID reference for developers.
Tag ID
Name
Use
409
RCP
All RCP articles — primary filter for the full framework
The following endpoints are targeted for deployment in RCP v1.1, pending implementation by the infrastructure team. The spec above defines the intended response format.
GET /wp-json/tygart/v1/rcp — Framework index with article type classification
GET /wp-json/tygart/v1/rcp/schema — RCP-JCR-1.0 JSON Schema as a clean API response
GET /wp-json/tygart/v1/rcp/factors — All emission factors as structured JSON with vintage metadata
GET /wp-json/tygart/v1/rcp/factors/{category} — Filtered factor sets (transportation, electricity, waste, materials)
GET /wp-json/tygart/v1/rcp/articles/{type} — Articles filtered by framework type
Software vendors who want to implement the planned endpoints ahead of formal deployment, or who have implementation questions, contact: rcp@tygartmedia.com
Every RCP article published so far covers how to measure and report the Scope 3 emissions your restoration work generates. This article introduces a complementary concept: carbon avoidance — the quantified emissions that did not happen because of deliberate operational choices made on a specific job.
Avoided emissions are not the same as offsets. They are not purchased credits. They are not estimates of what another contractor might have done. They are documented, job-level calculations showing that a specific decision — dry in place instead of demolish, drywall recycled instead of landfilled, electric van instead of diesel truck — produced a measurable reduction from what the baseline calculation would have shown. When delivered alongside a standard RCP Job Carbon Report, avoided emissions data transforms the contractor from a Scope 3 data source into a Scope 3 reduction partner.
Why Avoided Emissions Matter to Your Commercial Clients
Why avoided emissions matter to commercial clients.
A commercial property manager with an SBTi commitment needs two things from their restoration contractor supply chain: the actual emissions figure for their Scope 3 inventory, and evidence that those emissions are declining. The actual figure alone satisfies a disclosure requirement. Evidence of decline satisfies a reduction target.
SBTi supplier engagement targets — which require companies to show that their supply chain partners are actively reducing emissions — are best evidenced not by a contractor’s promise to do better but by documented proof that specific jobs generated fewer emissions than the counterfactual. An RCP Job Carbon Report that includes an avoided emissions summary gives the property manager exactly that evidence in a form their ESG team can cite in annual reporting.
Under the GRESB GH1 indicator’s data coverage scoring, a client who can show that a contractor’s actual job data consistently outperforms the spend-based benchmark is in a stronger scoring position than one using estimates. Avoided emissions documentation supports that narrative directly.
The Three Categories of Restoration Carbon Avoidance
Three categories of restoration carbon avoidance.
Category A: Dry-In-Place vs. Demolish-and-Replace
The most material avoidance opportunity in restoration is also the most consequential clinical decision: dry in place or tear it out. When a Category 2 water damage job achieves successful in-place drying of drywall that would otherwise have been demolished and replaced, the avoided emissions include:
Category 12 avoided: embodied carbon of the drywall that was not demolished (0.16 tCO₂e/ton landfilled, plus the embodied carbon of new drywall not manufactured)
Category 5 avoided: disposal emissions from the demolition debris that was not generated
Category 4 partial: some debris hauling trips eliminated
Calculation methodology: Document the affected area that was successfully dried in place (square footage). Calculate the weight of drywall that would have been demolished using the standard proxy (2.5 lbs/sq ft for 1/2″ drywall). Apply the landfill emission factor plus the embodied carbon of new drywall avoided. Sum across Categories 5 and 12.
Example: A 400 sq ft wall assembly successfully dried in place instead of demolished: 400 × 2.5 lbs = 1,000 lbs = 0.45 tons avoided demolition. At 0.16 tCO₂e/ton (landfill) + 0.12 kg CO₂e/kg for new drywall embodied carbon (ICE Database), total avoided emissions ≈ 0.127 tCO₂e for this decision alone.
Category B: Waste Diversion from Landfill
When demolished materials are diverted from landfill to recycling — drywall to a gypsum recycler, clean wood to a biomass facility, metal to a scrap recycler — the difference between the landfill emission factor and the recycling emission factor represents avoided emissions.
EPA WARM v16 avoidance factors for key restoration materials:
Material
Landfill (tCO₂e/ton)
Recycled (tCO₂e/ton)
Avoided per ton diverted
Gypsum drywall
0.160
0.020
0.140
Carpet and pad
0.330
0.050
0.280
Dimensional lumber (uncharred)
0.039
-0.150
0.189
Vinyl/LVP flooring
0.280
0.080
0.200
Metals (mixed)
0.025
-0.420
0.445
Source: EPA WARM v16. Negative recycling values reflect avoided virgin production emissions — recycling metals and wood avoids more emissions than landfilling would have produced.
Calculation methodology: Obtain a weight receipt from the recycling facility documenting the material type and weight diverted. Subtract the recycling emission factor from the landfill emission factor. Multiply by tons diverted. This is the avoided emission attributable to the diversion decision.
Category C: Low-Emission Equipment or Material Substitution
When a contractor deploys a lower-emission alternative to what would otherwise have been used — an electric monitoring vehicle instead of a diesel truck, R-32 dehumidifiers instead of R-410A units, cellulose insulation instead of fiberglass during reconstruction — the emission difference is an avoidance claim, provided the counterfactual (what would otherwise have been used) is documented and defensible.
Calculation methodology: Document the actual equipment or material used and its emission factor. Document the standard counterfactual (e.g., diesel equivalent, standard drywall, fiberglass insulation). Calculate the emission factor difference and multiply by the activity quantity. This is the avoided emission attributable to the substitution decision.
Important boundary condition: Category C avoidance claims require that the counterfactual is a realistic alternative — not an implausible worst case. Using “diesel heavy truck” as the counterfactual for a small cargo van trip, or “virgin nylon carpet” as the counterfactual when the client specified recycled carpet, overstates avoidance and will not survive audit scrutiny. The counterfactual should be the standard industry practice for that task, not the worst possible option.
How to Structure an Avoided Emissions Disclosure
How to structure an avoided emissions disclosure.
Avoided emissions should be reported as a supplementary section of the RCP Job Carbon Report, clearly separated from the actual emissions inventory. The structure prevents confusion in client ESG reporting — actual emissions go into their Scope 3 inventory; avoided emissions go into their Scope 3 narrative as evidence of supplier reduction activity.
Recommended disclosure format within an RCP Job Carbon Report:
"avoided_emissions": {
  "total_avoided_tco2e": 0.267,
  "avoidance_actions": [
    {
      "action_type": "dry_in_place",
      "description": "400 sq ft wall assembly dried in place — demolition avoided",
      "counterfactual_tco2e": 0.127,
      "actual_tco2e": 0.000,
      "avoided_tco2e": 0.127,
      "documentation": "psychrometric log confirming dry standard achieved, no demolition performed"
    },
    {
      "action_type": "waste_diversion",
      "description": "0.91 tons gypsum drywall diverted to regional gypsum recycler",
      "counterfactual_tco2e": 0.146,
      "actual_tco2e": 0.018,
      "avoided_tco2e": 0.128,
      "documentation": "recycling facility weight receipt #REC-2026-04847",
      "recycler_name": "National Gypsum Recycling, Portland OR"
    },
    {
      "action_type": "low_emission_vehicle",
      "description": "Electric monitoring van used for 3 monitoring visits (84 miles total) — diesel counterfactual",
      "counterfactual_tco2e": 0.042,
      "actual_tco2e": 0.013,
      "avoided_tco2e": 0.029,
      "documentation": "GPS trip log, vehicle: 2026 Ford E-Transit, charging location WECC subregion"
    }
  ],
  "methodology_note": "Counterfactuals based on standard RCP proxy values for the applicable job type. Avoidance calculations follow GHG Protocol guidance on avoided emissions disclosure as supplementary information, distinct from the Scope 3 inventory.",
  "audit_note": "Avoided emissions are supplementary disclosures and do not reduce the reported actual emissions total. They are not offsets and should not be subtracted from the client Scope 3 inventory."
}
What Avoided Emissions Are Not
Avoided emissions in the RCP framework are supplementary disclosures, not inventory adjustments. Three critical distinctions:
They do not reduce the reported actual emissions total. The Scope 3 inventory reports what happened. Avoided emissions report what didn’t happen because of a deliberate choice. A client cannot subtract avoided emissions from their Scope 3 total — that would be double-counting avoidance as a reduction. The GHG Protocol treats avoided emissions as supplementary information outside the inventory boundary, and RCP follows this treatment.
They are not carbon offsets. Offsets are purchased credits representing reductions achieved elsewhere. Avoided emissions are reductions achieved on the specific job being reported. A contractor cannot sell avoided emissions credits, trade them, or use them to offset other emissions unless they go through a formal carbon credit verification process, which is a separate and complex undertaking outside the RCP framework.
They require documentation at the same standard as actual emissions. An avoided emissions claim with no supporting documentation is worthless for ESG reporting and creates liability under FTC Green Guides for any contractor who markets it. Every avoided emissions entry in an RCP Job Carbon Report needs a source document: a recycling facility weight receipt, a GPS trip log, a psychrometric log, a materials delivery receipt. The same audit trail required for actual emissions is required for avoidance claims.
The Commercial Property Manager Perspective
When a property manager with a GRESB or SBTi commitment receives an RCP Job Carbon Report that includes an avoided emissions summary, they receive something most of their restoration vendors cannot provide: evidence that their contractor is actively contributing to their Scope 3 reduction trajectory, not just generating a number.
The practical use cases for property managers:
Annual sustainability report narrative: “In 2026, our restoration contractor network documented 47.3 tCO₂e of avoided emissions through waste diversion and dry-in-place techniques across 83 commercial property claims.”
SBTi supplier engagement evidence: Documented avoidance demonstrates that the contractor is taking action aligned with the client’s science-based targets, satisfying supplier engagement target requirements.
GRESB Management Component: Evidence of contractor sustainability practices supports management component indicators on supply chain engagement and vendor ESG requirements.
RCP v1.1 Roadmap: Formal Avoidance Framework
RCP v1.0 establishes the measurement standard. The avoided emissions framework described in this article is RCP guidance, not yet a formal v1.0 schema element. The following items are targeted for formalization in RCP v1.1:
JSON schema extension: avoided_emissions object with required fields for action_type, counterfactual_tco2e, actual_tco2e, avoided_tco2e, and documentation reference
Standardized counterfactual table: default counterfactual values for each of the three avoidance categories, analogous to the RCP proxy value table for actual emissions
Dry-in-place protocol: specific documentation requirements for Category A claims, including psychrometric log format, dry standard reference (IICRC S500), and affected area measurement methodology
Certified recycler registry: integration with a verified recycler directory (analogous to EcoClaim’s recycler directory) so that weight receipts from listed facilities carry a higher data quality designation than receipts from unlisted facilities
Portfolio avoidance summary: annual summary format that aggregates per-job avoided emissions across a client’s property portfolio, suitable for GRESB and SBTi supplier engagement reporting
Contractors who want to begin documenting avoided emissions now can use the JSON structure and methodology described above. Records generated under this guidance will be compatible with the v1.1 formal schema.
If you are generating avoided emissions data and would like to contribute to the v1.1 methodology development, contact rcp@tygartmedia.com. Primary data on actual avoidance outcomes — tons of drywall recycled, square footage successfully dried in place — is exactly what the RCP needs to build defensible proxy counterfactual tables for the next version.
Sources and References
GHG Protocol. Corporate Value Chain (Scope 3) Accounting and Reporting Standard, Chapter 9: Avoided Emissions. ghgprotocol.org/scope-3-standard
EPA WARM v16. Waste Reduction Model Documentation. epa.gov/warm
ICE Database v3.0. University of Bath / Circular Ecology. Embodied carbon factors for gypsum, lumber, metals.
Third-party verification of Scope 3 emissions data is no longer theoretical. California SB 253 requires limited assurance for Scope 3 emissions beginning in 2030. CSRD requires limited assurance for all emissions including Scope 3 from the date of initial reporting. GRESB added GHG data assurance as a newly scored metric in 2025. The direction of travel is clear: the per-job carbon data restoration contractors deliver to commercial clients will eventually be subject to external verification — not as a direct requirement on the contractor, but because the client’s verifier will examine the quality and traceability of the supplier data the client used to build their Scope 3 inventory.
This guide explains what verifiers actually look for in Scope 3 contractor data, how the RCP framework satisfies those requirements by design, and what documentation you need to retain to be audit-ready when your clients’ verifiers come asking.
The Two Levels of Assurance and What They Mean for Contractor Data
Two levels of assurance for contractor Scope 3 data.
Understanding assurance levels prevents confusion about what is actually being asked of you.
Limited assurance is a negative assurance — the verifier is confirming they found nothing that makes the report materially wrong. It involves reviewing methodologies, sampling data points, and checking for internal consistency. For Scope 3 data from restoration contractors, a limited assurance engagement will typically review: whether the methodology is documented and consistent with the GHG Protocol, whether proxy values are sourced and labeled, and whether the total reported figure is internally consistent with the underlying calculation inputs.
Reasonable assurance is a positive assurance — the verifier actively confirms the data is accurate. It involves re-performing calculations from source documents, testing internal controls, and in some sectors, site visits. For Scope 3 contractor data under reasonable assurance, verifiers will request the underlying source documents — GPS trip logs, waste manifests, purchase receipts — and verify that the calculation produces the reported number from those inputs.
The practical implication: for limited assurance, methodology documentation and labeling of proxy data are sufficient. For reasonable assurance, you need the source documents. The RCP 12-point data capture standard is designed to collect exactly those source documents at the time of the job, making reasonable assurance retroactively possible without extra effort.
The GHG Protocol’s Five Audit Principles — Applied to RCP Records
The GHG Protocol Corporate Value Chain Standard specifies five principles that a Scope 3 inventory — and by extension, the contractor data that feeds it — must satisfy for assurance purposes. Understanding how RCP records satisfy each principle makes audit preparation straightforward.
1. Relevance
What verifiers check: Whether the emissions sources included reflect the actual emissions generated on behalf of the client, and whether any exclusions are documented and justified.
How RCP satisfies this: The scope boundary section of the RCP Full Framework Document explicitly lists what is included and excluded, with justification for each exclusion. The job_type and damage_category fields in the RCP JSON schema ensure the correct emission domains are applied for each job type. No RCP-compliant record silently excludes a material emission source — exclusions must be documented in the data_quality.notes field.
2. Completeness
What verifiers check: Whether all material Scope 3 categories are covered and whether the reporting boundary is consistently applied across all jobs in the portfolio.
How RCP satisfies this: The RCP portfolio summary covers all jobs at a client’s properties during the reporting period. The four GHG Protocol categories covered (Cat. 1, 4, 5, 12) are documented in the framework as the complete set of material categories for restoration work. A verifier can confirm completeness by checking that every invoiced job appears in the portfolio summary.
3. Consistency
What verifiers check: Whether the same methodology and emission factors are applied across all jobs, and whether year-over-year comparisons are valid.
How RCP satisfies this: The schema_version field (“RCP-JCR-1.0”) ensures every record uses the same schema. The emission factor vintage is documented in the framework (“EPA 2025 EF Hub, EPA eGRID 2023, EPA WARM v16”). When CARB or EPA updates emission factors, the RCP patch version increments, creating a clear record of when methodology changed. Verifiers can request the emission factor table used and verify it matches the published RCP version for that reporting year.
4. Transparency
What verifiers check: Whether methodology is fully disclosed, proxy values are labeled, and the calculation can be reproduced from the disclosed inputs and factors.
How RCP satisfies this: The data_quality section of every RCP Job Carbon Report explicitly lists which data points are primary and which are proxy-estimated. The calculation_method field in each domain section identifies whether primary or proxy methodology was used. The emission factors are published in the RCP Emission Factor Reference Table with source citations. A verifier provided with an RCP JSON record, the proxy value table, and the raw source documents can reproduce the reported number independently.
5. Accuracy
What verifiers check: Whether the quantification is systematic, consistent, and not materially biased toward over- or under-reporting.
How RCP satisfies this: The proxy value hierarchy (primary > derived primary > job-specific proxy > national average proxy) ensures that the calculation uses the most accurate available data for each input. The data_quality section’s primary_data_points list lets verifiers assess what fraction of the total is based on primary data. The systematic use of EPA-sourced emission factors — not custom or proprietary factors — provides a defensible, auditor-recognized basis for every number.
What Source Documents to Retain and for How Long
What source documents to retain — and for how long.
The following source documents underpin each of the 12 RCP data points. Retain these at the job level, linked to the job ID, for a minimum of seven years. This covers the typical verification lookback period under CSRD (5 years) plus margin.
Data Point
Source Document to Retain
Assurance Level Required
1 — Vehicle log
GPS trip export or odometer log with vehicle ID, date, start/end location, miles
Reasonable assurance
2 — Waste transport
Disposal facility weight receipt or manifest with facility name, date, weight, material type
Reasonable assurance
3 — Equipment power source
Job notes confirming building power or generator fuel purchase receipt
Limited assurance
4 — Chemical treatments
Purchase order or supply requisition for chemicals used on this job, with quantities
Limited assurance
5 — PPE consumption
Supply order by job or proxy rate table reference if job-specific data unavailable
Limited assurance (proxy acceptable)
6 — Containment materials
Close-out notes with quantities or proxy rate table reference
Limited assurance (proxy acceptable)
7 — Debris volume
Disposal facility weight receipt (see Data Point 2) or dumpster manifest
Reasonable assurance
8 — Disposal method/facility
Disposal facility receipt naming the facility and disposal method
Reasonable assurance
9 — Demolished materials
Demolition scope from job file (Xactimate estimate or written scope), photo documentation
Reasonable assurance
10 — Replacement materials
Purchase orders or materials delivery receipts with quantities
Reasonable assurance (if in scope)
11 — Job classification
Initial assessment documentation with damage category, class, and affected area
Limited assurance
12 — Job timeline
Job management system record with start and completion dates
Limited assurance
How RCP Records Are Treated by Verifiers Under Limited vs. Reasonable Assurance
When a property manager’s verifier reviews their Scope 3 inventory under limited assurance, they will typically sample a subset of vendor records — often 10–20% of the total by value — and check for: consistency with stated methodology, that proxy records are labeled as such, and that the calculation produces a plausible number given the stated activity. An RCP JSON record satisfies all three checks without additional preparation, because the schema enforces methodology documentation, proxy labeling is required in the data_quality section, and the calculation is transparent and reproducible.
Under reasonable assurance, the verifier may specifically request source documents for the sampled records. This is where the seven-year document retention requirement becomes material. A contractor who can produce the disposal facility receipt, the GPS trip log, and the Xactimate estimate for a job from 18 months ago has converted a potential audit finding into a zero-question pass.
The most common Scope 3 audit finding for contractor data is: proxy data used without documentation of why primary data was unavailable. The RCP data_quality.notes field is specifically designed to prevent this. Every proxy-based data point should have a note explaining why primary data was unavailable: “Vehicle mileage estimated from dispatch records — GPS fleet system not yet deployed” is a valid and audit-acceptable explanation. Silence is not.
The Chain of Custody for RCP Data
The chain of custody for RCP data.
Verifiers are increasingly attentive to the chain of custody for supplier data — how data traveled from the source activity to the reported number in the client’s inventory. For RCP records, the chain of custody is:
Data entry: Job management system (Encircle, PSA, Dash, manual log)
RCP calculation: Activity data × emission factor = kg CO₂e per domain
RCP Job Carbon Report: JSON record with emissions summary and data quality metadata
Client delivery: Email, ESG platform upload, or API transmission
Client inventory: Aggregate Scope 3 figure in GRESB/CDP/SB 253 disclosure
Each link in this chain should be documentable. When a verifier asks “how did this number get into the inventory?” you should be able to walk from step 1 to step 7 for any sampled job.
Conducting Your Own Pre-Audit Review
Before your clients face their first verified Scope 3 disclosure cycle, run a pre-audit review of your own RCP records. The GHG Protocol explicitly recommends that inventory preparers treat each verification cycle as a learning process. For restoration contractors, a practical pre-audit review involves:
Pull the portfolio summary for your largest commercial client for the most recent year. Count the total jobs and total tCO₂e reported.
Sample 5 jobs — pick 2 large, 2 medium, 1 small by affected area. For each, verify you can locate all 12 data point source documents.
Check proxy labeling. For every job where a proxy was used, confirm the data_quality section identifies the proxy data points and the notes field explains why.
Reproduce one calculation. Take one job record and manually calculate the emissions from the source documents. Verify it matches the reported total within rounding.
Check version consistency. Verify all records in the portfolio used schema_version “RCP-JCR-1.0” and the same emission factor vintage. Mixed vintages require disclosure.
Document your findings. A one-page internal review memo noting what you checked and what you found creates a quality control record that verifiers view favorably as evidence of internal controls.
The Version Control Requirement
If a Job Carbon Report is corrected after delivery — because a waste manifest weight was updated, a vehicle mileage was corrected, or a proxy value was replaced with primary data — the corrected record must be issued as a new version. The version increment convention for RCP Job Carbon Reports is appending a revision suffix to the job ID: JOB-2026-04847-R1, JOB-2026-04847-R2, etc. The data_quality.notes field must document what changed and why. The original record should be retained alongside the revision — verifiers may ask why a record was corrected.
Assurance Standards Your Clients’ Verifiers Will Use
Different verifiers use different professional standards for GHG assurance. The most common frameworks your clients’ verifiers will reference:
ISAE 3000: The International Standard on Assurance Engagements (Revised) — the dominant framework for GHG assurance in the EU and used by the Big Four accounting firms globally
ISO 14064-3: Specification with guidance for the validation and verification of GHG statements — widely used in the US and internationally
AA1000AS: AccountAbility Assurance Standard — common in voluntary sustainability reporting contexts
CSAE 3410: Canadian standard, referenced by SB 253 as an acceptable framework
None of these standards create requirements that a contractor must meet directly — they govern how the verifier conducts the engagement. But understanding them helps you know what questions to expect if a client’s verifier contacts you directly about sampled records.
The EU Corporate Sustainability Reporting Directive (CSRD) is already in effect for large EU companies and is progressively expanding to cover more organizations through 2026. For US-based restoration contractors, CSRD becomes relevant not because they fall under the directive themselves — they almost certainly don’t — but because their clients might. If your commercial property clients include EU-listed entities, US subsidiaries of EU parent companies, or US real estate funds with EU institutional investors who are themselves CSRD-obligated, the data quality standard they need from you is different from and more demanding than GRESB or California SB 253 alone.
What CSRD Is and Who It Covers
What CSRD is and who it covers.
The CSRD requires companies to report on their environmental, social, and governance impacts under European Sustainability Reporting Standards (ESRS). It applies to large EU-based companies (those with over 250 employees, €40M revenue, or €20M balance sheet), all companies listed on EU-regulated markets regardless of size, and — importantly — non-EU companies with substantial EU operations or revenues above €150M within the EU.
The EU implementation timeline: Large companies already subject to the Non-Financial Reporting Directive (NFRD) began reporting under CSRD in 2024 for their 2023 data. Large companies not previously subject to NFRD report from 2025 (for 2024 data). Listed SMEs and certain financial institutions follow from 2026.
In February 2025, the European Commission adopted an Omnibus package proposing to limit mandatory CSRD reporting to companies with more than 1,000 employees, reducing the number of companies in scope. This proposal is moving through the EU Parliament and Council. Until formally adopted, the existing CSRD obligations remain in force.
The Double Materiality Concept and Why It Matters for Contractors
The double materiality concept for contractors.
CSRD introduces the concept of double materiality — companies must assess both how their activities impact climate and society (impact materiality) and how climate and social factors affect their business financially (financial materiality). This is a more demanding standard than the financial-only materiality used by US frameworks.
For restoration contractors serving CSRD-obligated property clients, double materiality means the client must assess not just the financial risk of the contractor’s emissions to the property portfolio, but also the actual environmental impact of restoration work on climate systems. This makes the per-job emissions calculation — not just a portfolio-level estimate — more important in the CSRD context.
ESRS E1: The Specific Standard Where Restoration Contractor Data Is Used
European Sustainability Reporting Standard E1 (Climate Change) is the ESRS standard that governs GHG emissions reporting under CSRD. ESRS E1 requires companies to disclose:
Gross Scope 1, 2, and 3 GHG emissions in metric tons CO₂e
Total GHG emissions (Scope 1 + 2 + 3)
GHG intensity metrics
Disclosure of significant Scope 3 categories and the methodology used to calculate them
The percentage of Scope 3 emissions calculated using primary data vs. spend-based or other estimation approaches
That last point — the percentage of Scope 3 calculated using primary data — is where RCP creates direct value for CSRD-reporting clients. ESRS E1 explicitly rewards primary data quality. A client that can say “67% of our Scope 3 Category 1 emissions from restoration contractors are calculated from primary job-level data using a standardized methodology” is in a materially better ESRS E1 position than one relying on spend-based estimates.
How to Identify Whether Your Client Has CSRD Exposure
Signs that a commercial property client may have CSRD obligations or exposure:
They are a US subsidiary of a European parent company — the EU parent’s CSRD reporting will include the US subsidiary’s supply chain emissions
They are a US REIT or property fund with EU institutional limited partners — the EU LPs may be CSRD-obligated and require portfolio-level supply chain data from their investments
Their annual sustainability report references CSRD, ESRS, double materiality, or EU taxonomy compliance
They are a multinational with EU revenues above €150M — potentially directly in scope for CSRD’s non-EU company provisions
Their ESG team has asked for supplier Scope 3 data with methodology disclosure (a common CSRD data collection pattern)
What CSRD-Obligated Clients Need from RCP Records
What CSRD-obligated clients need from RCP records.
For a CSRD-reporting client, the RCP Job Carbon Report provides the following ESRS E1 inputs:
GHG emissions by Scope 3 category: The emissions_summary section maps directly to ESRS E1 Scope 3 category disclosure
Primary data percentage disclosure: The data_quality section’s primary_data_points list enables the client to calculate what percentage of your reported emissions are primary-data-backed
Methodology disclosure: The reporting_standard field (“Restoration Carbon Protocol v1.0, GHG Protocol Corporate Value Chain Standard”) provides the methodology reference ESRS E1 requires
Emission factor vintage: ESRS E1 requires disclosure of the emission factors used. RCP’s emission factor reference table provides this with source citations
One important difference for CSRD vs. GRESB: ESRS E1 requires gross emissions, not net. Do not apply any offset or renewable energy credit adjustments to RCP records delivered to CSRD-reporting clients. Deliver the gross calculation only.
The Practical Implication: Methodology Documentation Matters More
For SB 253 or GRESB, a well-structured number with a plausible methodology is generally acceptable. For CSRD, the methodology disclosure itself is a reporting requirement — auditors will examine whether the stated methodology is credible and consistently applied. The RCP framework’s explicit source citations for every emission factor, its defined proxy hierarchy, and the data_quality section of the Job Carbon Report are not administrative overhead — they are the audit trail that CSRD-reporting clients need.
If you serve clients with CSRD exposure, ensure that every RCP Job Carbon Report delivered to them is fully populated through the data_quality section, with primary vs. proxy data points explicitly flagged and any unusual circumstances noted in the free-text notes field.
Sources and References
European Commission. Corporate Sustainability Reporting Directive (CSRD). eur-lex.europa.eu
European Financial Reporting Advisory Group (EFRAG). ESRS E1 — Climate Change. efrag.org
European Commission. Omnibus Package — Proposed CSRD Amendments. February 2025.