Tag: Restoration Industry

  • Restoration Company Valuation: 2026 Multiples & PE Buyers

    Restoration Company Valuation: 2026 Multiples & PE Buyers

    If you own a restoration company today, you are sitting on the most attractive asset class in the home services sector — and the buyers know it. Private equity has deployed more than $6 billion across 50+ restoration platforms since 2018, and the consolidation wave that started with brands like ServiceMaster and BELFOR is now grinding through the middle market. Regional operators doing $5M to $25M in revenue are getting unsolicited LOIs every quarter. Most owners have no idea what their business is actually worth, what they could be doing right now to add a turn or two to their multiple, or which buyer in the market is the right exit for their specific situation.

    This is the bottom-line guide. No fluff. What buyers pay, what they discount for, and what to fix before the call.

    What restoration companies are actually selling for in 2026

    Valuation in restoration is driven by size, revenue mix, and operating quality — in roughly that order. The brackets break down like this:

    • Owner-operator shops ($500K–$2M revenue, $150K–$400K SDE): 2.3x–3.5x SDE. These are individual-buyer or local-strategic deals. The owner is the business; the buyer is essentially buying a job with a customer list.
    • Established multi-tech operations ($2M–$10M revenue, $400K–$1.5M EBITDA): 3.5x–5.5x EBITDA. This is where most PE add-on activity happens. Buyer expects you to be transferable.
    • Multi-location regional platforms ($10M–$50M revenue, $1.5M–$5M EBITDA): 5.5x–8.0x EBITDA. Now you are platform-grade. TPA program participation, named carrier relationships, and 24/7 infrastructure matter heavily here.
    • Premium platforms ($12M+ EBITDA, multi-state, modern operating system): 7x–11x+ EBITDA. This is the HighGround-to-Knox-Lane tier. Rare air, but it exists.

    To translate: a $1M SDE owner-operator is looking at roughly $2.8M–$3M at sale. A $3M EBITDA regional with a clean TPA book and a working second-in-command is looking at $18M–$24M. The gap between those two numbers is mostly operational discipline, not revenue.

    The buyers actually writing checks right now
    Three buyer types: strategic PE, regional roll-ups, operator buyers
    Know who is writing checks before you polish the teaser.

    The named platforms most active in restoration add-ons through 2025 and into 2026 include:

    • Morgan Stanley Capital Partners (American Restoration): An 8-brand roll-up across 10 states, headquartered in Dallas. Acquired by MSCP after building out residential and commercial mitigation in regional markets. Looking for tuck-ins that fit the regional brand model.
    • Knox Lane (HighGround): 13 acquisitions in 5 years before exit. Aggressive on multiples for the right strategic geography.
    • LP First Capital / Align Collaborate (Rewind Restoration): Newer platform, launched with the Icon Restoration acquisition in Rochester Hills, Michigan. Stated goal of building one of the largest residential restoration businesses in the US — meaning they are at the early, hungry stage of a platform.
    • Osceola Capital (Fortify Restoration): Platform launched mid-2025. First add-on was Beach Contracting in South Florida. Focused on structural restoration and southeast geography.
    • Crossplane Capital (Mooring USA): Dallas-based PE shop that took Mooring private. Commercial-leaning thesis.

    None of these buyers want a vendor brochure. They want clean books, low owner dependence, and a story about how revenue keeps coming after closing.

    What buyers actually grade you on
    Six cards: repeatable jobs, clean books, bench depth, channel mix, owner optional, risk controls
    Buyers grade transferability — same scorecard as valuations.

    Pretend you are sitting in the LOI meeting. The questions on the buyer’s checklist, in order of how much they move the multiple:

    1. Revenue mix. Buyers want recurring service contracts, TPA program participation, and managed-repair work. They penalize reconstruction-heavy mix (lower gross margins) and they penalize catastrophe-heavy revenue. The savvy ones expect CAT work to represent no more than 15–20% of total revenue — anything north of that gets discounted as unpredictable.
    2. TPA and carrier relationships. A documented Contractor Connection, Alacrity, Code Blue, or PSA program book — with active job volume and clean compliance history — is worth real multiple turns. A regional platform with $4M–$12M EBITDA and a strong TPA book is the difference between a 6x deal and an 8x deal.
    3. Owner dependence. If you sign every estimate, talk to every adjuster, and make every hiring call, your business is not transferable. Most buyers want a turnkey, profitable operation, and creating SOPs that remove yourself from the daily grind is the single highest-ROI thing you can do in the 18 months before a sale.
    4. Financial cleanliness. Multiples above the median require demonstrably above-median EBITDA margin and clean financial documentation that survives a third-party Quality of Earnings review. If your bookkeeper is your spouse and your books are on QuickBooks with no monthly close, you will get repriced in due diligence.
    5. Management depth. A strong GM, an operations lead, and a finance person who isn’t you. Buyers will request to meet key employees during due diligence and may want to adjust transition terms based on who is staying.

    The things that quietly destroy your multiple
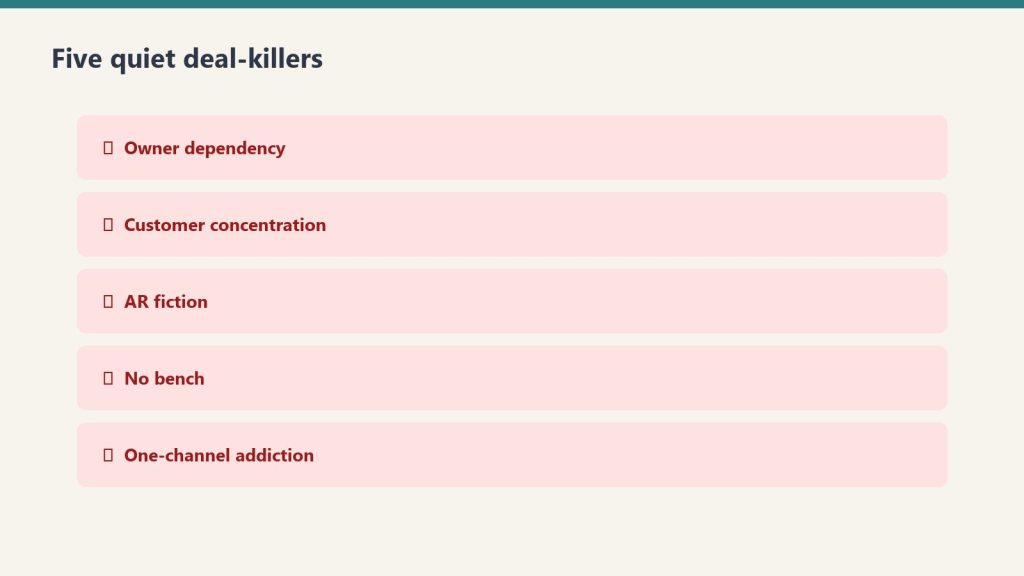
    Red list of deal killers including owner dependency and messy AR
    Quiet destroyers of multiple look a lot like deal killers.

    Sellers walk into deals not knowing these compress them by 1–2 turns:

    • Reconstruction-heavy revenue mix with low gross margin.
    • No TPA program participation — meaning revenue is fully dependent on local marketing and referrals.
    • Weak 24/7 response infrastructure (no real on-call rotation, no after-hours dispatch).
    • Paper-based or hybrid workflow with no modern job management system.
    • Single-territory exposure with no expansion playbook.
    • Lapsed or thin IICRC certifications across the technician base.
    • Concentration risk — one TPA or one big carrier representing more than 25% of revenue.

    The timeline that wrecks sellers

    Due diligence typically runs 30 to 90 days and is the most intensive phase of any restoration sale. Owners who go into LOI without having done their own internal QoE, their own SOP documentation, and their own legal cleanup almost always get retraded. Sometimes the retrade is mild — $200K off the headline number. Sometimes the buyer walks. The sellers who hold their price are the ones who showed up ready: trailing twelve-month EBITDA reconciled monthly, contracts organized, employee agreements in place, tax returns matching financials, and a clean cap table.

    Most restoration deals take six to twelve months from first conversation to close. If you are thinking about an exit in 2027, the time to start is now.

    The honest bottom line

    If you are under $2M in revenue, an owner-operator, and reconstruction-heavy: your real exit number is probably $400K–$800K, not the $2M figure you’ve been telling yourself. Sell to a local strategic, take three years of earn-out, and get to your number that way.

    If you are $3M–$10M with a working TPA book and a real management bench: you are exactly what every active PE platform is shopping for. Get a Quality of Earnings done now, fix the obvious holes, and start taking the calls. There are a dozen named buyers with active mandates, and the market for quality regional restoration assets is the strongest it has ever been.

    If you are $12M+ EBITDA with multi-state coverage and a modern operating system: you are not selling a business, you are negotiating a platform price. Hire a sell-side advisor who has actually closed restoration deals — not a generalist broker. The difference between a competitive process and a one-buyer conversation is two turns of EBITDA, which on your numbers is real money.

    The window for premium restoration exits is open. It will not stay open forever. Climate-driven loss frequency is up roughly 35% since the 1990s, which is fueling buyer enthusiasm — but interest rates and PE fundraising cycles will eventually cool the market. Sellers who prepare now will catch this wave. Sellers who wait for “the right time” will sell into a softer market.

    The right time is when your business is ready, not when the market is hot. The good news is the market is hot and the operational work to be ready is straightforward. Get started.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
  • Xactimate Supplement Audit: 7 Missed Water Mitigation Items

    Xactimate Supplement Audit: 7 Missed Water Mitigation Items

    Most water mitigation supplements get killed not because the work wasn’t done, but because the line items were never written down. If you’re running a restoration company and watching your margin bleed out on Category 2 and Category 3 jobs, there is a near-certainty that your initial Xactimate sketch is missing four to seven line items that your crews actually performed. The desk adjuster never saw them. So they never approved them. And your gross margin took the hit.

    This is the Xactimate supplement audit your estimator probably isn’t running. Walk through it before you submit your next water loss, and then walk through it again before you accept a partial denial.

    Why supplements get killed

    Clipboard and tablet on a kitchen counter during an insurance adjuster walkthrough after water loss
    Supplements die when docs are late or vague.

    The honest reason most supplements come back partially approved or denied is that they arrive looking like an afterthought. A clean Xactimate file that uses the carrier’s current price list, includes photo documentation tied to each line item, and matches the scope to the loss category gets reviewed apples-to-apples. A supplement that arrives as a PDF list with no photos and no sketch revision gets reviewed as a request for more money. Those are two very different conversations.

    If you want approvals to move faster, every supplement needs three things: a revised sketch with new room tags or affected areas marked, photographs that directly correspond to each added line item, and pricing pulled from the same Xactimate price list the carrier is using. Verbal approvals over the phone do not create a paper trail. Email or carrier portal submissions do.

    The line items most crews actually perform but never bill

    Seven cards of commonly performed but unbilled mitigation items
    Crews do the work — the estimate has to say so.

    These are the WTR category items that show up in real water loss workflows and get left off the initial estimate. None of these are exotic. All of them are billable when the work was performed and documented.

    Equipment decontamination on Category 3 losses. Every air mover, dehu, HEPA, and hose that entered a Category 3 environment requires decontamination before the next job. This is a line item, not a cost of doing business absorbed by your overhead. If your crew is bagging hoses and wiping down equipment with a quaternary cleaner, that is a billable task.

    Antimicrobial application to affected surfaces. Plant-based or quaternary antimicrobial application on framing, subfloor, and the bottom plates is a separate line item from the cleaning. On Category 2 and Category 3 work the IICRC S500 protocol calls for antimicrobial treatment of affected materials. If you applied it, bill for it.

    Containment and drying chamber setup. Plastic sheeting, zipper doors, and the labor to build a containment that isolates the drying chamber from unaffected areas is its own line item. The chamber itself is the reason your equipment count is justified — a smaller controlled volume dries faster, runs fewer days, and uses fewer air movers than an open room. If the adjuster is questioning your equipment count, the containment line item is the answer.

    Detach and reset of contents. Moving the homeowner’s furniture, boxing contents, blocking the legs of upholstered pieces, and putting it back at the end of the job is not free. Contents manipulation has its own line items in Xactimate and is one of the most consistently missed billable activities in mitigation work.

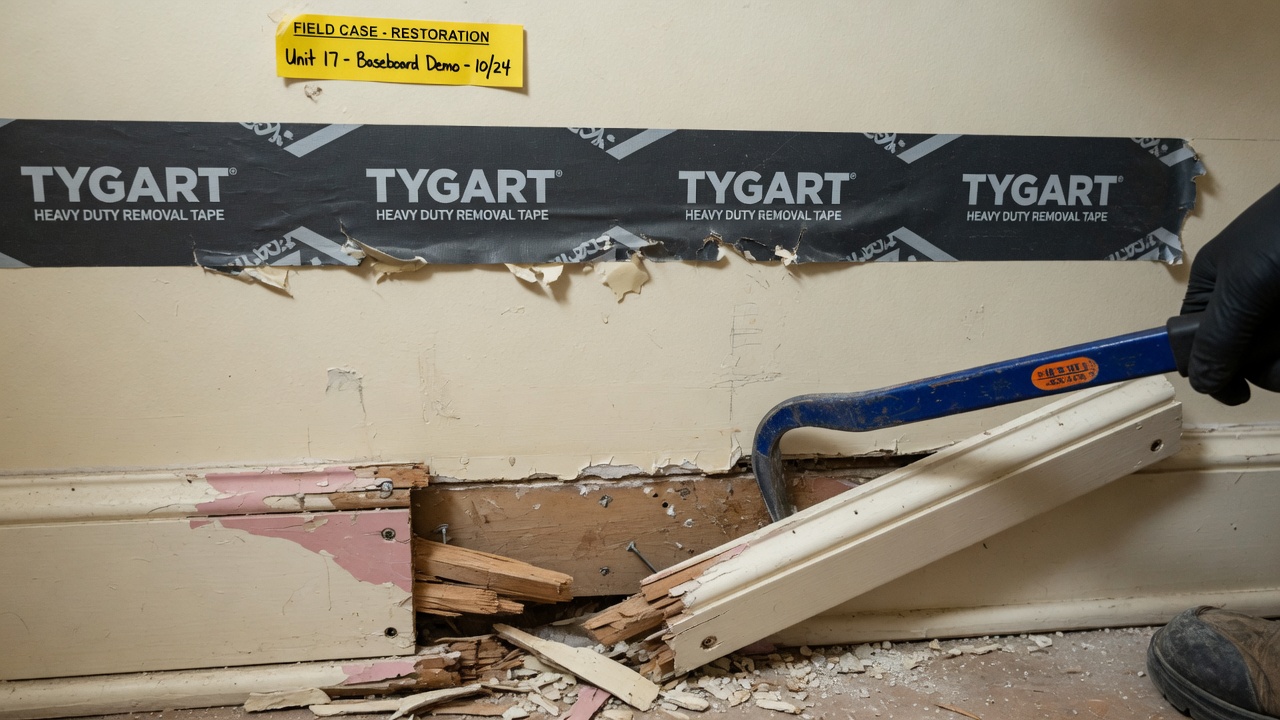
    Multi-member baseboard removal. If the baseboard had quarter round or a separate cap, the WTRBASEB> line item covers the additional labor to remove and dispose of each layer. Estimators trained on the older single-member baseboard removal habitually leave the extra members off the estimate.

    HEPA vacuum of demolition area. After a flood cut and material removal on a Cat 2 or Cat 3 loss, HEPA vacuuming the cavity before reconstruction begins is a billable task. It is also a defensible task if the homeowner ever questions whether the area was properly cleaned.

    Disposal of contaminated water and materials. Extracting Category 3 water and disposing of it is different from extracting Category 1. There are separate line items for contaminated water extraction, contaminated material disposal, and the dump fees. If your crew hauled six contractor bags of sewage-soaked drywall to the landfill, that is documentable and billable.

    The documentation that makes a supplement get approved

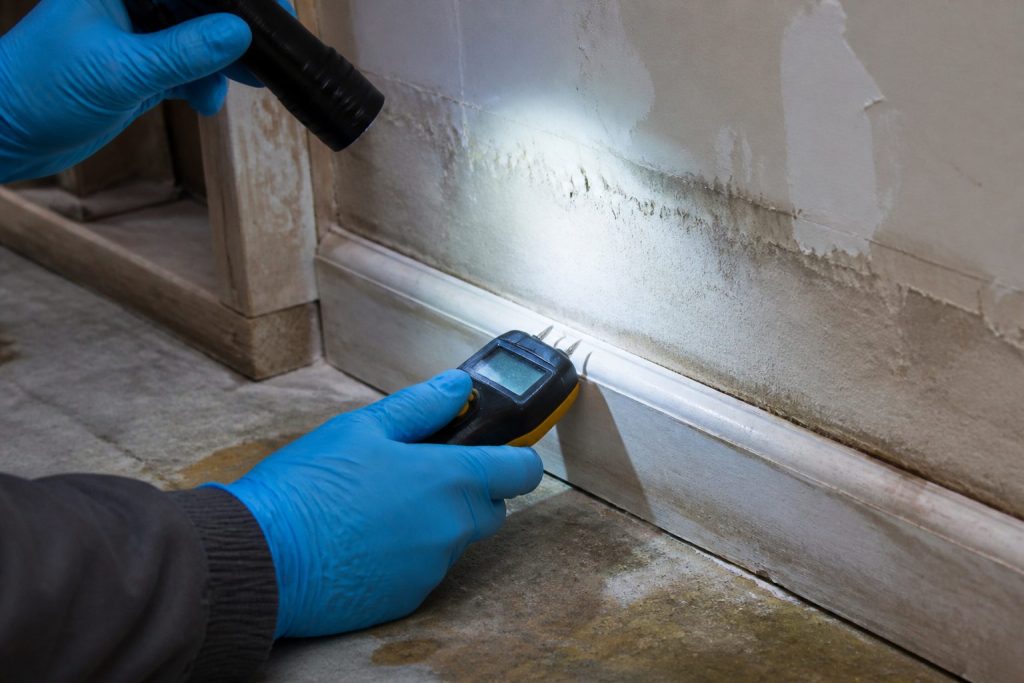
    Gloved hands using a pin-type moisture meter on wet drywall during inspection
    Moisture maps and photos make supplements get approved.

    Pricing arguments are losing arguments. Scope arguments are winning arguments. When you submit a supplement, do not lead with cost. Lead with scope, and let the Xactimate price list speak for itself.

    The fastest path to approval is to use Room ID tags in the Xactimate sketch so every space is clearly labeled, attach a photograph for every added line item that shows the affected area and condition, reference the loss category and IICRC standard where applicable, and submit the revised estimate as an attachment in the carrier portal rather than as a phone call or text.

    When a line item is denied, the response should not be a longer email. It should be a request for the specific reason for the denial, in writing, tied to the carrier’s policy language or pricing logic. Most contractors give up at the first denial. Most adjusters expect that. The ones who push back with documentation get a measurable percentage of denied items approved on second submission.

    The bottom line

    Restoration owners obsess over labor cost and equipment utilization, but the single biggest lever on water mitigation gross margin is the completeness of the initial Xactimate scope and the discipline of the supplement process. Every line item your crew performs that does not make it onto the estimate is pure margin loss — the cost was already incurred. Building a checklist of the seven items above and running it as a pre-submission audit on every Cat 2 and Cat 3 loss is a one-week implementation that will pay for itself on the first job.

    If your average water mitigation ticket is in the $4,000 to $6,000 range and a complete supplement audit recovers an additional $400 to $900 per job through previously uncaptured line items, the math at any meaningful job volume is the kind of margin recovery most owners spend years trying to find in payroll, fleet, or marketing instead.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
  • Restoration Company Expansion: Opening a Second Location

    Restoration Company Expansion: Opening a Second Location

    Every restoration owner who clears $5M in annual revenue eventually faces the same fork in the road: dominate the home market harder, or plant a flag in a second city. The wrong answer is not financially fatal — but it usually adds two or three years of expensive learning before the business starts compounding again. With private equity platforms now operating in 30+ states and the industry consolidating from roughly 15,000 firms toward fewer than 10,000 by 2030, that learning window is closing.

    This is the operator-level decision underneath the M&A headlines. Here is the honest framework for it.

    The PE backdrop you are competing against

    Before deciding whether to open a second location, understand what the buyers up the food chain are doing. Reported industry coverage in 2025 and 2026 shows over $6 billion has been deployed across roughly 50+ restoration platforms since 2018, with quality operators trading in the 4x–7x EBITDA range. Fortify Companies — backed by Osceola Capital — combined Rytech Restoration and Insurcomm to serve more than 100 markets across 30+ states. LP First Capital launched Rewind Restoration with an explicit “partner with local leaders, then scale via acquisitions” thesis. Morgan Stanley Capital Partners acquired American Restoration, which operates across approximately 10 states through eight regional brands.

    The pattern is the same in every deal: platforms are not opening locations. They are buying them. A platform spends 18 months building infrastructure, then acquires a $3M–$5M regional operator and bolts it on at a roughly 5x EBITDA multiple. If you are an owner expanding organically into a new market the slow way, you are competing for the same techs, the same referral relationships, and the same carrier slots against a buyer with cheaper capital and a centralized back office.

    That does not mean organic expansion is wrong. It does mean you need to be honest about why you are doing it and what the finish line looks like.

    The four real reasons owners open a second location (only two are good)

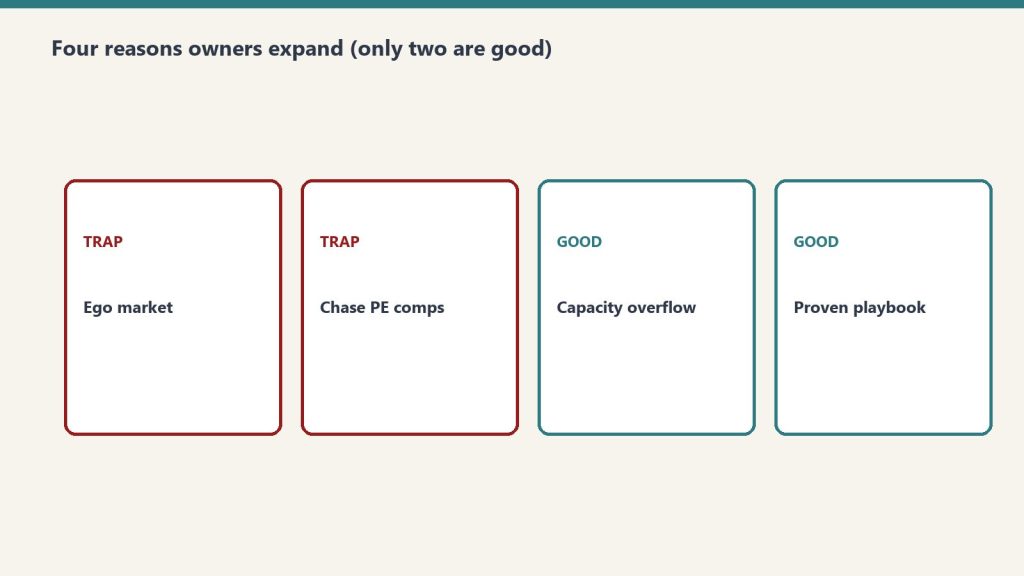
    Four cards marking ego and PE-chase as traps versus capacity and playbook as good reasons
    Only two of the four expansion reasons are good.

    In conversations across the industry, the rationales for a second location tend to cluster into four categories. Two of them tend to work. Two of them tend to bleed cash.

    1. The carrier asked for it. Strong reason. If you are on a Contractor Connection, Alacrity, or Code Blue program and your performance metrics in market A have earned you a request to cover market B, the demand is already there before you sign the lease. The carrier is effectively pre-funding your CAC. This is the cleanest second-location case in restoration.

    2. A key employee will leave if they do not get equity in something they can run. Reasonable reason. Promoting your best operations manager into a second-market GM role with a real P&L and a real equity slice is often cheaper than losing them to a competitor. The risk is that you are choosing the market for HR reasons, not market reasons. Mitigate it by making the GM put together a real go-to-market plan before you commit capital.

    3. The home market feels “tapped out.” Usually wrong. Industry coverage of restoration economics in 2026 — including reporting from Push Leads and Paul Davis — repeatedly notes that most owners who feel tapped out have actually capped their CAC channels, not their market. A second location does not solve a Google Ads ceiling, an LSA neglect problem, or a referral program that has gone stale. It just spreads the same problem over two cities.

    4. “It will be worth more at exit.” Almost always wrong on its own. Multi-location restoration platforms do command higher multiples, but the premium comes from diversified revenue and demonstrated systems — not from the existence of a second address. A second location that loses money for three years actively destroys exit value because it drags EBITDA and signals that the operator cannot run multi-site.

    The financial test before you sign the lease

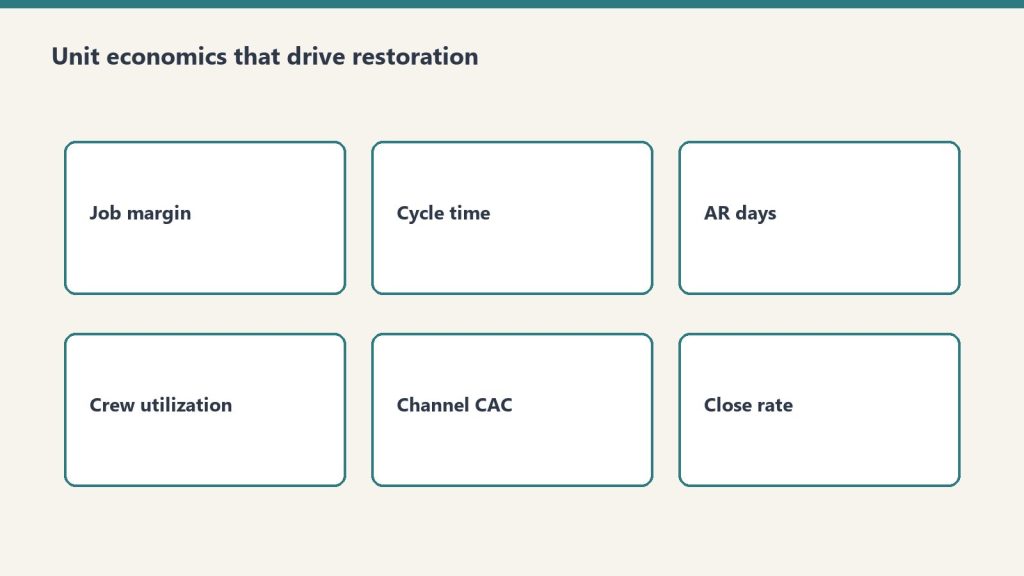
    Six cards covering job margin, cycle time, AR days, utilization, CAC, close rate
    Financial test before the lease — unit economics first.

    The math is unforgiving. Restoration industry reporting on unit economics generally points at the same benchmarks: water mitigation gross margins in the high 40s to mid 50s, blended company gross margins of roughly 38–45%, and net margins for healthy operators in the 8–15% range. Channel CAC tends to run roughly $100–$180 per acquired job on well-optimized Google Ads, $200–$400 on poorly run campaigns, and effectively the lowest CAC on agent and adjuster referrals.

    Run this test before committing:

    • Home market net margin must be at least 10% on a trailing-twelve-month basis. If it is not, you do not have a scalable model yet. Fix the unit economics in market A before duplicating them in market B.
    • You must have at least 6 months of fully loaded operating cash for the new market. A new market typically does not break even on operating cash for 12–18 months. Most “failed” second locations actually ran out of patience before they ran out of demand.
    • CAC in the new market should be modeled at 2x your home-market CAC for the first year. No agent relationships, no adjuster history, no organic search ranking. Plan for it, do not be surprised by it.
    • You must have a designated GM willing to live in the new market. Owner-commuter second locations have a documented bad track record across the industry. The job is too relationship-driven for absentee leadership.

    What the structure should look like in year one

    The second-location org chart that tends to survive is lean and asymmetric. The home market keeps centralized accounting, marketing, estimating support, and Xactimate review. The new market gets a GM, two to three production crews, one project manager, and a dedicated office coordinator. Sales and BD belong to the GM full time — this is non-negotiable because nothing else recovers if local referral relationships are not being built.

    Approximate revenue target in year one for a single new market: $1.2M–$2.0M, with a planned net loss in the first 6–9 months and a target of break-even monthly run-rate by month 12. If you cross break-even faster, the carrier-pre-funded scenario was real. If you are still bleeding past month 18, the most common honest answer is that the market choice was wrong — not that the team needs more time.

    Single-market dominance: the underrated alternative

    White restoration work van with ladder rack parked at a suburban jobsite curb
    Single-market dominance is often the underrated alternative.

    For a meaningful share of $3M–$8M restoration operators, the highest-return move is not a second location at all. It is doubling down on the existing market with a vertical-line expansion — adding contents cleaning, mold remediation, or reconstruction in-house — and grinding the home metro toward 6–10% market share.

    The math favors this more often than owners assume. A second service line in an existing market shares overhead, shares referral relationships, and adds revenue at a lower marginal CAC than any new geography can. A $5M single-market shop with diversified service lines and clean books frequently exits at a higher multiple than a $7M two-market shop with one money-losing location, because buyers price systems and predictability, not address count.

    The exit-aware framing

    If your 5-year plan is to sell to a PE platform or a strategic buyer, the question is not “how many locations do I have.” The question is “how cleanly does my next location bolt onto a buyer’s system.” That means:

    • Standard chart of accounts across locations from day one
    • One CRM and one estimating workflow across all sites
    • Documented SOPs for water, fire, mold, contents, and reconstruction
    • Carrier program enrollment at the parent entity level, not the location level
    • GMs on real comp plans with documented KPI scorecards

    If you cannot do those five things in your current single location, you are not ready for a second one. Buyers can tell within a single diligence meeting.

    The bottom line

    A second location is the right move when a carrier is pulling you into a new market, when you would otherwise lose a key operator, and when your home-market unit economics already produce 10%+ net margins and 6+ months of operating runway. It is the wrong move when it is a substitute for fixing CAC, when you are betting on multiple expansion alone, or when the GM does not actually live in the new city. Most owners would create more enterprise value by adding a service line in their existing market than by adding a city.

    The window matters. With platforms still buying regional operators at reported 4x–7x EBITDA multiples and the operator base aging into exit-readiness, the next 3–5 years is the time to either build a defensible multi-market platform or to be the kind of clean, single-market operator that those platforms want to acquire. Both are good outcomes. The bad outcome is being stuck in the middle — two locations, neither profitable, three years older.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
    Frequently Asked Questions

    When should a restoration company open a second location?

    When home-market net margins exceed 10% on a trailing-twelve-month basis, when you have 6+ months of fully loaded operating cash to fund the new market, and when either a carrier is requesting expansion or a key operator needs an equity-and-P&L opportunity to retain. Opening a second location to escape a CAC ceiling or to chase a higher exit multiple alone is generally a money-losing decision.

    How long does a second restoration location take to break even?

    Industry experience suggests 12–18 months to monthly operating break-even is normal for a new restoration market without a carrier program pre-funding the launch. With an active carrier program request, the timeline can compress materially. Owners should plan for a net loss in months 1–9 and budget cash accordingly.

    Is it better to add service lines or open a second location?

    For most restoration operators in the $3M–$8M range, adding service lines in the existing market — contents, mold, reconstruction — produces a higher marginal return on capital than geographic expansion, because overhead and referral relationships are already paid for. Geographic expansion makes more sense once a single market is diversified across service lines and approaching 6–10% local share.

    What multiple do multi-location restoration companies sell for?

    Industry reporting in 2026 generally cites a range of approximately 4x–7x EBITDA for quality restoration operators with diversified service lines, with sub-$2M shops trading closer to 2.8x–3.0x SDE. Location count alone does not drive the premium; diversified revenue, documented systems, clean financials, and demonstrated GM-led management at each site are what move the multiple.

  • Restoration Marketing Channels: LSA vs Google Ads vs SEO

    Restoration Marketing Channels: LSA vs Google Ads vs SEO

    If you own a restoration company in 2026, your marketing budget is being eaten alive by three channels fighting for the same lead: Google Local Services Ads, Google Search Ads, and SEO. The owners I talk to are spending six figures a year and still can’t tell me, with a straight face, which channel is actually paying them. So let’s settle this with the numbers vendors don’t put in their pitch decks.

    The water damage CPC is the most expensive in home services

    Reported cost-per-click for top water damage restoration keywords has climbed as high as the $200–$250 range in competitive metros, with industry sources citing top-of-page bids reaching around $250 per click for terms like “water damage restoration [city].” Average emergency restoration keywords more commonly land in the $40–$100 CPC range depending on geography and time of day. That is not a typo. A single click — not a lead, not a job — can cost more than most contractors charge for a furnace tune-up.

    The reason owners keep paying it is simple. A water mitigation job typically prices in the $3,000–$15,000+ range depending on category and scope. At those ticket sizes, a $300 cost-per-lead and a 25% close rate still pencils out. But “pencils out” is doing a lot of heavy lifting in that sentence — and that’s where most owners stop running the math.

    The three channels, ranked by what they actually do

    Three ranked panels: intent near need, catch overflow, compound trust
    Ranked by what they actually do — not vanity volume.

    Google Local Services Ads (LSA): the most consistent ROI lever right now

    LSA cost-per-lead in restoration is widely reported in the $80–$180 range for water damage, with mold remediation reported between roughly $60 and $250 depending on market. Conversion rates from lead to booked job tend to be reported around the 10–15% range — higher than standard Google Search Ads — because Google charges per qualified phone call or message, not per click.

    The bottom line on LSAs: if you do not have Google Guaranteed status set up and your service area dialed in, this is the first thing you fix this quarter. The catch nobody mentions: Google ended the credit policy for “job type not serviced” and “geo not serviced” disputes in 2025, meaning junk leads now come out of your pocket with no refund pathway. You have to dispute aggressively on the categories Google still credits, or your effective CPL drifts 15–25% higher than the platform number says it is.

    Google Search Ads (PPC): the channel you run when you have no other choice

    Average reported cost-per-lead for Google Search Ads in restoration falls in the $150–$400+ range, with the high end concentrated in metros with two or more national franchise advertisers bidding against you. Conversion from click to lead in well-managed accounts typically lands in the 5–10% range — half of what LSAs deliver.

    PPC has one thing LSAs don’t: control. You set the keywords, you set the geo, you set the ad copy, you decide whether you want commercial water damage leads or residential mold leads or fire restoration leads. If you are running a multi-location shop or chasing commercial work specifically, you cannot live on LSAs alone — the lead types are too restricted. But if you are a single-location residential operator, every dollar in PPC should be earning its keep against the LSA dollar, and most of the time it isn’t.

    SEO: the long-term asset everyone wants to own and almost nobody finishes building

    Cost-per-lead from established organic rankings is commonly reported in the $75–$150 range — roughly half the cost of paid channels at maturity. The trade-off is time. Restoration SEO in competitive metros typically takes 12–18 months of consistent investment before it produces meaningful lead flow, with initial signal in 3–6 months for low-competition local terms.

    The honest read: most restoration owners start SEO, get impatient at month four when paid channels are still doing all the work, and either fire the agency or stop publishing content. Then they restart 18 months later with a different vendor and the same outcome. SEO works. It works exactly the way the calendar says it will work. The companies that win with it are the ones who treat it like a 24-month commitment, not a 90-day experiment.

    What the channel mix should actually look like

    Three cards for LSA, search ads, and SEO/AI authority channels
    Channel mix should match capacity — not ego.

    For a residential-focused restoration company doing $1M–$5M in revenue, a defensible channel mix in 2026 looks something like this:

    • LSA: 35–45% of paid budget. Highest reported ROI of any paid channel in restoration. Cap is the daily lead volume Google will give you, not the budget.
    • Google Search Ads: 25–35% of paid budget. Covers the lead types LSAs cannot serve — commercial work, specific service lines, and overflow when LSAs hit daily caps. Required for any multi-location shop.
    • SEO and content: 20–30% of total marketing budget. Treat as 18–24 month asset build. Tracked separately from paid CPL because the unit economics only stabilize at month 12+.
    • Referrals and direct outreach: ongoing, no fixed budget. Reported industry-wide as the lowest-CAC channel and the one with the shortest break-even window. Build a plumber/agent/property manager referral program before you spend another dollar on paid ads.

    The split that gets restoration owners in trouble is putting 80% into paid and 20% into “we’ll get to it” SEO. Two years later they are completely dependent on Google’s auction prices, and the auction prices have gone up every year of the last five.

    The metric that actually matters

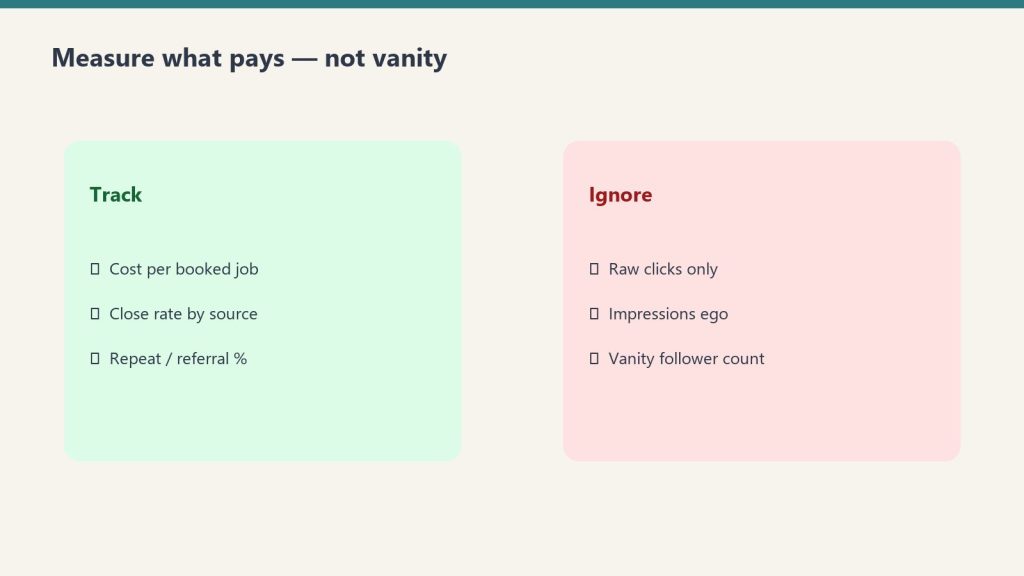
    Side-by-side of metrics to track versus vanity metrics to ignore
    The metric that matters is booked jobs, not clicks.

    Cost-per-lead is the metric every vendor reports. It is the wrong number to optimize for. The number that matters is fully-loaded cost-per-acquired-job, which is CPL divided by your channel-specific close rate, plus the labor cost of the CSR who fielded the call, plus the credit card processing on whatever portion of the job is paid out-of-pocket, minus the franchise or TPA fee if applicable.

    Most restoration owners do not have this number for any of their channels. They have CPL from the platform dashboards, they have revenue from the job management software, and the two systems have never talked to each other. Fix that before you change a single bid. The owner who knows their fully-loaded acquired-job cost by channel makes better decisions in five minutes than the owner who doesn’t makes in a quarter.

    The bottom line

    LSAs are the highest-ROI paid channel in restoration in 2026 and should be the first lever you optimize. Google Search Ads are required for any operator chasing commercial work or running multiple locations, but they should never be your largest line item. SEO is the long-term insurance policy against rising auction prices, and the only restoration owners who get the payoff are the ones who treat it like a 24-month commitment and refuse to flinch at month six.

    If you are spending more than $5,000 a month on Google Search Ads and you do not yet have LSAs set up, you are leaving the most profitable channel in restoration on the table. Start there.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
    Frequently Asked Questions

    What is the average cost per lead for water damage restoration in 2026?

    Reported cost-per-lead for water damage restoration in 2026 ranges from roughly $80–$180 on Google Local Services Ads, $150–$400+ on Google Search Ads, and $75–$150 from mature organic SEO. Actual costs vary significantly by metro, competition, and lead-type mix.

    Are Google Local Services Ads better than Google Ads for restoration?

    For most residential restoration operators, LSAs deliver a lower cost-per-lead and a higher reported lead-to-job conversion rate than standard Google Search Ads. LSAs charge per qualified call rather than per click, which is why the ROI tends to be more consistent. Multi-location shops and commercial-focused operators still need Google Search Ads to cover lead types LSAs do not serve.

    How long does SEO take to work for a restoration company?

    Restoration SEO in competitive metros typically takes 12–18 months of consistent investment before it produces meaningful lead flow. Initial ranking signal often appears in 3–6 months for low-competition local terms, but the cost-per-lead advantage versus paid channels only stabilizes after month 12.

    What percentage of a restoration marketing budget should go to paid ads?

    A common defensible split for a residential restoration company in 2026 is roughly 60–70% of total marketing budget on paid channels (LSA + Google Search Ads) and 20–30% on SEO and content, with referral programs running in parallel at minimal incremental cost. Going above 80% paid concentrates risk in the Google auction.

  • Restoration TPA Programs: Top Networks Compared in 2026

    Restoration TPA Programs: Top Networks Compared in 2026

    If you run a restoration company doing more than $2M a year, you’ve had the conversation. A friend in the business tells you their Contractor Connection volume just doubled. Your phone hasn’t rung in three days. You wonder if you should finally sign the paperwork.

    Before you do, sit with the math. TPA programs are not free leads — they are the most expensive leads in restoration, paid with margin instead of marketing dollars. The question isn’t whether TPAs are good or bad. The question is whether your business model can survive what they cost.

    Here is an honest look at the four programs restoration owners actually compare in 2026: Contractor Connection, Alacrity (now Altimeter Solutions Group on the managed repair side), Code Blue, and the smaller program work most operators don’t talk about openly.

    How TPA Economics Actually Work

    Clipboard and tablet on a kitchen counter during an insurance adjuster walkthrough after water loss
    How TPA economics actually work.

    Industry-reported referral fees on TPA work generally fall in a 5% to 20% range, with most managed-repair networks landing somewhere around 8% of the invoice. That fee comes off the top before you pay materials, labor, equipment, or overhead.

    The hidden cost is bigger than the fee. TPA work typically settles on extended payment terms — often 30 to 90 days — while your crews need to be paid weekly and your subs every other week. You finance the carrier’s cash conversion cycle out of your operating account. On a $5M operation running 25% gross margin, sitting on $300K of receivables longer than your direct-bill book costs you real money in line-of-credit interest, opportunity cost on equipment purchases, and the slow erosion of payroll-week stress.

    Industry consultants who work with restoration operators routinely advise keeping no single referral source above roughly 20% of revenue, and ideally under 10%. Once a TPA crosses that threshold, you are no longer a contractor — you are a subcontractor with a logo.

    Contractor Connection

    The largest network in the space and the one most operators encounter first. Owned by Crawford & Company, it positions itself with a “pay as you grow” structure: an application fee up front, then fees tied to the work you actually receive. Carrier relationships are deep, with most of the major property insurers routing some volume through Crawford’s managed-repair channel.

    Entry requirements published on Contractor Connection’s potential-contractor portal are not soft: a minimum of one year of financial statements demonstrating stability, $1M general liability, $1M auto, workers’ comp, all required state and local licensing, a clean credit background, criminal background checks on field employees, current estimating-software and digital documentation capability, twelve quality references, and a commercial or industrial-zoned facility. No home-based operations.

    Bottom line: Best fit for operators who already have crews, capacity, and the working capital to ride 60-to-90-day pay cycles. Worst fit for a $1M operator trying to use the program as growth capital — the volume will outrun your cash before margin catches up.

    Alacrity Solutions / Altimeter Solutions Group

    Alacrity announced the strategic sale of its Managed Repair Division, which now operates as an independent company under the Altimeter Solutions Group name with its existing leadership and team. Alacrity itself continues to run a broad TPA services book — claims handling, field adjusting, network solutions — but the contractor network specifically sits under the spun-off entity now.

    Entry requirements emphasize the same screening contractors see across the major networks: criminal background checks, current licensure and certifications, demonstrated financial stability, and proof of insurance. Their ACCESS program layers in affinity discounts, supplier programs, and growth resources for network members — useful at the margin if you’re already in, less of a reason to join.

    Bottom line: The leadership-continuity story on Altimeter is the thing to watch over the next twelve months. Spin-offs from larger TPA parents often go one of two ways: leaner and contractor-friendlier, or starved of resources and slower to pay. Talk to three current network contractors before signing — specifically about cycle time on payment since the transition.

    Code Blue

    An independent TPA serving casualty and property insurance carriers with end-to-end outsourcing. Smaller than Contractor Connection by volume, but contractors who run Code Blue work generally describe a more direct relationship with claim handlers and fewer layers of escalation. The trade-off is that Code Blue volume is lumpier — when a carrier surge hits, you get the work; when carriers route elsewhere, your queue thins.

    Requirements track industry standard: financial stability, customer service track record, business insurance, equipment, training, standardized estimating software. No home-based operations. Background checks and certification documentation required for field staff.

    Bottom line: Reasonable second or third program for an operator already in Contractor Connection who needs incremental volume without doubling down on a single source. Not a first-program choice unless your local market has a Code Blue–heavy carrier mix.

    What “Worth It” Actually Looks Like

    Flow from estimate to photos to notes to payment emphasizing integration
    Worth it means workflow fit — not logo count.

    Run the math on your own P&L before you sign anything. A direct-bill water-mit job at a healthy restoration shop targets gross margin in the 35% range after labor and materials. The same job under a TPA at an 8% referral fee, with the typical scope-and-pricing concessions and the 60-to-90-day pay cycle, often lands closer to 18-22% gross margin once you’ve fully loaded the cost of carrying the receivable.

    That gap is not a reason to refuse program work. It is a reason to know exactly what it’s paying for. Program work pays for crew utilization in slow weeks. It pays for keeping equipment off the shelf. It pays for the operational discipline of running standardized scopes and tight documentation. What it does not pay for is replacing your direct-to-consumer marketing — because the second you let your local lead engine atrophy, you’re locked in at whatever margin the network decides to give you next year.

    The Exit Question

    Three panels for hand-off, sale, and legacy operation end-states
    The exit question before you join a network.

    Operators who successfully unwind from heavy TPA dependency rarely do it all at once. The pattern that works: cap program volume at a hard percentage (10-20% of revenue), reinvest the margin gap from non-program work into local SEO, LSA campaigns, and adjuster relationships, and use the program work as a deliberate utilization buffer rather than a primary revenue stream.

    Operators who get stuck in the trap share the same profile: 60%+ of revenue from one or two networks, no direct marketing investment, no adjuster-direct relationships in their territory, and a fleet and crew count sized to the program’s volume rather than their own sales engine. When the program cuts your assignments — and it will, at some point, for reasons that have nothing to do with your performance — you have no Plan B.

    Bottom Line

    TPA programs are a tool, not a strategy. Contractor Connection is the most established and the highest-volume option for operators with the capital structure to absorb extended payment cycles. Altimeter (formerly Alacrity Managed Repair) is in transition and worth diligence before joining. Code Blue makes sense as a secondary source, not a primary one. Whatever you sign, build the business to survive without it — because every restoration operator who has run a TPA-heavy book for more than five years will tell you the same thing: the program does not love you back.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
    Frequently Asked Questions

    What percentage do TPAs typically charge restoration contractors?

    Referral fees in restoration TPA programs generally fall between 5% and 20% of the invoice, with most managed-repair networks landing near 8%. The fee comes off the top before you pay labor, materials, or overhead.

    How long do TPA programs take to pay restoration contractors?

    Payment cycles on TPA work commonly run 30 to 90 days, which means you finance the carrier’s cash conversion cycle out of your operating account. Plan working capital accordingly before signing any program agreement.

    Should I rely on a single TPA for most of my revenue?

    No. Industry consultants advise keeping any single referral source under 20% of revenue, ideally under 10%. Above that threshold, you lose pricing power and become structurally dependent on a relationship you don’t control.

    Is Contractor Connection or Alacrity better for new contractors?

    Contractor Connection has deeper carrier relationships and higher volume, making it the more common first program. Alacrity’s contractor network sits under the spun-off Altimeter Solutions Group as of the recent transition, which adds diligence risk for new entrants — talk to current network contractors about payment timing before joining.

  • DASH vs Albi vs PSA vs Xcelerate: The Honest 2026 Restoration Software Comparison

    DASH vs Albi vs PSA vs Xcelerate: The Honest 2026 Restoration Software Comparison

    If you run a restoration company doing between $1M and $10M, the software question is no longer “do we need a system?” It’s “which one do we commit to for the next five years, because the switching cost is going to hurt either way.” This is the honest comparison nobody selling you a demo will give you — built from each vendor’s own site, with the Xactimate / profitability / multi-location matrix verified 8 September 2026.

    Direct Answer (September 2026): The four purpose-built restoration job platforms are Cotality DASH (TPA / insurance programs), Albi (customizable retail, Pro seats for Xactimate), PSA by Canam (ERP + job costing, flat team pricing), and Xcelerate (process discipline, job-level margin). Xactimate / XactAnalysis is the estimate and assignment layer, not a fifth job system. Encircle, CompanyCam, JobNimbus, and ServiceTitan are adjacent tools, not the system of record.

    The restoration software market in 2026 has consolidated into those four platforms plus a tier of adjacent tools that solve part of the problem and force you to stitch the rest.

    The short answer for impatient owners

    • DASH (Cotality): Deepest insurance-ecosystem path. First look if TPA volume is more than 30% of the book. Formerly DASH by Next Gear Solutions.
    • Albi: Most customizable. $6,000 minimum annual subscription ($60/seat Base, $100/seat Pro). Xactimate and XactAnalysis on Pro seats only.
    • PSA (Canam Systems): Independently owned ERP. Flat team pricing. Stronger once you cross roughly 15 users. Lists Xactimate, XactAnalysis, and Symbility.
    • Xcelerate: Process discipline and job-level profitability. SOC 2 Type 2. Quote-only pricing.
    • ServiceTitan / JobNimbus / CompanyCam / Encircle: Too much platform, or not a system of record.

    Head-to-head

    Factor Cotality DASH Albi PSA (Canam) Xcelerate
    Pricing Quote $60 Base / $100 Pro / $6K yr min Flat team, quote Quote
    Best for TPA-heavy insurance work Retail + customization 15+ users, job costing SOP and margin control
    Xactimate Vendor Exchange import Pro seats; pull into workbook, no push back Listed + XA Listed; work orders from lines
    QuickBooks Online + Desktop Online + Desktop Yes Yes
    Mobile iOS + Android, offline Albi Mobile Proven OnSite Field-to-office
    Security AICPA SOC 2 Type II Not disclosed Not disclosed SOC 2 Type 2
    Owner Cotality Independent Independent Independent (Teamfront acquisition reported 2024)

    Xactimate and XactAnalysis: integration is not one feature

    Verified 8 September 2026: Cotality DASH help (Vendor Exchange, link assignment), Albiware Xactimate docs, canamsys.com, xlrestorationsoftware.com Verisk page, XactAnalysis third-party integrations list.

    All four advertise a Xactimate path. The operator question is whether the estimate becomes a carrier-ready assignment without a second spreadsheet.

    Motion DASH Albi (Pro) PSA Xcelerate
    Estimate in Vendor Exchange into the job (X1 sync or Xactimate Online auto-sync). Pulls completed estimates into the workbook. Albi docs: does not push estimates from Albi into Xactimate. Xactimate and XactAnalysis listed on canamsys.com. Create/sync estimates; work orders from line items (vendor webinar + integration page).
    XactAnalysis Link XA / Claims Workspace to an existing job or claim. Corporate dispatched assignments cannot attach to a locally created Job. On Pro seats. Actionable Insights profile can be the default Xactimate profile. Listed partner. CanAm Systems also appears on XactAnalysis’s own integrations list. Listed on the Verisk page. Confirm two-way assignment sync in demo — older copy on that URL used “soon.”
    Carrier reporting Estimate on the job slideboard; Compliance Manager for program checklists. Recap by category; material/labor/equipment split; optional separate O&P lines. Job costing in Proven Accounting next to the estimate. Work orders and sub scopes from estimate lines; job margin view.

    Xactimate is the estimate writer, not a fifth job-management platform. Insurance-backed shops need the job ID to survive supplement and invoice. Detail page: Xactimate integration compared.

    Profitability tracking

    “Profitability dashboard” means estimate vs labor, equipment, and sub invoices on the same file. Field list: Restoration job management profitability dashboards.

    • Albi: Public Xactimate page covers estimated vs actuals, trade work orders, invoicing. Analytics add-on from $250/mo (June 2026 card): WIP, aging, job costing, division/PM splits.
    • Xcelerate: Sells job-level profitability and work orders from estimate lines.
    • PSA: Proven Accounting + Proven Analytics. Flat team pricing is the cost bet at 15+ users.
    • DASH: Live budgets on the job (Cotality product page). Stronger on program compliance than retail margin theater. Ask for estimate-vs-actual export on a closed file.

    No vendor publishes a comparable public margin-% screenshot you can put in an RFP. Make every demo open one closed water job and one rebuild.

    Multi-location and concurrent jobs

    • DASH: Built for program volume and multi-crew disaster work. Offline mobile. Dispatched program claims and local jobs are different objects.
    • Xcelerate: Markets to multi-location and franchise operators. SOP stage gates are the control. Confirm location permissions and shared XA assignments.
    • PSA: Named multi-brand logos on canamsys.com (BluSky, Winmar, PuroClean Canada, Dalworth). ERP assumes concurrent jobs. Implementation time is the tax.
    • Albi: Pro role-based permissions. Concurrent-project rules are whatever you configure. Multi-location needs that demo, not the homepage.

    Alternatives to DASH and Albiware

    If those two are off the table, stay inside the same four. Do not promote Encircle, JobNimbus, CompanyCam, or ServiceTitan to system of record.

    1. Xcelerate — process enforced; live inside work orders from Xactimate lines.
    2. PSA — headcount heading past ~15; accounting and jobs in one independently owned ERP.

    Water-only Albi vs DASH lives on the existing pair page: Albi vs DASH for water damage (2026).

    The four platforms, in brief

    Cotality DASH

    Connects to QuickBooks Online/Desktop, Sage 100/300, Claims Connect, Matterport, DocuSketch, Cotality CRM, Cotality Mitigate. AICPA SOC 2 Type II. Offline mobile. Compliance Manager for carrier checklists. Quote: (866) 774-3282. Breaks when you want the workflow to be yours, not the program’s.

    Albi

    June 2026 public card: Base $60, Pro $100, $6K year minimum (2 Base + 2 Pro), onboarding from $1,000, Analytics/Automations from $250/mo each. DryBook 2.0 on Base. Xactimate/XA on Pro. Breaks at 20+ seats versus PSA flat pricing.

    PSA (Canam)

    Proven Accounting, Jobs, CRM, OnSite, Analytics. Open API. Xactimate, XactAnalysis, Symbility, Encircle, Matterport, DocuSketch. 9,278+ contractors claimed on canamsys.com. UI and ramp are the cost.

    Xcelerate

    SOC 2 Type 2. Job management, CRM, dashboards. Integrations listed on xlrestorationsoftware.com including Xactimate/XactAnalysis, CompanyCam, Encircle, Matterport, Power BI, TSheets. Customization is intentionally low. Quote: (423) 405-6417.

    Decision framework

    1. TPA / direct insurance above 30% of revenue? DASH first.
    2. Users 24 months out above 15? Force PSA into the demo.
    3. Software should enforce process (Xcelerate) or mirror yours (Albi)?

    A $3M shop with eight users on the wrong platform burns 40–120 estimator/admin hours a month on double entry and late invoices. Sticker price is the wrong optimization.

    Frequently Asked Questions

    Do all four integrate with Xactimate and XactAnalysis?

    All four advertise Xactimate. DASH uses Vendor Exchange and can link XA assignments, with rules on dispatched program claims. Albi Pro pulls estimates in and does not push them back. PSA and Xcelerate both list XA; confirm supplement direction on a live file. XactAnalysis’s own list includes DASH and CanAm Systems.

    Which platform is best for job profitability tracking?

    Albi publishes estimate-vs-actuals plus an Analytics add-on. Xcelerate sells job-level margin and work orders from estimate lines. PSA puts costing in Proven Accounting. DASH tracks live budgets and is stronger on program compliance. Demand the same closed-job walkthrough from every demo. Field list: profitability dashboards.

    What are the alternatives to DASH and Albiware?

    Xcelerate and PSA. Adjacent tools are not replacements for the system of record.

    How much does Albi cost?

    Per albiware.com, June 2026: Base $60/user/mo, Pro $100/user/mo, $6,000 year minimum, onboarding from $1,000, Analytics and Automations from $250/mo each.

    Does Albi integrate with Xactimate?

    Yes, on Pro seats only ($100/user/mo), including XactAnalysis. Not on Base seats.

  • How Buyers Price a Restoration Company: 2026 Deal Killers

    How Buyers Price a Restoration Company: 2026 Deal Killers

    Most restoration buyers in 2026 are paying for the wrong things. They look at top-line revenue, the truck count, the trailing-twelve EBITDA — and miss the structural details that decide whether the company they just bought is a $4M business or a slow-motion writedown. Private equity has deployed over $6 billion across 50-plus platforms since 2018, and the buyers who keep winning at these multiples are the ones with a checklist that goes deeper than the broker’s pitch deck.

    Here is what the disciplined buyers — strategic acquirers, PE platforms, and operator-buyers — actually look at when they price a restoration company in 2026, and the five line items that quietly kill more deals than anything in the financials.

    What buyers are actually paying for in 2026

    Six cards: repeatable jobs, clean books, bench depth, channel mix, owner optional, risk controls
    What buyers pay for in 2026 — transferability over heroics.

    Median sale prices in restoration have risen to roughly $2.2M. Shops under $2M in revenue tend to clear at 2.5x to 3.0x SDE. The $2M to $5M EBITDA band — what the industry calls the PE feeder zone — trades at 4x to 6x EBITDA. Platforms above $10M EBITDA push 6x to 8x with strategic buyers willing to stretch further for the right geography or carrier panel. The spread between bottom and top of that range is not random. It is a function of five drivers that a thorough buyer will price line by line.

    Carrier preferred-vendor status is the first thing on every diligence sheet. A company on the preferred panel of two or more Tier 1 carriers — State Farm, Allstate, USAA, Liberty Mutual — gets a multiple premium because that revenue is durable, repeatable, and very hard for a new entrant to replicate. A company that depends on one TPA program for half its work gets discounted because that revenue is one phone call away from disappearing.

    Revenue mix matters almost as much. Mitigation-heavy companies — fast-turn water and emergency services — carry better margins and more predictable cash conversion than companies leaning on large-loss reconstruction. Reconstruction-heavy shops can still trade well, but buyers will model lower margins and longer working-capital cycles, which compresses the multiple.

    Management depth below the founder is the third lever. If the owner is the estimator, the rainmaker, and the operations lead, the buyer will assume a 12 to 24 month earnout structure and discount the price accordingly. A general manager, an estimating lead, and a production manager who are staying through transition can add an entire turn of EBITDA to the offer.

    CAT exposure is the fourth. Companies with more than 20-25% of revenue tied to catastrophic events get valued on a normalized basis — buyers strip the spike years out of the average. If you bought a restoration company on a peak hurricane year’s numbers, you overpaid. Sophisticated buyers know this and adjust before they sign the LOI.

    The fifth is books that survive a quality-of-earnings review. In about 85% of deals, the QoE adjusts down from the seller’s claimed EBITDA, and the average haircut runs 10 to 15%. Companies that have already run a sell-side QoE and addressed the easy adjustments hold their price better than companies that hand a buyer a QuickBooks export and a confident shrug.

    The five quiet deal-killers

    Red checklist of five quiet deal killers for restoration M&A
    Five quiet deal-killers — fix before the LOI.

    Most deals do not die on price. They die in the back half of due diligence, when something surfaces that the seller either did not disclose or did not realize mattered. These are the five issues that show up most often, and what a disciplined buyer does about each one.

    1. Customer or carrier concentration over 20%. If a single carrier, TPA program, or property manager drives more than a fifth of revenue, the company has a single point of failure. Buyers either re-price the deal, structure a larger earnout tied to retention, or walk. The honest fix on the seller side is to diversify the book 18 months before going to market, but most do not have that luxury once they have decided to sell.

    2. Licensing and certification gaps. Restoration is a regulated trade in most states. Buyers verify IICRC firm certification, individual technician WRT and ASD credentials, AMRT for mold work, state contractor licenses, and any specialty endorsements required locally. A lapsed firm certification or an expired mold license is not always a deal-killer, but it is always a price renegotiation and sometimes a regulatory exposure that gets baked into the purchase agreement as an indemnity.

    3. Aged accounts receivable. Restoration AR ages slowly because insurance carriers and TPAs pay slowly. Buyers will look at the receivables aging report and discount anything over 90 days, sometimes severely. If a meaningful portion of the company’s "earnings" is actually trapped in 180+ day AR that nobody is going to collect, the working capital adjustment at close will swallow a real chunk of the purchase price.

    4. Founder dependency in estimating and sales. This is the single most common reason restoration deals collapse or restructure into heavy earnouts. If the founder writes 60% of the estimates and personally manages the top carrier relationships, buyers know the business does not transfer. The seller who builds a real estimating department and pushes carrier relationships down to a sales lead two years before sale will capture meaningfully more value.

    5. Compliance and labor exposure. 1099 versus W-2 misclassification, prevailing wage issues on commercial jobs, OSHA history, and EMR trends all surface in diligence. Buyers will hire an HR specialist on any deal above a few million in revenue, and a clean compliance picture is worth 0.25x to 0.5x of EBITDA on its own.

    What a buyer should actually run before the LOI

    Six cards covering job margin, cycle time, AR days, utilization, CAC, close rate
    Run unit economics before the LOI — not after.

    The minimum diligence package on a serious restoration acquisition includes: a quality-of-earnings review by a firm that has seen at least a dozen restoration deals, an independent verification of carrier preferred-vendor status and any TPA contracts, a customer concentration analysis at the carrier and account level, an AR aging review by a buyer-side accountant, an IICRC and state licensing audit, and a sit-down with the operations and estimating leads with the founder out of the room. That last item is the most underused and the most predictive.

    Buyers who skip any of these line items end up renegotiating after close or eating a writedown a year in. Buyers who run all of them tend to pay slightly less and own businesses that transfer cleanly.

    Bottom line

    The 2026 restoration market is the best buyer’s window of the next five years, but only for buyers with discipline. The capital is there, the seller pipeline is there as the founder generation exits, and the platform playbook has been proven by HighGround, American Restoration, and a half-dozen others. The companies worth buying at top-of-range multiples are the ones with diversified carrier mix, real management depth, and books that survive a serious QoE. Everything else is a turnaround dressed up as an acquisition — and turnarounds in restoration take 18 to 36 months to fix and often cost more than the purchase premium ever saved. Pay for what transfers. Walk from what does not.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
    Frequently asked questions

    What multiple do restoration companies sell for in 2026?

    Sub-$2M revenue shops typically trade at 2.5x to 3.0x SDE. Companies in the $2M to $5M EBITDA range — the PE feeder zone — clear 4x to 6x EBITDA. Platforms above $10M EBITDA reach 6x to 8x, with strategic premiums pushing higher in the right geography or carrier panel.

    What kills restoration acquisition deals most often?

    Customer or carrier concentration above 20%, founder dependency in estimating and sales, aged accounts receivable that does not collect, licensing or IICRC certification gaps, and labor compliance exposure — in roughly that order of frequency.

    How long should a buyer-side diligence process take?

    For a sub-$5M revenue restoration acquisition, plan on 60 to 90 days from signed LOI to close. Quality of earnings runs three to five weeks, legal and licensing diligence runs parallel, and customer/carrier verification typically lands in the final two weeks before close.

    Is buying a restoration franchise better than buying an independent?

    Franchises like SERVPRO or ServiceMaster Restore deliver brand, training, and national-account access at the cost of royalties and territorial restrictions. Independents give you full margin upside and the freedom to build proprietary carrier relationships, but require self-built systems and certifications. For first-time operators, the franchise reduces execution risk. For experienced operators, an independent acquisition tends to compound faster.

  • Xactimate Sketch Workflows: Encircle vs DocuSketch Costs

    Xactimate Sketch Workflows: Encircle vs DocuSketch Costs

    Most restoration owners I know underestimate what their sketch workflow actually costs them. Not the per-claim app fee — the labor hour buried in every job where a tech spends 90 minutes measuring a flooded basement with a laser distance meter, then another 45 minutes back at the office rebuilding it in Xactimate Sketch. At a loaded labor rate of $45 an hour and ten water jobs a week, those 135 minutes per job add up to roughly $52,000 a year in tech hours tied up in measurement and sketch rebuild — a meaningful chunk of which is not directly billable. The sketch is the foundation of every line item Xactimate calculates — walls, floors, ceilings, missing wall openings, ceiling height multipliers — and if it’s wrong, the entire estimate inherits the error. So the question is not whether to invest in a sketch workflow. It’s which one.

    Why the sketch is the most expensive five minutes in restoration

    Four steps: phone capture, sketch in Xactimate, review, supplement
    Sketch is expensive when you redo it — capture once.

    Xactimate utilizes the sketch to drive line item quantities — square footage of drywall, linear feet of base trim, square footage of ceiling, paint surfaces, area for antimicrobial application. Get the ceiling height wrong by six inches in a 200-square-foot room and you’ve quietly undercut your paint and wall labor by roughly 100 surface square feet. Forget to draw a missing wall between a kitchen and a dining room and Xactimate treats them as two separate sealed rooms — doubling perimeter trim, ignoring shared dry-out airflow, and producing a scope that any seasoned adjuster will flag and ask you to redo.

    Common sketch errors compound: rushing through measurements without verification, failing to account for wall thickness, overlooking irregular features like soffits or knee walls, and using incorrect roof pitch on exterior sketches. The result is either lost revenue on your end (you underbilled) or a denial cycle on the carrier side (the adjuster sends it back and your cash conversion stretches). Either way, the sketch is where the money leaks out.

    The three sketch workflows actually used in the field

    Gloved hands using a pin-type moisture meter on wet drywall during inspection
    Three field workflows — pick one and train it.

    Despite a dozen marketing pitches, restoration contractors use one of three approaches. Each has a real cost and a real time profile.

    1. Manual Xactimate Sketch (laser distance meter + on-screen drawing)

    The default. A tech walks the loss with a Bosch or Leica laser, writes measurements on a clipboard or phone notes app, then either sketches on-site in the X1 mobile app or rebuilds it at the office. Cost is whatever you already pay for Xactimate (Professional runs around $185/month per user on subscription pricing as of early 2026, per Verisk’s published rates — verify on your own contract because Verisk negotiates).

    Realistic time for a competent tech on a 1,500-square-foot residential water loss: 45–60 minutes on-site for measurements and photos, plus 30–45 minutes back at the office to build the sketch in Xactimate. Call it 90 minutes total. The advantage: no extra software cost, full control. The disadvantage: every minute of that 90 is a minute a tech is not on another job, and your sketch accuracy depends entirely on how disciplined your tech is with a laser.

    2. Encircle Floor Plan

    Encircle’s floor plan product converts a smartphone video walkthrough into a Xactimate-ready ESX or FML import. Their published per-claim pricing is around $25 per claim as of 2026, with subscription bundles available — confirm current pricing with Encircle directly, as restoration software vendors revise tiered pricing frequently. Encircle’s marketing claims floor plans are delivered in under 6 hours, but in practice most users report same-day to next-morning turnaround.

    The actual workflow advantage is not the speed of delivery — it’s that your tech leaves the loss with a video, not a sketch. On-site time drops to roughly 15–25 minutes. The office labor for sketch rebuild drops to near zero because Encircle delivers an importable file. If you’re running 40 claims a month and trimming 60 minutes per claim, that’s 40 hours of tech labor recaptured — roughly $1,800 a month in labor against $1,000 in Encircle fees. The math works above about 25–30 claims a month.

    3. DocuSketch

    DocuSketch uses a 360 camera kit instead of a smartphone video. The contractor captures spherical photos at each room, uploads, and DocuSketch returns an ESX file. Per their public materials, ESX and FML files are typically delivered 1 to 3 days after capture. Per-claim cost at scale runs around $70 when amortizing the Express plan ($1,095/month), the $795 camera kit, and overnight delivery fees against 20 projects a month — based on DocuSketch’s published comparison materials.

    DocuSketch’s appeal is the 360 photo documentation that comes with the sketch — useful for supplement defense and for adjuster file packages. The disadvantage versus Encircle: slower turnaround (days, not hours), higher per-claim cost, and a camera kit your techs have to actually carry and use. For high-volume shops doing large losses and commercial work where 360 documentation has independent value, DocuSketch can earn its keep. For a typical residential water mitigation shop, the price-per-claim is hard to justify against Encircle.

    The bottom line for restoration owners

    White restoration work van with ladder rack parked at a suburban jobsite curb
    Bottom line: faster accurate sketches protect margin.

    If you’re under 20 claims a month, manual sketching is fine. Buy your techs better lasers and train them on Xactimate Sketch keyboard shortcuts (CTRL+click and drag to pull new rooms from existing ones is the single highest-leverage shortcut Xactimate ships). Sending a tech to one of the regular Xactimate fundamentals classes pays for itself the first month — it’s the cheapest sketch optimization you can buy.

    If you’re between 20 and 60 claims a month and most of your volume is residential water, Encircle Floor Plan is the obvious move. The labor recapture pays for the subscription several times over, and your techs spend less time at the office rebuilding sketches and more time at the next loss. Make sure your techs actually shoot the video correctly — Encircle’s output quality depends on input quality.

    If you’re north of 60 claims a month, running commercial losses, or losing supplements because your documentation packages are thin, evaluate DocuSketch alongside Encircle. The 360 documentation is a real defensible asset when you’re supplementing six months after the original scope. Some shops run both — Encircle for residential water mitigation, DocuSketch for commercial and large-loss reconstruction.

    One workflow truth nobody likes to say out loud: the sketch tool only matters if your techs use it consistently. The shops that get the most out of Encircle or DocuSketch are the ones where the office manager refuses to accept a claim file without a video or 360 capture. Without that enforcement, you’re paying for software and still rebuilding sketches at the office because half your techs forgot to use it.

    Pick the workflow that fits your claim volume, then enforce it. The sketch is the foundation of every line item Xactimate calculates. It’s worth more attention than most owners give it.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
  • Restoration Company Org Structure: Scaling $2M to $25M

    Restoration Company Org Structure: Scaling $2M to $25M

    If you own a restoration company doing somewhere between $2M and $10M a year, you are operating in the most actively consolidated environment this industry has ever seen. Reported figures put the U.S. restoration market at roughly $7.1B in 2025, growing in the 5–6% CAGR range, with 50+ private equity platforms reportedly acquiring operators at multiples in the 4x–7x EBITDA range. Quality scaled operators in the $8M+ range have reportedly traded at the upper end — approximately 6x–8x EBITDA — when the asset is built right.

    Almost none of that value gets captured by accident. The org chart you build at $2M determines whether you can survive $5M. The systems you install at $5M determine whether $10M makes you or breaks you. And the structure at $10M determines whether a PE platform sees you as a bolt-on at a discount or a regional anchor at a premium.

    Here is the honest breakdown of what the org should look like at each revenue milestone, what the typical owner gets wrong, and what an exit-aware growth path actually requires.

    $2M: The owner-operator squeeze

    At $2M, the owner is still the bottleneck of every consequential decision. A typical structure: the owner does sales, estimating, and major-loss oversight; one office admin handles AR/AP and scheduling; six to eight technicians split across two to three trucks; one lead tech runs supplements informally. Reconstruction is either non-existent or subcontracted ad hoc.

    What this stage actually feels like: gross margins on mitigation can run in the reported 65–75% range, but the owner’s labor is uncosted. If you charged your own time at the rate of a real operations manager (approximately $80K–$110K fully loaded), most $2M shops would discover their actual margin is thinner than their P&L suggests.

    The mistake at this stage: hiring more techs to grow revenue. More techs at $2M without a coordination layer creates more chaos, not more profit. The next hire is not a fifth tech. It is the first non-owner decision-maker.

    $5M: The operations manager inflection

    Five seat cards: owner, ops lead, PM bench, sales, admin
    Seats change as revenue changes — titles are not the strategy.

    $5M is where the structure has to change or the owner will burn out. The proven move is to hire a real operations manager — someone who owns the mitigation P&L day to day so the owner can focus on relationships, supplements, and growth. Reported compensation ranges for restoration operations managers cluster around $80K–$120K base plus variable, depending on market.

    The $5M org typically looks like: owner; operations manager; one project manager for mitigation; one project manager (or a lead carpenter functioning as one) for reconstruction; office admin handling AR/AP; a dedicated estimator or supplement coordinator; 10–14 technicians across 4–6 trucks; one or two carpenters or subs handling reconstruction in-house.

    This is also the stage where adding reconstruction matters disproportionately. Reported gross margins on reconstruction land in the 25–40% range — lower than mitigation but on much larger ticket sizes. A company that captures 25–30% of its mitigation revenue as in-house reconstruction by Year 3 of scaling tends to be substantially more valuable at exit, because reconstruction revenue is harder to replicate and stickier with carriers.

    The mistake at this stage: the owner refuses to fully hand over the mitigation P&L. The operations manager becomes a dispatcher instead of a real GM. The org gets stuck at $5M for years.

    $10M: The platform-decision stage

    Restoration technicians training in a shop bay with equipment demo and whiteboard
    Platform-decision stage: managers own the week.

    At $10M, the question is no longer “how do we grow?” — it is “what are we growing into?” There are two paths and they require different org structures.

    Path A — single-market dominance. Stay in one metro, deepen TPA relationships (typically expanding from 2–3 carrier programs to 4–6), build a dedicated commercial division, and push toward $15M–$18M in a single footprint. Org: owner shifts to CEO role; operations manager promoted to COO; one mitigation manager; one reconstruction manager; commercial division lead; in-house controller or fractional CFO; dedicated marketing manager; office admin team of 2–3; 20–30 field staff.

    Path B — multi-location expansion. Open a second branch in an adjacent market. This is where most $10M companies break. The org has to duplicate without doubling overhead: branch manager who reports to a regional operations leader; standardized SOPs, training, and KPIs; shared back-office (AR/AP, HR, marketing) from the home office; one finance function across both branches.

    Reported industry experience is that the second location is the hardest. Branch three and four are dramatically easier if branch two is run with discipline. Most owners who fail at multi-location failed because they opened branch two as a bolted-on copy of branch one and did not build a real regional management layer in between.

    $25M: Platform-ready

    By $25M, the company is no longer a restoration business in the operational sense. It is a portfolio of branches with a central operating system. Org at this stage typically includes: CEO; COO; CFO (real, not fractional); VP of operations; regional operations managers (one per 2–3 branches); a dedicated commercial sales team; a marketing director; HR director; training manager; and 60–120+ field staff.

    This is the structure PE platforms actually pay premiums for. The reported pattern: companies built around the owner trade at the lower end of the 4x–7x EBITDA range. Companies built around a system, with EBITDA visibility, repeatable branch economics, and a non-owner-dependent management team, trade at the upper end — approximately 6x–8x EBITDA, with some strategic transactions reportedly going higher.

    The exit-aware framing

    Three panels for hand-off, sale, and legacy operation end-states
    Exit-aware framing — org chart is part of the multiple.

    Most restoration owners build the org chart they need today. Owners who exit well build the org chart their next buyer will want. The functional difference is small. The financial difference is enormous.

    At $5M EBITDA of $1M, the difference between a 4x exit and a 7x exit is $3M. That gap is almost entirely a function of org structure, not revenue. Two restoration companies with identical revenue and identical margins will trade at different multiples if one is owner-dependent and the other is system-dependent.

    Bottom line

    The growth path is not a revenue chart. It is a sequence of structural inflection points. At $2M, the next hire is not a tech — it is a manager. At $5M, the next decision is not “more sales” — it is whether the owner will actually hand over the mitigation P&L. At $10M, the decision is single-market depth versus regional expansion, and the org has to be built before the second branch opens. At $25M, the company is either a platform asset or a glorified job shop — and the buyer can tell the difference in the first meeting.

    The market is paying premium multiples for companies that look like platforms. Build the org that gets paid.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
    Frequently Asked Questions

    What is the right first non-tech hire for a $2M restoration company?

    An operations manager or general manager who can own the mitigation P&L day to day, freeing the owner to focus on sales, supplements, and growth. Hiring another technician at this stage typically adds chaos, not profit, because the coordination bottleneck is the owner, not the field capacity.

    When should a restoration company add in-house reconstruction?

    Most owners benefit from adding reconstruction once they hit roughly $3M–$5M in mitigation revenue and have a stable operations manager in place. Reconstruction increases average ticket size, deepens carrier relationships, and is harder to replicate, which raises the exit multiple. Adding reconstruction before the org can support it usually just adds risk and overhead.

    What EBITDA multiple do restoration companies sell for in 2026?

    Reported ranges put quality restoration operators at 4x–7x EBITDA, with companies scaled to $8M+ in revenue and built around a system rather than the owner reportedly trading at the upper end of approximately 6x–8x EBITDA. Smaller operations under $500K in SDE often transact closer to 2.8x–3x on an SDE basis rather than an EBITDA basis. Numbers vary by region, carrier relationships, and quality of management team.

    Is multi-location expansion or single-market depth the better growth strategy?

    Both work, but they require different org investments. Single-market depth at $15M–$18M from one footprint can produce strong cash flow with less management complexity. Multi-location expansion produces higher exit valuations and platform optionality, but only if a regional management layer is built before the second branch opens. The most common failure mode is opening a second location without that layer in place.

  • Restoration Company Marketing: 2026 LSA, SEO & CAC

    Restoration Company Marketing: 2026 LSA, SEO & CAC

    Restoration company marketing is one of the most expensive paid-search categories in the United States. “Water damage restoration” keywords routinely clear $60–$85 per click in competitive markets, with reported outlier bids running well over $200 in metros like New York, Houston, and South Florida. Industry tracking has flagged some emergency-restoration terms breaking $500 per click in specific moments. Meanwhile, the average home-services lead via Google Local Service Ads (LSA) is roughly $53 — but water damage restoration sits at the premium end, with reported LSA cost-per-lead ranges of approximately $80–$180 depending on market.

    If you run a $3M–$15M restoration company, this is the single biggest line item that nobody on your team is staring at correctly. Owners hear “marketing” and think website. The real fight in 2026 is channel allocation: how much should you spend on LSA, how much on Google Search Ads, and how much on owned SEO — and at what point does each one stop scaling? Here is the honest breakdown a $5M owner needs before their next marketing budget meeting.

    The three channels that actually matter

    Three cards for LSA, search ads, and SEO/AI authority channels
    Three channels that actually matter for restoration demand.

    For commercial water and fire restoration in 2026, three channels do the heavy lifting: Google Local Service Ads (the LSA “Google Guaranteed” boxes at the very top of the SERP), Google Search Ads (the paid text ads below LSA), and organic SEO (the map pack plus blue links). Everything else — Yelp, Angi, HomeAdvisor, Facebook, programmatic display, lead-broker buys — is either supplemental, declining, or actively cannibalizing your margin. The first decision is choosing where the bulk of your new-customer budget goes among those three.

    Local Service Ads (LSA) — the default starting point in 2026

    LSA is the highest-real-estate placement on a phone screen, period. For emergency-driven categories like water damage and mold, that real estate matters more than anything else. Reported 2026 cost-per-lead for water damage restoration through LSA generally falls in the $80–$180 range, with some markets reporting averages closer to $100 in stable competitive conditions. On a $6,000 average ticket, even a $150 LSA lead at a 25–35% close rate produces a customer acquisition cost (CAC) of roughly $450–$600 — which is workable on jobs that gross $1,800–$2,400.

    The catch: Google removed credits for “job type not serviced” and “geo not serviced” leads in 2025, meaning every junk lead now hits your card with no recourse. You have to dispute leads inside Google’s dispute window and you have to answer your phone in under 30 seconds. LSA also weights reviews more heavily than any other channel — a 4.6 average will visibly underperform a 4.9 in the same zip code. If your review velocity is under 8 per month, fix that before you scale LSA spend.

    Google Search Ads — the diminishing-returns layer

    Below LSA, traditional Google Search Ads remain expensive and uneven. Reported 2026 average CPC for water damage restoration keywords falls into bands: bottom-of-funnel emergency keywords like “emergency water damage [city]” run $60–$85; less-direct terms like “water damage cleanup near me” run $40–$65; awareness-stage keywords like “what to do after a flood” run $20–$40. The trap is that close rates on Search Ads have been compressing for three reasons: LSA is taking the highest-intent clicks, AI Overviews are stealing informational queries, and click fraud from competitor bots remains nontrivial.

    For most restoration owners, Search Ads should be a defense-and-coverage play, not a primary growth channel. Bid on your own brand name to keep TPA programs and franchise competitors from arbitraging your traffic. Bid on the keywords LSA does not cover well (commercial, mold remediation, biohazard, contents pack-out). Cap monthly spend. Watch the CAC, not the CPC.

    SEO — the compounding asset that owners under-invest in

    Owned SEO — Google Business Profile plus a real content engine on the company website — is where the math eventually breaks in your favor. Multiple cross-industry benchmarks in 2025–2026 put the cost-per-lead delta between SEO and paid search at roughly 4x–6x lower for SEO once a site is mature (typically 12–18 months in). One widely cited cross-industry benchmark places SEO CPL near $31 versus paid search closer to $181. Restoration-specific tracking from agencies serving the category has reported organic CPL well under $50 in established markets after 18+ months of investment, while paid CPL stays in the $150+ band.

    The painful truth: SEO has a CAC of essentially zero on the marginal lead, but you cannot start it in January and expect leads in March. The owners who win SEO in restoration started 24 months ago, publish 6–12 useful pieces a month, and have a Google Business Profile with 500+ reviews and weekly post activity. If you have not started, your starting line is today — not next quarter.

    The honest allocation for a $5M restoration company in 2026

    A defensible 2026 marketing budget for a $5M residential and small-commercial restoration company, assuming 60% TPA-fed and 40% self-generated, looks roughly like this on the self-gen side:

    • LSA: 45–55% of self-gen ad spend. Highest immediate ROI. Cap by service area until close rate clears 30%.
    • Google Search Ads: 15–20%. Brand defense plus commercial, mold, and biohazard keywords LSA underweights.
    • SEO and Google Business Profile: 25–35%. This is content, on-site technical work, review-generation systems, and GBP weekly posts. Treat it as an asset, not a cost.
    • Everything else (Yelp, Angi, Nextdoor, paid social): under 5% combined, and only with tracked phone numbers per channel.

    If your current mix is 80%+ LSA and 0% SEO, you are renting your customer pipeline from Google at a rate that will keep rising. If your current mix is 80%+ SEO and 0% LSA, you are leaving the highest-intent emergency calls on the table for competitors who will outbid you for them.

    What to measure, not what to chase

    Side-by-side of metrics to track versus vanity metrics to ignore
    Measure what pays — not vanity.

    CPC, CPL, and CAC are not the same number. Restoration owners chase CPC because Google Ads dashboards make it visible. The metric that should sit on your monitor is blended CAC by channel, calculated quarterly: total channel spend divided by booked jobs from that channel. Track three more numbers next to it — close rate from lead to booked job, average ticket size by channel, and lifetime value adjustments for repeat and referral. A $180 LSA lead with a 35% close on $7,000 average ticket is a different business than a $40 organic lead with a 12% close on $2,200 average ticket — even though the CPL looks better in column B.

    Bottom line

    White restoration work van with ladder rack parked at a suburban jobsite curb
    Bottom line: booked jobs beat pretty dashboards.

    In 2026, LSA pays the bills, Search Ads defends the perimeter, and SEO is the only channel that compounds. The restoration owners who will be writing larger checks to their estimators in 2028 are the ones who fund all three this year — and the ones who refuse to pay $150 for a water damage lead because “that’s expensive” will keep watching franchise competitors and out-of-town aggregators win the calls that finance their own retirement. The expensive lead is the one you didn’t bid on at 2 a.m. when the house was actively flooding.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.
    Frequently Asked Questions

    What is a good cost per lead for a water damage restoration company in 2026?

    Reported 2026 ranges put water damage LSA cost-per-lead at roughly $80–$180, with some stable markets averaging closer to $100. Google Search Ads CPL is generally higher and more volatile. Organic SEO CPL trends well under $50 in mature programs after 12–18 months. Evaluate against your average job size and close rate, not against a flat industry number.

    Are Google Local Service Ads still worth it for restoration companies?

    Yes, for emergency categories LSA remains the most cost-efficient paid channel in 2026 because of its top-of-screen placement and pay-per-lead structure. The caveats: Google removed credit for off-service-area and wrong-job-type leads, review velocity matters more than ever, and you have to answer the phone in under 30 seconds to keep ranking.

    How long until SEO produces restoration leads?

    Plan on 9–12 months for a Google Business Profile and review-driven program to generate meaningful local-pack volume, and 12–18 months for content-driven organic leads to show up in any volume. Owners who treat SEO as a 6-month sprint nearly always abandon it 30 days before it would have started working.

    Should I use a marketing agency or build in-house?

    Under $3M revenue, hire one credible local agency for LSA plus GBP and own SEO with a part-time writer. From $3M–$10M, split LSA/Search Ads with an agency and bring SEO content in-house under a marketing coordinator. Above $10M, build the function internally with a director-level hire — at that size your marketing spend funds a salary and the data needs to live on your side of the firewall.