Tag: puyallup

  • WSU Is Building an Aquaculture Center in Puyallup. Builders Have Until November 10 to Get in Line.

    WSU Is Building an Aquaculture Center in Puyallup. Builders Have Until November 10 to Get in Line.

    Washington State University is hiring a design-build team for new aquaculture facilities at its Puyallup Research and Extension Center, and the first door closes fast: statements of qualifications are due Tuesday, November 10, 2026, before 3:00 p.m. The contract covers both the Puyallup center and the Pullman campus, and its guaranteed maximum price is $25.6 million — design, construction, contingencies, and fees included, with Washington sales tax excluded.

    What gets built in Puyallup

    The Puyallup half of the project starts with a building that already stands. The center’s Salmon Lab, 4,542 net square feet, will be renovated across roughly 3,000 square feet of it. Alongside it, new construction adds approximately 8,000 to 12,000 square feet — space for fish rearing, quarantine and examination rooms, wet and dry laboratories, and cold storage — plus about 2,000 square feet of secured outdoor area for large fish tanks.

    The Pullman half of the same contract renovates aquaculture space in four buildings, including the Carver Farm Fish Vivaria, and adds 7,000 to 10,000 square feet of new construction near Carver Farm. One team takes both campuses: WSU is procuring a single progressive design-build contract, and responding teams are limited to the builder and the prime designer.

    The money is federal, and it has rules

    The project rides on a National Institute of Standards and Technology grant — award 60NANB26D275 — for what the funding proposal called a Scientific Research Center. At a Puyallup city council meeting in September, university representatives described the planned Puyallup aquaculture center as supported by a $50 million federal appropriation. The $25.6 million in the solicitation is a different and narrower number: the guaranteed maximum price for this design-build contract itself.

    Federal money brings federal conditions with it. The Build America, Buy America requirements sit inside the request-for-qualifications package, and the finished buildings must meet Washington’s Clean Buildings Performance Standard. A team that wins this job is signing up for both.

    A two-page audition

    For a $25.6 million contract, the first audition is strikingly small. The statement of qualifications is capped at two pages — 11-by-17, nothing under 10-point type — plus a single third page for the team’s resumes. WSU states plainly that pages beyond the three will not be reviewed. Shortlisted teams move to a proposal round due December 15; WSU expects to announce the selected team on Friday, December 18, 2026, and execute the agreement by December 29.

    The calendar

    • Optional Puyallup site walk: Thursday, October 29, 2026, 2:30–4:30 p.m., Allmendinger Building, 2606 W. Pioneer, Puyallup
    • Statements of qualifications due: Tuesday, November 10, 2026, before 3:00 p.m., by email in PDF to contracts@wsu.edu, cc carbour@wsu.edu
    • Proposals from shortlisted teams: December 15, 2026
    • Selected team announced: December 18, 2026
    • The long arc after selection: project confirmation in May 2027, detailed design in October 2027, construction documents in January 2028, and substantial completion in March 2029

    Questions go to the project manager, Cyndi Arbour, at carbour@wsu.edu or (509) 335-7010. The full solicitation, including the RFQ document itself, is posted on WSU Facilities Services’ alternative public works page, and the state’s Office of Minority and Women’s Business Enterprises carries the advertisement.

    What it adds to the town

    The Research and Extension Center has been becoming a water campus for years. Its master plan names the direction outright — a leader in water research — and its Salmon Ecology Toxicology Lab already works on the fish this region’s rivers are known for. The city marked the relationship in September, proclaiming September 21–26 as WSU Puyallup Research & Extension Center Appreciation Week, with center director Todd Murray addressing the council.

    An aquaculture build of this size makes that identity physical: renovated lab space, up to 12,000 new square feet, outdoor tank yards, and a construction run on West Pioneer that stretches into 2029. It lands in the same season the town’s Opportunity Zone nomination went to Treasury — different money, same direction. Puyallup’s research footprint is compounding, and universities build the kind of institutions that stay for decades.

    We will name the selected team here when WSU announces it on December 18.
  • Heritage Square Sold for $25 Million — and Its Rents Tell the Puyallup Housing Story

    Heritage Square Sold for $25 Million — and Its Rents Tell the Puyallup Housing Story

    The sale. Heritage Square, a 104-unit apartment community in Puyallup, sold for $25 million — $240,385 per unit — in a deal announced October 22, 2026 by Institutional Property Advisors (IPA), a division of Marcus & Millichap. Both the buyer and the seller are private investors; neither is named in the announcement.

    A first sale, 25 years in. Built in 2001, Heritage Square had never before been offered for sale before this deal. It is a low-density, gated community on six acres of landscaped green space, with townhome and rambler floor plans averaging 1,041 square feet and private garages — a suburban rental product that looks a lot more like a neighborhood than a complex.

    The number that explains the deal. According to Philip Assouad, the IPA executive managing director who led the sale team, Heritage Square's rents run approximately 50% below current local mortgage costs. That single comparison is the economics of the whole transaction: in a city where buying a home costs roughly twice what renting one of these units costs, a well-kept rental community has a durable reason to stay full.

    Why an investor pays $25 million for below-market rents

    The renter base is anchored by an employer. Assouad pointed to the property's proximity to MultiCare Good Samaritan as support for "a strong, stable renter base." MultiCare is Puyallup's second-largest employer and sits within one mile of the property. Renters who work nearby and cannot make the mortgage math work are not a temporary audience — they are a structural one.

    The location does quiet work. Heritage Square sits near the Washington State Fairgrounds, close to State Route 512 and Interstate 5, with downtown Tacoma, the Kent Valley, Sea-Tac Airport, Seattle, and Renton all within commuting reach. A renter can hold a job almost anywhere in the central Puget Sound corridor and still come home to Puyallup.

    The upside is in the original finishes. The announcement notes that the property's original 2001 finishes present a "value-add opportunity" for the buyer. In plain terms: the new owner paid for a stable, below-market rent roll today, with the option to renovate units over time and move rents closer to what the market would bear. Whether that happens, and how fast, is the buyer's call — the announcement does not describe a renovation plan.

    What this is — and what it is not

    This is not an Opportunity Zone deal, as far as anyone has said. The announcement makes no mention of Opportunity Zones, tax incentives, or census tracts, and we are not going to dress it up as one. It is a private sale between two private investors, brokered the ordinary way. It belongs in this series for a different reason: it is a market signal about the housing economics of the city the tract sits in.

    Puyallup is a city of about 43,730 people with a median household income of roughly $97,826. That income figure is exactly why the 50% figure matters. When a median-income household looks at local mortgage costs roughly double the rent on a 1,041-square-foot townhome-style unit with a garage, renting stops being a way station and becomes the long-term housing answer for a large share of the workforce.

    The Opportunity Zone clock is running on a separate track. Why this sale matters for the housing spoke

    Capital is already pricing Puyallup rentals ahead of the zone window. A $25 million trade at $240,385 per unit, for a 2001-vintage property with original finishes, closed before the nominated tract is even certified. Whatever incentive capital arrives after January 1, 2027 will be entering a market where private buyers are already paying full freight for exactly the kind of The workforce-housing math is the tract math. The nominated tract sits near MultiCare Good Samaritan's campus, and the region's own planning says the area needs hundreds more hospital beds by 2036 — every one of them staffed by people who need a home they can afford on a working income. Heritage Square's rent-versus-mortgage gap is what that staffing need looks like when it shows up as a private market price.

    Below-market here is a market outcome, not a program. Nothing in the announcement describes affordability restrictions or income limits on Heritage Square's rents — the below-mortgage pricing is what this location, this product, and these finishes command. That makes it a useful contrast with Addison Grove, the 102-unit Puyallup community renting at 50–80% of area median income, which reached its affordability through a different route and was not an Opportunity Zone deal either. Puyallup's affordable supply comes from more than one mechanism, and it is worth keeping them straight.

    FAQ

    How much did Heritage Square in Puyallup sell for? Heritage Square sold for $25 million, or $240,385 per unit, according to Institutional Property Advisors, which announced the sale on October 22, 2026. The 104-unit community was built in 2001 and had never been offered for sale before.

    Why would an investor buy apartments with rents 50% below mortgage costs? Because the gap itself is the demand engine. IPA's Philip Assouad noted that rents approximately 50% below current local mortgage costs make the property an attractive alternative to homeownership, and that proximity to MultiCare Good Samaritan supports a stable renter base. The property's original finishes also give the buyer a value-add path if they choose to renovate.

    Is Heritage Square an Opportunity Zone project? No — not according to anything in the announcement, which never mentions Opportunity Zones. The buyer and seller are both private investors. Puyallup's nominated Opportunity Zone tract (53053073405) is a separate matter: nominated October 14, 2026, with certification expected by November 27, 2026 and a January 1, 2027 effective date if certified.

    Are Heritage Square's rents restricted affordable housing? The announcement does not say that. It gives no dollar rent figures and mentions no income limits or affordability restrictions — only the comparison that rents run about 50% below current local mortgage costs. The below-market level appears to be a market outcome, not a program requirement.


    Source: Yield PRO, "Heritage Square" — Institutional Property Advisors announcement of the sale, published October 22, 2026. https://yieldpro.com/2026/10/heritage-square-2/

  • The Name Is Back at South Hill. The Lease Says It’s a Test.

    The Name Is Back at South Hill. The Lease Says It’s a Test.

    If you grew up around here, the history needs no explaining. There was a store your parents took you to before Christmas that was not really a store — it was the whole season under one roof, aisles tall enough to make a kid feel small. That store went away in 2018, and most of us assumed the name went with it.

    This month, the name is going up over a door at South Hill Mall.

    Toys “R” Us is opening at South Hill as part of a holiday expansion — 120 new standalone stores the brand and its operator, Go! Retail Group, announced in September. A second Washington store is planned in Auburn. The South Hill store is expected to open in October and run through the holiday season.

    But read the lease before the headline, because the lease is the real story: at least one year, with an option to stay longer. That is not a comeback parade. That is a test — a famous name renting a room in Puyallup to find out whether the room still makes the business.

    How a dead chain learned to travel light

    The short version of the fall: Toys “R” Us filed for Chapter 11 in September 2017 carrying roughly $5 billion in debt, and closed its remaining U.S. stores in 2018.

    What happened next is the part worth understanding. The stores died; the name didn’t. Brand management firm WHP Global took a controlling stake in 2021 and stopped trying to rebuild the old chain. Instead it licensed the name into other people’s rooms: shops inside more than 400 Macy’s stores in 2022, airport locations, Navy Exchange stores (one sits at Bangor, for military families), and standalone stores run with Go! Retail Group starting in 2023.

    Go! is the operator behind this expansion, and the choice tells you the strategy. The Austin-based, family-owned company has run seasonal retail since 1993 — calendars, toy stores, pop-ups across six countries. Seasonal retail is a discipline: sign short, stock for the peak, open fast, know what the room has to earn. That playbook is now pointed at the most famous name in toys.

    Why a toy store is a different bet in 2026

    Why open a physical toy store in the age of next-day delivery? Because toys are one of the few categories where the trip itself is part of the product. Nobody’s childhood memory is of a package arriving. Kids don’t browse an algorithm well — they browse a room. A toy store sells discovery: the thing a kid didn’t know existed until it was at eye level, the thing a grandparent can’t choose off a search results page.

    It doesn’t beat Amazon at Amazon’s game, and it isn’t trying to. The bet is that there’s a second game: the Saturday trip, the birthday-party errand, the December walk-through. The old chain lost the first game carrying too much debt and too much real estate. This version only plays the second one.

    What South Hill gets out of the test

    For the mall, the timing is the value. The holiday quarter is when a shopping center either gives people a reason to make the drive or loses them to their phones, and a toy store is one of the strongest seasonal reasons there is. Every family that comes to South Hill for Toys “R” Us walks past every other store in the building in the weeks those stores live on.

    And the one-year term cuts both ways: the mall isn’t betting the building on this, and neither is the brand. Both sides signed a deal that lets everyone learn something cheaply — South Hill learns whether a nostalgia anchor still pulls traffic; the brand learns whether Puyallup families keep coming in February.

    The only question that matters now

    December will take care of itself — toy stores in December are like fireworks stands in July; the season does most of the work. The option on that lease gets exercised, or it doesn’t, based on months nobody writes press releases about.

    Watch February. Watch whether the store becomes a habit — the birthday gift bought on the way to the party, the ordinary Saturday with the grandkids. A store that only works when the whole country is buying toys is a pop-up with better signage. A store that works in March is a business.

    The name already proved it can survive bankruptcy, liquidation, and eight years of being a memory. What it’s testing at South Hill is smaller and harder: whether a famous name and a physical room, in a town that remembers both, still add up to a store people use.

    We’ll know in a year. That’s what the lease says — and for once, the lease and the truth are the same document.

    Sources: What Now Seattle; Toys “R” Us expansion announcement (PR Newswire); People; Retail TouchPoints.

  • The Shape of the Spike: The Fair, in Search — Part 1

    The Shape of the Spike: The Fair, in Search — Part 1

    When we wrote about what a million fair visitors leave behind, the claim underneath the piece was that the fair lives on phone screens as much as on the fairgrounds. Claims like that deserve receipts. So we pulled the receipts: Google Trends, day by day, for the whole run of the 2026 Washington State Fair — what Washington searched, and when.

    This is the first installment of The Fair, in Search: a case study in four parts, built entirely from the search record. And the record’s first surprise is the shape itself.

    How to read the numbers: Google Trends reports a relative index, not raw counts. 100 is the single biggest day in the window; every other day is scored against it. These figures are Washington State searches for the exact term “Puyallup Fair,” pulled for August 24 – October 12, 2026. Comparisons inside this one pull are apples-to-apples. (Methods and limits at the end — they matter.)

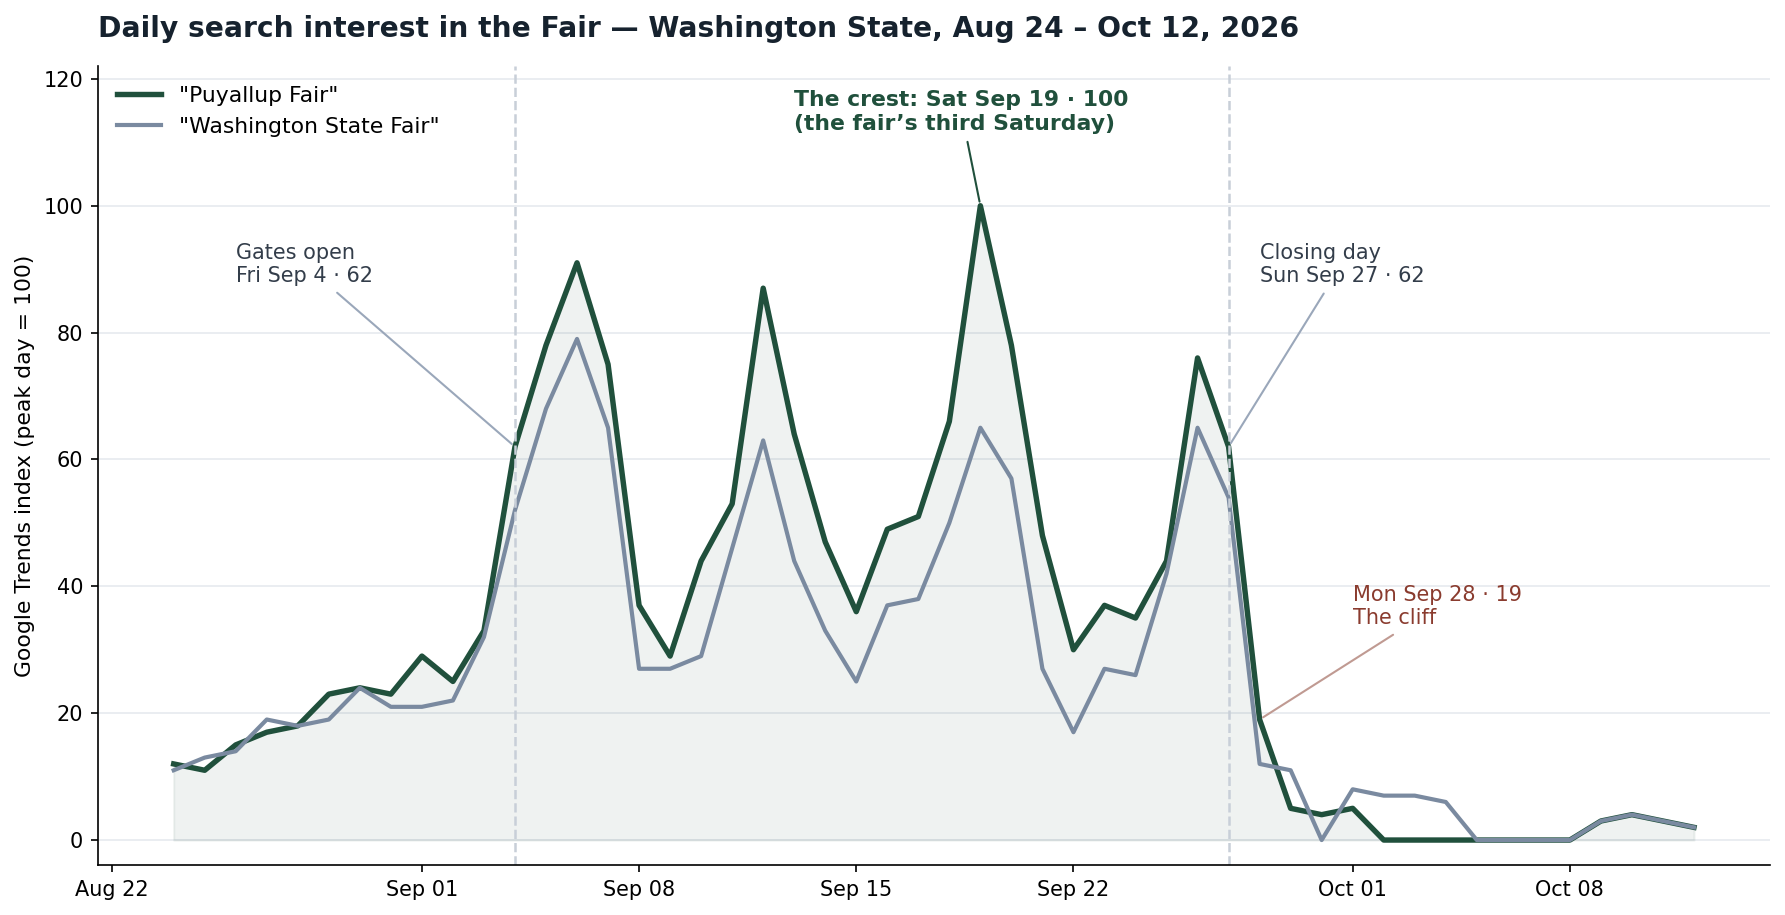
    Line chart of daily Google search interest for Puyallup Fair and Washington State Fair in Washington State, August 24 to October 12, 2026, showing a plateau with weekend peaks, a crest of 100 on Saturday September 19, and a sharp drop after closing day
    Daily search interest, Washington State. The fair does not spike and fade — it switches on, holds, and switches off.

    It is not a spike. It is a mesa.

    Everyone pictures event attention as a spike: a surge at opening, a long decay. The fair’s search curve does something else. Weekly average interest during the run barely moves — 59.4 in week one, 55.3 in week two, 56.3 in week three, and 60.7 across the closing stretch. For twenty-four days, the fair is simply on: a plateau of attention at roughly triple the pre-fair baseline (the late-August average was 20.9), with the lowest single day of the entire run — a rainy-season Wednesday, September 9, at 29 — still sitting above that baseline.

    A plateau changes the planning math. A spike rewards whoever shouts loudest on day one. A mesa rewards whoever is still findable, still accurate, still interesting on day seventeen.

    The teeth: Saturdays, ascending

    Riding on the plateau is a weekly rhythm with a clear beat. Across the fair’s run, weekend days averaged 79.5; weekdays averaged 46.4. The five biggest search days of the fair were all Saturdays and Sundays.

    And the Saturdays climb. First Saturday, September 5: 78. Second, September 12: 87. Third, September 19: 100 — the single biggest search day of the entire fair. The closing Saturday, September 26, comes back to 76. The crest of the fair is not its opening. It is the third weekend — after two weeks of photos, scones, concert clips, and coworkers saying you have to go. Search interest in the fair is built by the fair: word of mouth, made visible.

    Last year rhymes. In 2025’s search record, the peak day for “Puyallup Fair” was also a Saturday in the middle of the run — September 13 — not opening day. (Year-to-year levels can’t be compared directly; each pull is scaled to its own peak. But the shape repeating is the finding.) One year is an anecdote. Two is the start of a pattern worth planning around.

    Two names, two curves

    The fair has two names, and they behave differently. “Washington State Fair” — the official name — peaked early, at 79 on Sunday, September 6, opening weekend, and averaged 44.3 across the run. “Puyallup Fair” — the name people here actually use — averaged 57.5 and owned the crest. The formal name is how the fair is announced; the hometown name is how it is searched for once people are deciding to go. That split deserves its own installment, and it will get one.

    The cliff

    Then the fair ends, and the curve does the most honest thing in this whole dataset. Closing day, Sunday, September 27: 62 — still strong. Monday, September 28: 19. Tuesday: 5. By October 2: 0. The two weeks after closing average 3.0. There is no long tail, no nostalgic afterglow in search. The audience does not drift away from the fair; it is gone, the morning after, almost to zero.

    That cliff is the most useful number in this series for a local business. It means the conversion window is the run itself — the reviews, the signups, the second invitation have to be captured while the mesa holds, because the day after closing there is no residual attention to harvest. October’s work, which the afterglow piece described, starts from an audience you kept, not one you can still reach.

    What the shape tells a Puyallup business

    • Plan for the third Saturday, not just opening day. The biggest search day of the fair is mid-run. Staffing, inventory, hours, and your best offer should peak when the curve does — September 19, not September 4.
    • Weekends are the teeth. Search runs about 70% hotter on fair weekends than fair weekdays. If your public information is wrong anywhere, it is wrongest in effect on a Saturday.
    • The mesa forgives a slow start. Interest holds level for three-plus weeks. A business that fixes its profile, photos, or hours in week two still catches most of the run. A spike would punish that; a mesa doesn’t.
    • Capture during, because after is zero. The cliff is total. Whatever the fair is going to give you — reviews, names, regulars — it gives during the twenty-four days, or not at all.

    Next in this series: the intent map — what those million visitors actually searched for, week by week, from parking to scones. The mesa is the shape. What flows across it is the story.

    Methods: Google Trends daily data, geo = Washington State, pulled October 23, 2026 for the window August 24 – October 12, 2026; terms are exact search terms “Puyallup Fair” and “Washington State Fair.” Trends values are a relative index (peak = 100), not search counts. Separate pulls rescale to their own peaks, so the 2025 comparison is shape-only, and a separate June 2026 pull we ran was discarded for exactly that reason — levels from different pulls cannot be compared. Fair dates: September 4–27, 2026 (thefair.com). This is part one of “The Fair, in Search,” a Tygart Media case study; the companion piece is “The Fair Is Over. What Does a Million Visitors Leave Behind?”

  • AI Needs a Zoning Permit: Puyallup’s Data Center Question

    AI Needs a Zoning Permit: Puyallup’s Data Center Question

    Artificial intelligence feels weightless when you use it. It answers from nowhere, instantly, in a calm voice. But every answer is computed somewhere — in a building full of servers that draws serious power, drinks serious water, and has to sit on actual land inside somebody’s city limits.

    This summer, that somewhere came up for a vote-shaped discussion in Puyallup.

    The June 30 meeting

    At its June 30, 2026 study session, the Puyallup City Council took up Phase 2 of the city’s zoning map and code amendments — Package Six of the Development and Permitting Services work plan, presented by Senior Planner Kendall Wals. Most of the package was alignment work: making the zoning map match the adopted future land use map, updating mixed-use zones, weighing consolidation of the single-family RS zones, refreshing the manufacturing zones, and revising the Fair Park overlay.

    The council endorsed most of it and sent it forward to the Planning Commission. But on two items it deliberately slowed down: the single-family consolidation, and the proposed data center allowances — the question of where, and under what conditions, data centers should be permitted in Puyallup’s manufacturing and business park zones. On those, the council urged more public outreach and more analysis before anything moves.

    Residents at the session made the concerns concrete: traffic, infrastructure strain, and protections for the neighbors of facilities that run loud, bright, and around the clock. Those are not abstractions in a city where industrial land and neighborhoods have been growing toward each other for thirty years.

    The part nobody in the room could call hypothetical

    Puyallup is not deciding whether to admit its first data center. It already has one.

    Washington’s legislative auditor (JLARC), in its 2026 review of the state’s data center tax preference, lists exactly three owners who claimed the urban-county exemption — in Tukwila, in Kent, and Benaroya Capital, in Puyallup, whose facility opened in 2011 in a business park zoned for manufacturing and industrial activity. JLARC’s dry conclusion is also worth hearing in full: the tax preference “has had no influence” on where any of the three located. They all came before it existed, for their own reasons — power, land, fiber, and position in the corridor.

    So the Phase 2 question is not whether data centers belong in Puyallup. It is whether the next ones arrive under rules the city chose on purpose — with conditions on noise, power, water, and siting written in advance — or under whatever the current code happens to allow by default.

    The honest ledger both sides are arguing from

    What a data center brings: a very large construction project; a serious new property-tax and utility customer; a small number of permanent, well-paid technical jobs — few jobs per acre is the industry’s known arithmetic, and pretending otherwise insults everyone’s intelligence; and a tenant that does not leave when retail cycles turn.

    What it asks: power, at a scale that makes utilities plan around a single customer; water, in most designs, for cooling; land in the same industrial zones the city’s warehouse and manufacturing economy is competing for — the same corridor economy that is Puyallup’s growth story right now; and neighbors’ tolerance for generator testing, HVAC hum, and a building that produces almost no daily street life.

    Neither column is a caricature. The council’s June move — forward with the package, slower on this — reads like a body that can see both columns and declined to pretend the math was finished.

    What happens next, and what to watch

    The Phase 2 package is working through the Planning Commission phase, with the data center allowances carrying the council’s instruction for more outreach and analysis attached. That means hearings, a staff analysis worth reading when it lands, and eventually a council decision that will be one of the more consequential land-use calls of Puyallup’s decade — because it writes the rules before the applications arrive, not after.

    For local businesses, there is a quieter stake in this than the headlines suggest. Data centers are the physical plant of the AI services every small business in town is rapidly adopting. Whether that plant sits in our industrial zones — paying into our tax base, drawing on our power planning, answering to our code — or one freeway exit away in somebody else’s is a live local choice, being made this year, in meetings almost nobody attends.

    The AI era will be built out of zoning decisions like this one, in towns like this one. June 30 was Puyallup’s turn to start deciding. The record so far says the city chose to look harder before it chose — and that the rest of the decision is still in front of all of us.

    Update — October 23, 2026: the decision window is open

    Two weeks after the June 30 session, residents were back at the microphone. The July 14, 2026 council minutes record public commenters advocating a moratorium on zoning changes related to higher-tier data centers, raising the impacts of large facilities on nearby residents, and pressing the council on its process — the June caution, organized.

    And the calendar has caught up with the story. The city’s own published timeline for the Phase 2 amendments puts the Planning Commission public hearing in fall 2026, followed by council review and action, with council consideration of the package slated for October 2026. In other words: the decision this piece said was “still in front of all of us” is being made in the current window. When the hearing date posts and the staff analysis lands, this desk will cover both — the analysis the council asked for in June is the document that will tell us what “choosing on purpose” actually costs and pays.

    Sources: City of Puyallup City Council study session minutes, June 30, 2026 (Phase 2 zoning map and code amendments, Package Six; data center allowances among items flagged for more outreach and analysis); Citizen Portal meeting record, June 30, 2026; JLARC, “2026 Tax Preference Review: Data Centers in Urban Counties” (Benaroya Capital facility in Puyallup, opened 2011; tax preference found to have had no influence on siting); City of Puyallup 2026 DPS Work Plan overview; City Council minutes, July 14, 2026 (public comment on data centers); City of Puyallup zoning map & code updates project timeline (Phase 2: Planning Commission public hearing fall 2026, council review and action to follow). Part of Tygart Media’s Puyallup coverage.

  • The Fair Is Over. What Does a Million Visitors Leave Behind?

    The Fair Is Over. What Does a Million Visitors Leave Behind?

    For twenty days in September, Puyallup — a city of roughly 44,000 people — hosted on the order of a million visitors at the Washington State Fair. The fair ran September 4–27 on the 160-acre fairgrounds, and then, as it does every year, it packed up and left.

    Here is the question October asks every business in this town: what did the million leave behind?

    Not the obvious things — not the revenue spike, welcome as it was, and not the traffic, unmissed as it is. The durable residue. Because a million visitors is the largest audience any Puyallup business will ever be handed, and almost all of that audience interacted with this town through a phone screen before, during, or after they walked through a gate. What they left behind lives on those screens — and most of it expires if nobody tends it.

    What a million visitors actually deposits

    • Searches. For twenty days, people standing in Puyallup searched like locals: coffee near me, breakfast, parking, burgers, things to do after the fair. Those searches taught the platforms which Puyallup businesses answer local intent — and the businesses that showed up, with current hours and real photos, banked visibility that doesn’t vanish when the Ferris wheel comes down.
    • Reviews. Fair season is review season. Visitors review the restaurant that saved their rainy Saturday and the shop that treated their kids well — and those reviews are read for the next eleven months by the audience that matters more: the 44,000 of us who live here and the steady stream of people deciding whether Puyallup is worth a Saturday.
    • Photos and tags. A million people photographing their day puts this town’s storefronts, signs, and plates into more feeds in three weeks than a year of ordinary marketing. That imagery is findable, and it compounds.
    • Names and numbers. Every business that ran a fair-season list signup, a text club, a receipt offer, or a Spring Fair reminder hold now owns a small asset: permission to talk to people who already came once.

    The October work: converting a crowd into a clientele

    The fair’s economics tempt a business to treat September as weather — wonderful, uncontrollable, gone. The operators who win the fair treat it as the top of a funnel that runs all year. The conversion work is October work, and it is unglamorous:

    • Answer the reviews. All of them, especially the fair-season ones, while the visit is still warm in the reviewer’s mind. A thoughtful reply in October is read by everyone shopping you in December.
    • Fix what the crowd exposed. Fair traffic is a stress test: the hours that were wrong on your profile, the menu photo from 2023, the parking question answered nowhere. A million visitors just audited your public information for free. October is when you correct the findings.
    • Send the second invitation. The list you built gets its first real message now — not a coupon blast, an invitation: the fall menu, the local night, the thing residents get that fair crowds don’t. The fair proved people will come to Puyallup. Give them a reason that isn’t a Ferris wheel.
    • Speak to the 44,000. Residents watched the fair happen to their town for twenty days. The businesses that acknowledge locals in October — we saved you a seat now that the crowds are gone — earn the loyalty that carries the other eleven months.

    The date that makes this a strategy instead of a sentiment

    The fair has already posted its return: the Spring Fair runs April 9–11 and 16–18, 2027 — two weekends, a smaller and more local crowd, and the first big test of every October intention. Businesses that did the conversion work get to watch April behave differently: repeat faces, a warmer list, reviews that mention coming back.

    And the wheel keeps turning. September 2027’s million will arrive on schedule. The only question the fair ever really asks a Puyallup business is whether it treats the crowd as weather or as an audience it intends to keep.

    A million people came to our town this fall. What they left behind is sitting in your reviews, your search profile, and your signup list right now — quietly expiring or quietly compounding, depending on what October looks like.

    The Washington State Fair ran September 4–27, 2026 at the Washington State Fair Events Center in Puyallup; the fair draws on the order of a million visitors across its run. The Spring Fair is scheduled April 9–11 and 16–18, 2027 (thefair.com). This piece is part of Tygart Media’s Puyallup coverage, alongside the Opportunity Zone series and the new farmers market story.

  • The Playbook: Four Seats, One Deadline

    The Playbook: Four Seats, One Deadline

    This is the final piece in the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters — with the math, the map, the hospital play, the housing play, the business play, and the honest caveats before it. Those explained. This one assigns seats.

    An Opportunity Zone designation is not an event. It is the start of a ten-year game with four kinds of players, and the towns that got results from the first version were the ones where all four showed up early and knew their parts.

    Tract 53053073405’s game starts January 1, 2027. Here is the playbook, seat by seat — what to do now, what to do at go-live, and the dates nobody gets to miss.

    Seat one: property owners inside the line

    You hold the scarcest asset in this story: the ground itself. The designation just made your property legible to a class of capital that could not see it last month. Moves, in order:

    • Confirm you’re in. Check your address against the official map (the State Department of Commerce maintains the nomination map; Treasury’s certified map is final). Not a neighbor’s assurance — the map.
    • Know your basis split. For any building, the number that decides your future conversations is its basis excluding land, because the substantial-improvement rule (invest at least that much again) is how investors will classify your property: renovation candidate or new-build site. Get it from your records or your CPA before anyone quotes you a strategy.
    • Decide your posture before the outreach knocks. Sell, partner with a developer, or develop it yourself with fund equity — all three are legitimate, and they are not interchangeable. Owners who choose get terms; owners who drift get offers.
    • Use the news window. The designation is a story right now, and certification in November will make it one again. Attention is a pricing input. The next twelve months are when your ground is most visible to the most qualified buyers and partners it will ever have.

    Seat two: investors holding capital gains

    Your clock is the loudest one in the program. The money piece has the arithmetic; here is the calendar discipline:

    • The regime question comes first. Money invested in a fund by December 31, 2026 lives under the expiring 1.0 rules, with deferred tax due almost immediately. The same gain invested on or after January 1, 2027 gets the full 2.0 runway: five-year rolling deferral, 10% step-up, ten-year exclusion. For most investors with late-2026 gains, the 180-day window runs into 2027 — use it deliberately rather than rushing into the dying program.
    • Underwrite the project, then the tax. The benefit is worth roughly a quarter of the gain in the best case. The difference between a good project and a bad one is worth more than that. Every credible fund will show you the underlying deal; if the deal doesn’t work without the tax story, it doesn’t work.
    • Local funds and single-project vehicles exist. Pierce County’s first-era buildings were financed by a specialist QOZ firm and a national opportunity fund platform. The channel is proven here. What will be scarce in 2027 is ready projects inside this tract — which is why seat one and seat four matter to you.
    • Paper up early. Fund subscriptions, deferral elections (Form 8997), and the annual reporting habit all run smoother set up before the gain’s clock starts, with a CPA who has done OZ work before.

    Seat three: businesses in — or willing to be in — the tract

    Your door is the least-used one in the program, which makes it the widest open:

    • Run the tests on paper first. Seventy percent of tangible property in the zone, 50% of gross income from active conduct in the zone, under 5% in passive financial assets. If your operation — or the expansion you’re planning — can pass those on a whiteboard, it’s worth a professional structuring conversation.
    • Time the entity before the money. QOZ Business status is structural: the fund must hold equity in the qualifying entity, and retrofitting an old structure is harder than forming the right one. Counsel first, capital second.
    • Think in the hospital’s supply chain. The corridor’s demand engine is a 20-year hospital expansion. Businesses that serve that campus — health services, childcare, trades, food — are pitching into documented demand, not hope.
    • Prepare to be found. Funds that do operating-company deals are rare and they scout. A business with clean books, a written growth plan, and a zone address is findable in a way a handshake operation is not.

    Seat four: the City

    The City’s part is already scripted in its own announcement: an outreach phase to property owners, developers, investors, and businesses in the designated area. The playbook adds only emphasis, drawn from what worked and failed elsewhere in 1.0:

    • Publish the pipeline. The towns that attracted quality capital made their priorities legible — priority sites, desired product types, process contacts — in public, where a fund analyst in another state could find them at midnight. Legibility is economic development now.
    • Make certification a moment. When Treasury certifies (due by November 27, 2026), that is the tract’s one guaranteed news cycle before go-live. It is the cheapest investor-relations event the City will ever be handed.
    • Keep the front door staffed. A named contact and a predictable pre-application process are worth more than incentives layered on top of the federal one. Capital flees confusion faster than it flees cost.
    • Report back to the town. The 2.0 era will generate fund-level data. A city that narrates its own tract’s record — projects, jobs, product mix — keeps public trust through the decade and keeps the next designation (2036’s map) within reach.

    The dates box

    • October 14, 2026 — Governor Ferguson’s nomination announced; Puyallup tract 53053073405 among Washington’s 99.
    • By November 27, 2026 — Treasury certification decisions due. The hub updates the day it lands.
    • December 31, 2026 — last day for investments under OZ 1.0 rules; the 2018-era deferral ends.
    • January 1, 2027 — the designation takes effect. OZ 2.0 investments begin; the ten-year clock starts.
    • December 31, 2028 — the original 2018 zone map expires nationally.
    • December 31, 2036 — this designation ends. Projects funded under it live out their own timelines.

    One table, four seats

    Strip the series down and it says one thing: the federal government has put a price on patience, and pointed it at a specific piece of Puyallup. Owners hold the ground. Investors hold the clocks. Businesses hold the jobs. The City holds the map and the microphone.

    None of the four can substitute for another — and the tract doesn’t need any of them to be heroes. It needs them to be ready at the same time, in January, when the window opens.

    The record of what they do with it will be kept on the hub, scoreboard and all. It starts at zero. It won’t stay there.

    Sources: City of Puyallup news release, October 14, 2026 (nomination, announced outreach phase); Rev. Proc. 2026-14 certification timeline (decisions by November 27, 2026); P.L. 119-21 §70421 (2.0 effective January 1, 2027; designation period through December 31, 2036; 2018 map expiry December 31, 2028); IRS Forms 8996/8997 fund and investor reporting; 2026 Opportunity Zones Handbook (QOZ Business tests; substantial improvement). This article is general information, not tax, legal, or investment advice.

  • The Honest Caveats: What Opportunity Zones Got Wrong, and What 2.0 Fixed

    The Honest Caveats: What Opportunity Zones Got Wrong, and What 2.0 Fixed

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters. The other pieces make the case — the math, the map, the hospital, the housing, the businesses. This piece is the one that makes the rest believable: everything the first version of this program got wrong, stated plainly.

    A series that only cheers for its subject is advertising. This tract deserves a chronicler, not a cheerleader — and the credibility of everything else on this site rests on this page being as honest as the others are enthusiastic.

    So: Opportunity Zones 1.0 had real failures. Some were design flaws Congress has now fixed. Some were not flaws at all, but the predictable behavior of capital given weak instructions. And some are still waiting, unfixed by any statute, for local people to decide.

    What 1.0 actually did

    The scale was real: an estimated $100 billion of equity moved into roughly 5,600 neighborhoods under the first program — one of the largest place-based capital flows in American history. The Astor and The Moraine, ten miles from the tract, are what the good version looked like: a landmark saved, workforce housing built.

    But the distribution was the scandal. One widely cited program review (Columbia Threadneedle’s analysis of the first era) found that more than a quarter of the equity raised landed in the top sliver of neighborhoods by measures of existing advantage — places whose recovery was already underway before the designation arrived. Critics catalogued the product mix that followed: luxury apartments, hotels, and self-storage facilities wearing a distressed-community incentive. Every state had its example of a zone drawn around a neighborhood that plainly didn’t need the help.

    The mechanism behind the skew is worth understanding, because it’s the thing to watch here. Governors in 2018 could nominate tracts merely adjacent to qualifying low-income tracts — the contiguous-tract rule. Money, being money, preferred the safest version of eligible: the tract next to the hot neighborhood rather than the genuinely struggling one. The incentive paid the same either way, so it bought the safer thing.

    And over it all sat a quieter failure: 1.0 required almost no reporting. Funds self-certified, and the public record of what the money built, whom it employed, and who benefited stayed thin for years. That vacuum served nobody well — it let boosters claim miracles without evidence and critics claim pure giveaway without it either. A program this size, running on this little data, was a choice, and it was the wrong one.

    What 2.0 fixed — genuinely

    The 2025 law reads, in places, like a point-by-point reply to the critics:

    • Tighter eligibility. The income test dropped from 80% to 70% of area median family income (or a 20% poverty rate with its own income cap). Fewer tracts qualify — roughly 6,500 expected nationally, down from 8,764.
    • The side door is closed. No more contiguous-tract nominations. Every tract qualifies on its own numbers. This is the single most important repair in the law, because it removes the mechanism that produced the worst headlines.
    • A cap with teeth. Governors may nominate only up to 25% of their eligible tracts — scarcity that forces actual prioritization. Washington’s 152-applications-for-99-slots process is what that looks like in practice.
    • Reporting is now law. Funds must report their holdings and activity in a structured way, so the 2.0 era can be argued from records instead of impressions.
    • The map expires. Designations now renew every ten years. A tract that no longer needs help doesn’t keep the incentive forever, and a newly struggling one isn’t locked out for a generation.
    • The deferral cliff is gone. The rolling five-year deferral (see the money piece) removes the decaying-incentive problem that distorted 1.0’s later years.

    Puyallup’s tract is a creature of the repaired rules: it qualified at the stricter test, on its own numbers, through a competitive state process. That does not make it virtuous. It makes it eligible under a better-designed screen. The distinction matters, and this series will keep making it.

    What no statute can fix

    Here is the part that lands on us.

    The incentive pays gain-holders, first and always. The direct beneficiary of every Opportunity Zone dollar is an investor with a capital gain. The community’s return — jobs, housing, services, tax base — is a downstream consequence of what that money builds. A program designed this way can be a powerful development tool; it cannot be a direct anti-poverty program, and judging it as one guarantees disappointment. Judge it instead on the buildings and businesses: are they the ones the tract needed?

    Success has a price, and the price is rent. If the corridor works — hospital growing, housing building, businesses opening — land and housing costs inside and around the tract rise. That is what success looks like in a market, and it squeezes the very residents the eligibility numbers describe. No provision of §1400Z-2 manages that. Local tools do: the affordability layering in the housing piece (the Addison Grove model), permitting choices, and whether anyone in authority is watching the rent line as carefully as the investment line. This series will watch both.

    Product choice is local. The tax code cannot distinguish a workforce apartment building from a storage facility with the same return profile. People can. The City’s announced outreach phase, the projects owners choose to bring, and the public’s attention are the actual quality control. Towns that treated their zones as spectator sports got spectator results.

    The watch list for this tract

    So the series ends its caveats where it will spend the next ten years: watching specifics. For tract 53053073405, the questions that matter, in order:

    • What is the first project — its product type, its rent or price point, its employer count? The first announcement sets the tract’s tone for every funder watching.
    • Do local owners sell, partner, or build? Each path puts the value in different hands.
    • Does any operating business get funded, or only buildings? The least-used door is the jobs test.
    • When 2.0’s reporting starts publishing, what does the fund-level record for this tract actually say? We will read it here, in public, against this page’s questions.
    • What happens to rents in and around the tract as investment lands? The success metric and the warning light are the same number, read carefully.

    The first program’s honest verdict is: powerful tool, loosely aimed, poorly measured. The second program fixed the aim and the measuring. What it cannot fix is whether the people in the place are paying attention.

    In this town, at least, somebody is. That’s the whole point of the record we’re keeping on the hub.

    Sources: Opportunity Zone 1.0 capital estimates (~$100B across ~5,600 neighborhoods) via City of Spokane / Spokane Journal of Business reporting; Columbia Threadneedle Opportunity Zones program review (concentration of equity in advantaged neighborhoods); OZ 2.0 reforms under P.L. 119-21 §70421 as summarized by the Federal Reserve Community Development function and the 2026 Opportunity Zones Handbook (70% AMI test, contiguous-tract removal, 25% nomination cap, decennial remap, fund reporting). This article is general information, not tax, legal, or investment advice.

  • The Business Play: The Opportunity Zone Door Nobody Walks Through

    The Business Play: The Opportunity Zone Door Nobody Walks Through

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters, alongside The New Opportunity Zone Math, Between Two Growth Centers, The Hospital Play, and The Housing Play. This piece covers the door almost nobody walks through: the zone funds businesses, not just buildings.

    Ask a room of business owners what an Opportunity Zone is and you’ll hear about apartment buildings. The real estate story ate the whole program’s public image — partly because buildings are easy to photograph, and partly because most funds found property easier to underwrite than companies.

    But the statute has a second door, and for a tract anchored by a growing hospital, it may be the more important one: a Qualified Opportunity Fund can buy equity in an operating business inside the zone — a Qualified Opportunity Zone Business. Growth capital, from investors whose tax benefit requires them to stay for ten years, for companies that locate and operate inside the line.

    How a business qualifies, in plain English

    The rules are real, and they are tests, not vibes. Reduced to their working core, an operating business qualifies when:

    • Its tangible property is in the zone. At least 70% of the business’s tangible property — owned or leased — must be qualified zone business property: property acquired after 2017 (and, under 2.0, aligned to the new designation period), used in the zone, and either new or substantially improved.
    • Its income is earned in the zone. At least 50% of the business’s gross income must come from the active conduct of the business inside the zone. A company can’t just rent a mailbox in the tract and operate in Bellevue.
    • It is actually a business. Less than 5% of its assets can sit in stocks, bonds, and other nonqualified financial property (ordinary working capital and reasonable reserves aside), a substantial portion of any intangible property must be used in the zone’s active conduct, and the statute excludes a short list of “sin” categories — golf courses, gambling facilities, liquor stores, and their relatives need not apply.
    • The fund’s money works on a clock. Businesses get a working-capital safe harbor — up to 31 months under a written plan to deploy the capital — which is the provision that makes expansions and build-outs practical instead of theoretical.

    An owner reading that list will notice something: these tests describe a business that is genuinely there — property there, income there, operations there. That is not a loophole shape. That is the program working as designed.

    Why almost nobody uses this door

    Three honest reasons. First, funds are mostly built by real estate people; underwriting an operating company’s management and market is a different skill than underwriting a building, and most QOF platforms never acquired it. Second, the compliance testing is ongoing — a building stays qualified by standing there, while a business must keep passing its tests as it operates, hires, and grows. Third, the deal sizes are often smaller than fund economics prefer.

    The result is a strange gap: the program’s most job-creating mechanism is its least used. For Puyallup, that gap is an opportunity, because the tract’s demand story — a $430 million hospital expansion — generates business demand that buildings alone don’t answer.

    The businesses this tract is actually calling for

    Read the hospital’s ecology as a business list, because that is what it is:

    • Healthcare services around the campus — home health agencies, outpatient therapy, imaging and lab services, durable medical equipment, medical staffing. Businesses whose customers and referral sources are a short drive from the tract, whose workforce is local, and whose income is earned where their people work.
    • Childcare built for shift work — an operating business (not just a building) serving the hospital’s three-shift workforce, the single most-cited unmet need around every growing hospital campus in America.
    • Trades and light production — the corridor’s existing commercial fabric is full of service businesses, fabricators, and suppliers positioned between the Port of Tacoma’s freight economy and the South Hill retail engine; expansion-stage companies in that fabric are natural candidates for growth equity that doesn’t come with a bank’s five-year leash.
    • Food and daily services — the unglamorous, durable layer that a campus population of staff, patients, and visitors supports around the clock.

    What it means for an owner

    For a business owner inside the tract — or one willing to locate a real operation there — the QOF structure offers something bank debt doesn’t: equity whose owners are rewarded for staying. The fund’s full tax benefit requires a ten-year hold, which makes its capital structurally patient. The trade is real, too: equity means dilution and a partner, where debt means payments and a deadline. Which one fits depends on the business, the growth plan, and the owner’s appetite for company.

    The realistic paths in:

    • Expansion capital. An existing Pierce County business opens its growth location — second site, larger facility, new service line — inside the tract, structured so the fund’s equity funds the expansion entity.
    • Relocation with substance. A business moves real operations — property, people, income — into the zone and raises fund equity against the move and build-out.
    • Founder-stage location. A new business in the hospital’s service ecology chooses the tract as its home base from day one, raising patient equity instead of stacking early debt.

    Each path needs the same unglamorous first steps: confirm the address is inside tract 53053073405 on the official map, and structure the entity with counsel and a CPA who has actually read §1400Z-2 — before money moves, not after. The tests are passable; they are not forgiving of improvisation.

    The number that keeps this honest

    Nationally, the overwhelming share of the estimated $100 billion that flowed through Opportunity Zone 1.0 went to real estate. The business door stood open the whole time, comparatively unused. If Puyallup’s tract ends up funding even a handful of operating companies — employers, not just addresses — it will have used the program better than most of the map did.

    Buildings are what the zone is famous for. Businesses are what a town actually runs on. The scoreboard on the hub has a line waiting for the first one.

    Sources: IRC §1400Z-2 and QOZ Business requirements as summarized in the 2026 Opportunity Zones Handbook (70% tangible property test; 50% of gross income from active conduct in the zone; under 5% nonqualified financial property; excluded business categories; 31-month working capital safe harbor); Opportunity Zones 2.0 provisions under P.L. 119-21; Opportunity Zone 1.0 capital estimates (~$100B, predominantly real estate) via industry and city reporting. This article is general information, not tax, legal, or investment advice.

  • The Housing Play: Three Pierce County Models, One Obvious Next Site

    The Housing Play: Three Pierce County Models, One Obvious Next Site

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters, alongside The New Opportunity Zone Math, Between Two Growth Centers, and The Hospital Play. This piece is housing — and unlike most housing commentary, every model in it is a real building within ten miles of the tract.

    Housing is where Opportunity Zone money does its most visible work, and its most argued-about. It is also where Pierce County has an unusual advantage in this conversation: we don’t have to speculate about what OZ housing looks like. It is already built here, in two different flavors — and Puyallup itself just proved it can close a sophisticated housing deal in 90 days.

    Three buildings. Three capital models. One obvious next site.

    Model one: The Astor — the historic conversion (Tacoma)

    In downtown Tacoma, the Washington Building stood as a 1925 office tower, a landmark running out of economic lives. Unico Properties partnered with Pinnacle Partners — a firm that exists specifically to invest Qualified Opportunity Zone funds — and converted it into The Astor: 156 apartments, delivered in July 2022.

    The lesson for Puyallup is the mechanism. Adaptive reuse of an existing building under OZ rules runs on the substantial improvement test: within 30 months, the project must invest at least as much in improving the building as the building itself was worth (its basis, excluding the land). Buy a tired building for a basis of $800,000 and the rule requires another $800,000-plus of real construction into it. The rule is why OZ money loves sturdy old shells — the incentive literally pays for resurrection, not cosmetics.

    The tract between Downtown and South Hill has exactly this kind of stock: older commercial buildings with good bones and tired economics. The Astor is the proof, fifteen minutes away, that QOZ capital will underwrite their second lives.

    Model two: The Moraine — workforce housing, new build (Tacoma Hilltop)

    On Tacoma’s Hilltop, Ethos Development and Catalyst Opportunity Funds built The Moraine: 160 units of workforce housing — new construction, aimed at the people who staff a city’s hospitals, schools, and services rather than at the top of the rent market. It won CoStar’s 2025 Multifamily Development of the Year for the Seattle market.

    Workforce housing is the product OZ 2.0’s redesign quietly favors: the tightened eligibility tests push funds toward tracts with genuine need, and the new reporting requirements mean the “who lives there” question now gets asked in public. The Moraine shows the product can also be the best building in its market — workforce rents and an award-winning project are not a contradiction.

    For Puyallup, connect this model to the hospital play: Good Samaritan’s expansion will hire in waves for twenty years. Those hires are the Moraine’s tenant profile, and housing built for them — near the campus, at workforce rents — is the tract’s most defensible residential thesis.

    Model three: Addison Grove — the 90-day close (Puyallup, not OZ)

    The third building is the one skeptics should sit with. Addison Grove, right here in Puyallup, is 102 apartments for families earning 50–80% of area median income (90 of the 102 homes are reserved below 60% of AMI), developed by Great Expectations. It is not an Opportunity Zone project — its engine is the Washington Family Housing Fund, created by Ballmer Group with the Washington State Housing Finance Commission, which put in a $13.41 million subordinate forgivable loan. From application to closing: 90 days.

    Addison Grove matters to this series for three reasons. First, it proves Puyallup’s machinery works — land, entitlements, and a sophisticated capital stack, executed fast. Second, it proves local absorption: affordable and workforce product here leases into real demand, not projections. Third, it sets the honest contrast: where OZ equity is return-seeking capital that needs the math in the money piece to work, the Family Housing Fund is concessionary capital that optimizes for affordability per dollar. Different engines, both real.

    How the three models stack over one tract

    The mistake is treating these as competitors. Over a ten-year designation, a healthy tract uses all three:

    • Conversions (Astor model) for the older buildings the substantial-improvement rule fits — QOZ equity, market and workforce rents, historic fabric saved instead of scraped.
    • New workforce buildings (Moraine model) on the vacant and underutilized parcels the City’s application emphasized — QOZ equity again, aimed at the hospital-and-corridor workforce.
    • Layered affordable projects (Addison Grove model) where deeper affordability is the goal — concessionary and public capital in the stack, with OZ equity able to sit alongside other sources where a project is structured for it.

    That layering point is the one honest housing economists insist on, and this series will too: tax-advantaged equity on its own generally underwrites market and workforce rents. The deeper affordability — the 50–60% AMI homes — usually arrives when other capital takes the subordinated, patient position, exactly as the Family Housing Fund did. OZ 2.0’s reporting makes it harder to blur that distinction, which is a feature.

    What would actually get built first

    If the Pierce County record is the guide, the tract’s first housing moves are the Astor and Moraine plays, not the mega-project: an older building with the right basis math, converted; a vacant parcel near the corridor, built to workforce rents; both marketed to the workforce the hospital is hiring and the two growth centers already employ.

    The demand is documented — a 249-bed regional shortfall being built against, two designated growth centers, a fair that imports a million visitors a year past these blocks. The models are standing ten miles apart, visible from the freeway. The capital mechanism switches on January 1, 2027.

    What Puyallup adds, when the first project is announced, gets recorded on the hub’s scoreboard — which today still reads zero, and won’t for long.

    Sources: Unico Properties (The Astor — 156 units, Washington Building adaptive reuse with Pinnacle Partners, delivered July 2022); Catalyst Opportunity Funds (The Moraine — 160 workforce units with Ethos Development; CoStar 2025 Multifamily Development of the Year, Seattle market); Propmodo / Puget Sound Business Journal (Addison Grove — 102 units at 50–80% AMI, Washington Family Housing Fund $13.41M subordinate forgivable loan, 90-day close, developer Great Expectations); IRS/IRC §1400Z-2 substantial improvement standard (100% of building basis ex-land within 30 months, urban). This article is general information, not tax, legal, or investment advice.