Author: William Tygart

  • The Shape of the Spike: The Fair, in Search — Part 1

    The Shape of the Spike: The Fair, in Search — Part 1

    When we wrote about what a million fair visitors leave behind, the claim underneath the piece was that the fair lives on phone screens as much as on the fairgrounds. Claims like that deserve receipts. So we pulled the receipts: Google Trends, day by day, for the whole run of the 2026 Washington State Fair — what Washington searched, and when.

    This is the first installment of The Fair, in Search: a case study in four parts, built entirely from the search record. And the record’s first surprise is the shape itself.

    How to read the numbers: Google Trends reports a relative index, not raw counts. 100 is the single biggest day in the window; every other day is scored against it. These figures are Washington State searches for the exact term “Puyallup Fair,” pulled for August 24 – October 12, 2026. Comparisons inside this one pull are apples-to-apples. (Methods and limits at the end — they matter.)
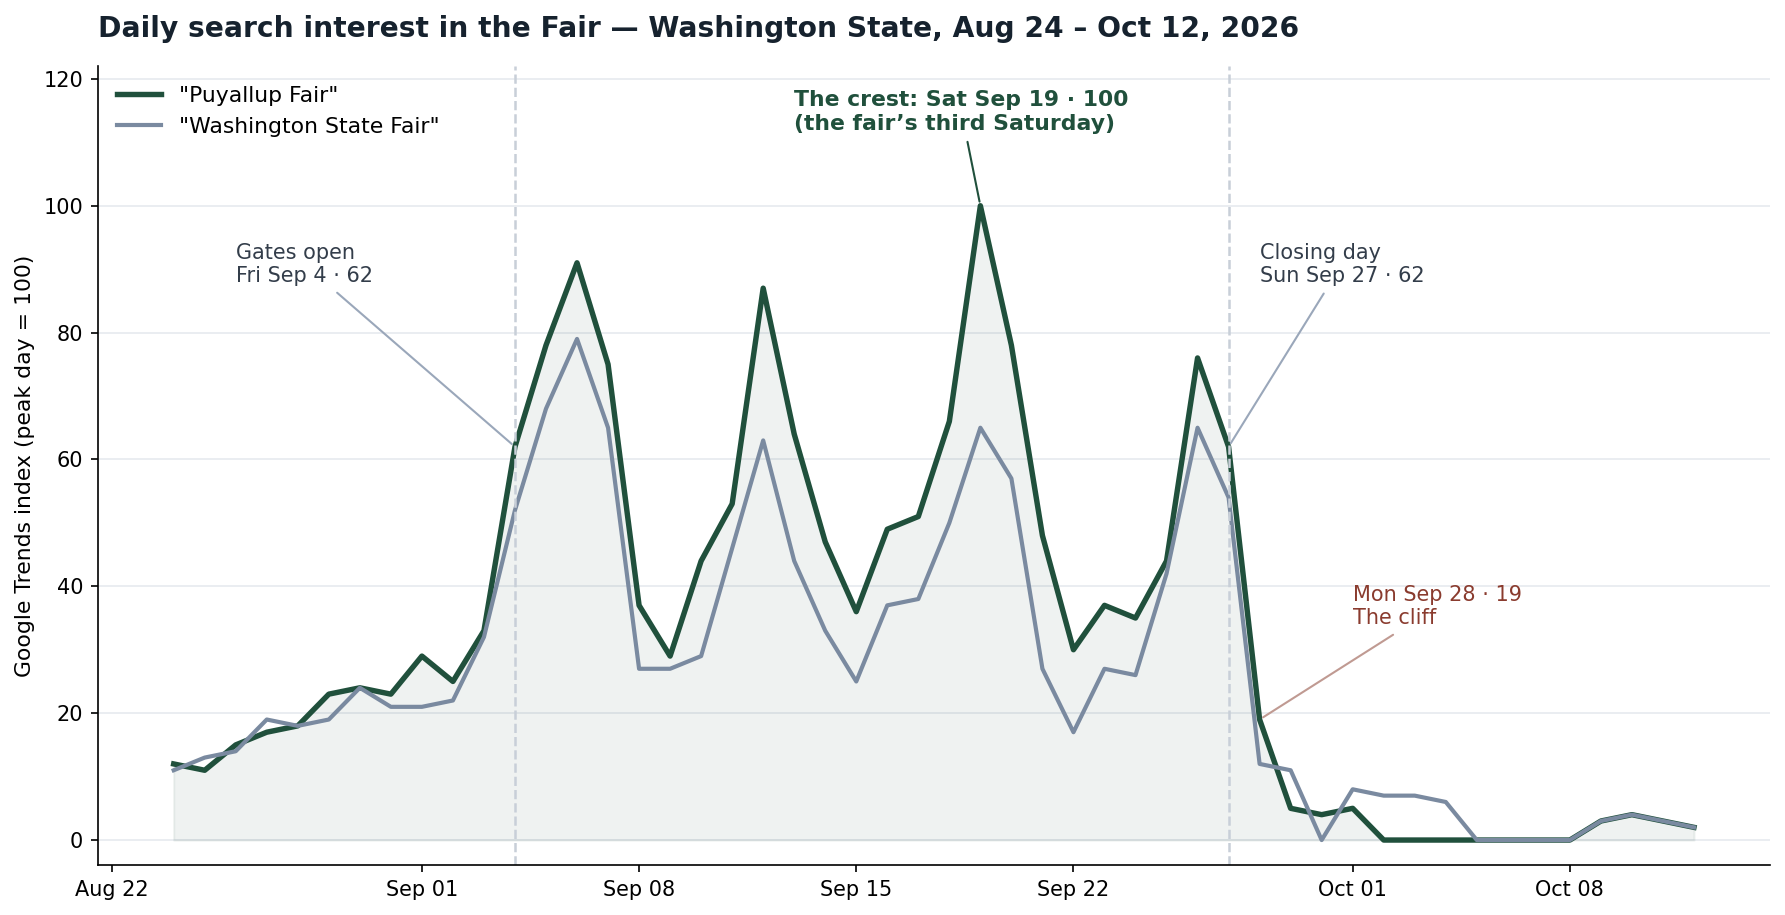
    Line chart of daily Google search interest for Puyallup Fair and Washington State Fair in Washington State, August 24 to October 12, 2026, showing a plateau with weekend peaks, a crest of 100 on Saturday September 19, and a sharp drop after closing day
    Daily search interest, Washington State. The fair does not spike and fade — it switches on, holds, and switches off.

    It is not a spike. It is a mesa.

    Everyone pictures event attention as a spike: a surge at opening, a long decay. The fair’s search curve does something else. Weekly average interest during the run barely moves — 59.4 in week one, 55.3 in week two, 56.3 in week three, and 60.7 across the closing stretch. For twenty-four days, the fair is simply on: a plateau of attention at roughly triple the pre-fair baseline (the late-August average was 20.9), with the lowest single day of the entire run — a rainy-season Wednesday, September 9, at 29 — still sitting above that baseline.

    A plateau changes the planning math. A spike rewards whoever shouts loudest on day one. A mesa rewards whoever is still findable, still accurate, still interesting on day seventeen.

    The teeth: Saturdays, ascending

    Riding on the plateau is a weekly rhythm with a clear beat. Across the fair’s run, weekend days averaged 79.5; weekdays averaged 46.4. The five biggest search days of the fair were all Saturdays and Sundays.

    And the Saturdays climb. First Saturday, September 5: 78. Second, September 12: 87. Third, September 19: 100 — the single biggest search day of the entire fair. The closing Saturday, September 26, comes back to 76. The crest of the fair is not its opening. It is the third weekend — after two weeks of photos, scones, concert clips, and coworkers saying you have to go. Search interest in the fair is built by the fair: word of mouth, made visible.

    Last year rhymes. In 2025’s search record, the peak day for “Puyallup Fair” was also a Saturday in the middle of the run — September 13 — not opening day. (Year-to-year levels can’t be compared directly; each pull is scaled to its own peak. But the shape repeating is the finding.) One year is an anecdote. Two is the start of a pattern worth planning around.

    Two names, two curves

    The fair has two names, and they behave differently. “Washington State Fair” — the official name — peaked early, at 79 on Sunday, September 6, opening weekend, and averaged 44.3 across the run. “Puyallup Fair” — the name people here actually use — averaged 57.5 and owned the crest. The formal name is how the fair is announced; the hometown name is how it is searched for once people are deciding to go. That split deserves its own installment, and it will get one.

    The cliff

    Then the fair ends, and the curve does the most honest thing in this whole dataset. Closing day, Sunday, September 27: 62 — still strong. Monday, September 28: 19. Tuesday: 5. By October 2: 0. The two weeks after closing average 3.0. There is no long tail, no nostalgic afterglow in search. The audience does not drift away from the fair; it is gone, the morning after, almost to zero.

    That cliff is the most useful number in this series for a local business. It means the conversion window is the run itself — the reviews, the signups, the second invitation have to be captured while the mesa holds, because the day after closing there is no residual attention to harvest. October’s work, which the afterglow piece described, starts from an audience you kept, not one you can still reach.

    What the shape tells a Puyallup business

    • Plan for the third Saturday, not just opening day. The biggest search day of the fair is mid-run. Staffing, inventory, hours, and your best offer should peak when the curve does — September 19, not September 4.
    • Weekends are the teeth. Search runs about 70% hotter on fair weekends than fair weekdays. If your public information is wrong anywhere, it is wrongest in effect on a Saturday.
    • The mesa forgives a slow start. Interest holds level for three-plus weeks. A business that fixes its profile, photos, or hours in week two still catches most of the run. A spike would punish that; a mesa doesn’t.
    • Capture during, because after is zero. The cliff is total. Whatever the fair is going to give you — reviews, names, regulars — it gives during the twenty-four days, or not at all.

    Next in this series: the intent map — what those million visitors actually searched for, week by week, from parking to scones. The mesa is the shape. What flows across it is the story.

    Methods: Google Trends daily data, geo = Washington State, pulled October 23, 2026 for the window August 24 – October 12, 2026; terms are exact search terms “Puyallup Fair” and “Washington State Fair.” Trends values are a relative index (peak = 100), not search counts. Separate pulls rescale to their own peaks, so the 2025 comparison is shape-only, and a separate June 2026 pull we ran was discarded for exactly that reason — levels from different pulls cannot be compared. Fair dates: September 4–27, 2026 (thefair.com). This is part one of “The Fair, in Search,” a Tygart Media case study; the companion piece is “The Fair Is Over. What Does a Million Visitors Leave Behind?”
  • AI Needs a Zoning Permit: Puyallup’s Data Center Question

    AI Needs a Zoning Permit: Puyallup’s Data Center Question

    Artificial intelligence feels weightless when you use it. It answers from nowhere, instantly, in a calm voice. But every answer is computed somewhere — in a building full of servers that draws serious power, drinks serious water, and has to sit on actual land inside somebody’s city limits.

    This summer, that somewhere came up for a vote-shaped discussion in Puyallup.

    The June 30 meeting

    At its June 30, 2026 study session, the Puyallup City Council took up Phase 2 of the city’s zoning map and code amendments — Package Six of the Development and Permitting Services work plan, presented by Senior Planner Kendall Wals. Most of the package was alignment work: making the zoning map match the adopted future land use map, updating mixed-use zones, weighing consolidation of the single-family RS zones, refreshing the manufacturing zones, and revising the Fair Park overlay.

    The council endorsed most of it and sent it forward to the Planning Commission. But on two items it deliberately slowed down: the single-family consolidation, and the proposed data center allowances — the question of where, and under what conditions, data centers should be permitted in Puyallup’s manufacturing and business park zones. On those, the council urged more public outreach and more analysis before anything moves.

    Residents at the session made the concerns concrete: traffic, infrastructure strain, and protections for the neighbors of facilities that run loud, bright, and around the clock. Those are not abstractions in a city where industrial land and neighborhoods have been growing toward each other for thirty years.

    The part nobody in the room could call hypothetical

    Puyallup is not deciding whether to admit its first data center. It already has one.

    Washington’s legislative auditor (JLARC), in its 2026 review of the state’s data center tax preference, lists exactly three owners who claimed the urban-county exemption — in Tukwila, in Kent, and Benaroya Capital, in Puyallup, whose facility opened in 2011 in a business park zoned for manufacturing and industrial activity. JLARC’s dry conclusion is also worth hearing in full: the tax preference “has had no influence” on where any of the three located. They all came before it existed, for their own reasons — power, land, fiber, and position in the corridor.

    So the Phase 2 question is not whether data centers belong in Puyallup. It is whether the next ones arrive under rules the city chose on purpose — with conditions on noise, power, water, and siting written in advance — or under whatever the current code happens to allow by default.

    The honest ledger both sides are arguing from

    What a data center brings: a very large construction project; a serious new property-tax and utility customer; a small number of permanent, well-paid technical jobs — few jobs per acre is the industry’s known arithmetic, and pretending otherwise insults everyone’s intelligence; and a tenant that does not leave when retail cycles turn.

    What it asks: power, at a scale that makes utilities plan around a single customer; water, in most designs, for cooling; land in the same industrial zones the city’s warehouse and manufacturing economy is competing for — the same corridor economy that is Puyallup’s growth story right now; and neighbors’ tolerance for generator testing, HVAC hum, and a building that produces almost no daily street life.

    Neither column is a caricature. The council’s June move — forward with the package, slower on this — reads like a body that can see both columns and declined to pretend the math was finished.

    What happens next, and what to watch

    The Phase 2 package is working through the Planning Commission phase, with the data center allowances carrying the council’s instruction for more outreach and analysis attached. That means hearings, a staff analysis worth reading when it lands, and eventually a council decision that will be one of the more consequential land-use calls of Puyallup’s decade — because it writes the rules before the applications arrive, not after.

    For local businesses, there is a quieter stake in this than the headlines suggest. Data centers are the physical plant of the AI services every small business in town is rapidly adopting. Whether that plant sits in our industrial zones — paying into our tax base, drawing on our power planning, answering to our code — or one freeway exit away in somebody else’s is a live local choice, being made this year, in meetings almost nobody attends.

    The AI era will be built out of zoning decisions like this one, in towns like this one. June 30 was Puyallup’s turn to start deciding. The record so far says the city chose to look harder before it chose — and that the rest of the decision is still in front of all of us.

    Update — October 23, 2026: the decision window is open

    Two weeks after the June 30 session, residents were back at the microphone. The July 14, 2026 council minutes record public commenters advocating a moratorium on zoning changes related to higher-tier data centers, raising the impacts of large facilities on nearby residents, and pressing the council on its process — the June caution, organized.

    And the calendar has caught up with the story. The city’s own published timeline for the Phase 2 amendments puts the Planning Commission public hearing in fall 2026, followed by council review and action, with council consideration of the package slated for October 2026. In other words: the decision this piece said was “still in front of all of us” is being made in the current window. When the hearing date posts and the staff analysis lands, this desk will cover both — the analysis the council asked for in June is the document that will tell us what “choosing on purpose” actually costs and pays.

    Sources: City of Puyallup City Council study session minutes, June 30, 2026 (Phase 2 zoning map and code amendments, Package Six; data center allowances among items flagged for more outreach and analysis); Citizen Portal meeting record, June 30, 2026; JLARC, “2026 Tax Preference Review: Data Centers in Urban Counties” (Benaroya Capital facility in Puyallup, opened 2011; tax preference found to have had no influence on siting); City of Puyallup 2026 DPS Work Plan overview; City Council minutes, July 14, 2026 (public comment on data centers); City of Puyallup zoning map & code updates project timeline (Phase 2: Planning Commission public hearing fall 2026, council review and action to follow). Part of Tygart Media’s Puyallup coverage.

  • The Fair Is Over. What Does a Million Visitors Leave Behind?

    The Fair Is Over. What Does a Million Visitors Leave Behind?

    For twenty days in September, Puyallup — a city of roughly 44,000 people — hosted on the order of a million visitors at the Washington State Fair. The fair ran September 4–27 on the 160-acre fairgrounds, and then, as it does every year, it packed up and left.

    Here is the question October asks every business in this town: what did the million leave behind?

    Not the obvious things — not the revenue spike, welcome as it was, and not the traffic, unmissed as it is. The durable residue. Because a million visitors is the largest audience any Puyallup business will ever be handed, and almost all of that audience interacted with this town through a phone screen before, during, or after they walked through a gate. What they left behind lives on those screens — and most of it expires if nobody tends it.

    What a million visitors actually deposits

    • Searches. For twenty days, people standing in Puyallup searched like locals: coffee near me, breakfast, parking, burgers, things to do after the fair. Those searches taught the platforms which Puyallup businesses answer local intent — and the businesses that showed up, with current hours and real photos, banked visibility that doesn’t vanish when the Ferris wheel comes down.
    • Reviews. Fair season is review season. Visitors review the restaurant that saved their rainy Saturday and the shop that treated their kids well — and those reviews are read for the next eleven months by the audience that matters more: the 44,000 of us who live here and the steady stream of people deciding whether Puyallup is worth a Saturday.
    • Photos and tags. A million people photographing their day puts this town’s storefronts, signs, and plates into more feeds in three weeks than a year of ordinary marketing. That imagery is findable, and it compounds.
    • Names and numbers. Every business that ran a fair-season list signup, a text club, a receipt offer, or a Spring Fair reminder hold now owns a small asset: permission to talk to people who already came once.

    The October work: converting a crowd into a clientele

    The fair’s economics tempt a business to treat September as weather — wonderful, uncontrollable, gone. The operators who win the fair treat it as the top of a funnel that runs all year. The conversion work is October work, and it is unglamorous:

    • Answer the reviews. All of them, especially the fair-season ones, while the visit is still warm in the reviewer’s mind. A thoughtful reply in October is read by everyone shopping you in December.
    • Fix what the crowd exposed. Fair traffic is a stress test: the hours that were wrong on your profile, the menu photo from 2023, the parking question answered nowhere. A million visitors just audited your public information for free. October is when you correct the findings.
    • Send the second invitation. The list you built gets its first real message now — not a coupon blast, an invitation: the fall menu, the local night, the thing residents get that fair crowds don’t. The fair proved people will come to Puyallup. Give them a reason that isn’t a Ferris wheel.
    • Speak to the 44,000. Residents watched the fair happen to their town for twenty days. The businesses that acknowledge locals in October — we saved you a seat now that the crowds are gone — earn the loyalty that carries the other eleven months.

    The date that makes this a strategy instead of a sentiment

    The fair has already posted its return: the Spring Fair runs April 9–11 and 16–18, 2027 — two weekends, a smaller and more local crowd, and the first big test of every October intention. Businesses that did the conversion work get to watch April behave differently: repeat faces, a warmer list, reviews that mention coming back.

    And the wheel keeps turning. September 2027’s million will arrive on schedule. The only question the fair ever really asks a Puyallup business is whether it treats the crowd as weather or as an audience it intends to keep.

    A million people came to our town this fall. What they left behind is sitting in your reviews, your search profile, and your signup list right now — quietly expiring or quietly compounding, depending on what October looks like.

    The Washington State Fair ran September 4–27, 2026 at the Washington State Fair Events Center in Puyallup; the fair draws on the order of a million visitors across its run. The Spring Fair is scheduled April 9–11 and 16–18, 2027 (thefair.com). This piece is part of Tygart Media’s Puyallup coverage, alongside the Opportunity Zone series and the new farmers market story.

  • The Playbook: Four Seats, One Deadline

    The Playbook: Four Seats, One Deadline

    This is the final piece in the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters — with the math, the map, the hospital play, the housing play, the business play, and the honest caveats before it. Those explained. This one assigns seats.

    An Opportunity Zone designation is not an event. It is the start of a ten-year game with four kinds of players, and the towns that got results from the first version were the ones where all four showed up early and knew their parts.

    Tract 53053073405’s game starts January 1, 2027. Here is the playbook, seat by seat — what to do now, what to do at go-live, and the dates nobody gets to miss.

    Seat one: property owners inside the line

    You hold the scarcest asset in this story: the ground itself. The designation just made your property legible to a class of capital that could not see it last month. Moves, in order:

    • Confirm you’re in. Check your address against the official map (the State Department of Commerce maintains the nomination map; Treasury’s certified map is final). Not a neighbor’s assurance — the map.
    • Know your basis split. For any building, the number that decides your future conversations is its basis excluding land, because the substantial-improvement rule (invest at least that much again) is how investors will classify your property: renovation candidate or new-build site. Get it from your records or your CPA before anyone quotes you a strategy.
    • Decide your posture before the outreach knocks. Sell, partner with a developer, or develop it yourself with fund equity — all three are legitimate, and they are not interchangeable. Owners who choose get terms; owners who drift get offers.
    • Use the news window. The designation is a story right now, and certification in November will make it one again. Attention is a pricing input. The next twelve months are when your ground is most visible to the most qualified buyers and partners it will ever have.

    Seat two: investors holding capital gains

    Your clock is the loudest one in the program. The money piece has the arithmetic; here is the calendar discipline:

    • The regime question comes first. Money invested in a fund by December 31, 2026 lives under the expiring 1.0 rules, with deferred tax due almost immediately. The same gain invested on or after January 1, 2027 gets the full 2.0 runway: five-year rolling deferral, 10% step-up, ten-year exclusion. For most investors with late-2026 gains, the 180-day window runs into 2027 — use it deliberately rather than rushing into the dying program.
    • Underwrite the project, then the tax. The benefit is worth roughly a quarter of the gain in the best case. The difference between a good project and a bad one is worth more than that. Every credible fund will show you the underlying deal; if the deal doesn’t work without the tax story, it doesn’t work.
    • Local funds and single-project vehicles exist. Pierce County’s first-era buildings were financed by a specialist QOZ firm and a national opportunity fund platform. The channel is proven here. What will be scarce in 2027 is ready projects inside this tract — which is why seat one and seat four matter to you.
    • Paper up early. Fund subscriptions, deferral elections (Form 8997), and the annual reporting habit all run smoother set up before the gain’s clock starts, with a CPA who has done OZ work before.

    Seat three: businesses in — or willing to be in — the tract

    Your door is the least-used one in the program, which makes it the widest open:

    • Run the tests on paper first. Seventy percent of tangible property in the zone, 50% of gross income from active conduct in the zone, under 5% in passive financial assets. If your operation — or the expansion you’re planning — can pass those on a whiteboard, it’s worth a professional structuring conversation.
    • Time the entity before the money. QOZ Business status is structural: the fund must hold equity in the qualifying entity, and retrofitting an old structure is harder than forming the right one. Counsel first, capital second.
    • Think in the hospital’s supply chain. The corridor’s demand engine is a 20-year hospital expansion. Businesses that serve that campus — health services, childcare, trades, food — are pitching into documented demand, not hope.
    • Prepare to be found. Funds that do operating-company deals are rare and they scout. A business with clean books, a written growth plan, and a zone address is findable in a way a handshake operation is not.

    Seat four: the City

    The City’s part is already scripted in its own announcement: an outreach phase to property owners, developers, investors, and businesses in the designated area. The playbook adds only emphasis, drawn from what worked and failed elsewhere in 1.0:

    • Publish the pipeline. The towns that attracted quality capital made their priorities legible — priority sites, desired product types, process contacts — in public, where a fund analyst in another state could find them at midnight. Legibility is economic development now.
    • Make certification a moment. When Treasury certifies (due by November 27, 2026), that is the tract’s one guaranteed news cycle before go-live. It is the cheapest investor-relations event the City will ever be handed.
    • Keep the front door staffed. A named contact and a predictable pre-application process are worth more than incentives layered on top of the federal one. Capital flees confusion faster than it flees cost.
    • Report back to the town. The 2.0 era will generate fund-level data. A city that narrates its own tract’s record — projects, jobs, product mix — keeps public trust through the decade and keeps the next designation (2036’s map) within reach.

    The dates box

    • October 14, 2026 — Governor Ferguson’s nomination announced; Puyallup tract 53053073405 among Washington’s 99.
    • By November 27, 2026 — Treasury certification decisions due. The hub updates the day it lands.
    • December 31, 2026 — last day for investments under OZ 1.0 rules; the 2018-era deferral ends.
    • January 1, 2027 — the designation takes effect. OZ 2.0 investments begin; the ten-year clock starts.
    • December 31, 2028 — the original 2018 zone map expires nationally.
    • December 31, 2036 — this designation ends. Projects funded under it live out their own timelines.

    One table, four seats

    Strip the series down and it says one thing: the federal government has put a price on patience, and pointed it at a specific piece of Puyallup. Owners hold the ground. Investors hold the clocks. Businesses hold the jobs. The City holds the map and the microphone.

    None of the four can substitute for another — and the tract doesn’t need any of them to be heroes. It needs them to be ready at the same time, in January, when the window opens.

    The record of what they do with it will be kept on the hub, scoreboard and all. It starts at zero. It won’t stay there.

    Sources: City of Puyallup news release, October 14, 2026 (nomination, announced outreach phase); Rev. Proc. 2026-14 certification timeline (decisions by November 27, 2026); P.L. 119-21 §70421 (2.0 effective January 1, 2027; designation period through December 31, 2036; 2018 map expiry December 31, 2028); IRS Forms 8996/8997 fund and investor reporting; 2026 Opportunity Zones Handbook (QOZ Business tests; substantial improvement). This article is general information, not tax, legal, or investment advice.

  • The Honest Caveats: What Opportunity Zones Got Wrong, and What 2.0 Fixed

    The Honest Caveats: What Opportunity Zones Got Wrong, and What 2.0 Fixed

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters. The other pieces make the case — the math, the map, the hospital, the housing, the businesses. This piece is the one that makes the rest believable: everything the first version of this program got wrong, stated plainly.

    A series that only cheers for its subject is advertising. This tract deserves a chronicler, not a cheerleader — and the credibility of everything else on this site rests on this page being as honest as the others are enthusiastic.

    So: Opportunity Zones 1.0 had real failures. Some were design flaws Congress has now fixed. Some were not flaws at all, but the predictable behavior of capital given weak instructions. And some are still waiting, unfixed by any statute, for local people to decide.

    What 1.0 actually did

    The scale was real: an estimated $100 billion of equity moved into roughly 5,600 neighborhoods under the first program — one of the largest place-based capital flows in American history. The Astor and The Moraine, ten miles from the tract, are what the good version looked like: a landmark saved, workforce housing built.

    But the distribution was the scandal. One widely cited program review (Columbia Threadneedle’s analysis of the first era) found that more than a quarter of the equity raised landed in the top sliver of neighborhoods by measures of existing advantage — places whose recovery was already underway before the designation arrived. Critics catalogued the product mix that followed: luxury apartments, hotels, and self-storage facilities wearing a distressed-community incentive. Every state had its example of a zone drawn around a neighborhood that plainly didn’t need the help.

    The mechanism behind the skew is worth understanding, because it’s the thing to watch here. Governors in 2018 could nominate tracts merely adjacent to qualifying low-income tracts — the contiguous-tract rule. Money, being money, preferred the safest version of eligible: the tract next to the hot neighborhood rather than the genuinely struggling one. The incentive paid the same either way, so it bought the safer thing.

    And over it all sat a quieter failure: 1.0 required almost no reporting. Funds self-certified, and the public record of what the money built, whom it employed, and who benefited stayed thin for years. That vacuum served nobody well — it let boosters claim miracles without evidence and critics claim pure giveaway without it either. A program this size, running on this little data, was a choice, and it was the wrong one.

    What 2.0 fixed — genuinely

    The 2025 law reads, in places, like a point-by-point reply to the critics:

    • Tighter eligibility. The income test dropped from 80% to 70% of area median family income (or a 20% poverty rate with its own income cap). Fewer tracts qualify — roughly 6,500 expected nationally, down from 8,764.
    • The side door is closed. No more contiguous-tract nominations. Every tract qualifies on its own numbers. This is the single most important repair in the law, because it removes the mechanism that produced the worst headlines.
    • A cap with teeth. Governors may nominate only up to 25% of their eligible tracts — scarcity that forces actual prioritization. Washington’s 152-applications-for-99-slots process is what that looks like in practice.
    • Reporting is now law. Funds must report their holdings and activity in a structured way, so the 2.0 era can be argued from records instead of impressions.
    • The map expires. Designations now renew every ten years. A tract that no longer needs help doesn’t keep the incentive forever, and a newly struggling one isn’t locked out for a generation.
    • The deferral cliff is gone. The rolling five-year deferral (see the money piece) removes the decaying-incentive problem that distorted 1.0’s later years.

    Puyallup’s tract is a creature of the repaired rules: it qualified at the stricter test, on its own numbers, through a competitive state process. That does not make it virtuous. It makes it eligible under a better-designed screen. The distinction matters, and this series will keep making it.

    What no statute can fix

    Here is the part that lands on us.

    The incentive pays gain-holders, first and always. The direct beneficiary of every Opportunity Zone dollar is an investor with a capital gain. The community’s return — jobs, housing, services, tax base — is a downstream consequence of what that money builds. A program designed this way can be a powerful development tool; it cannot be a direct anti-poverty program, and judging it as one guarantees disappointment. Judge it instead on the buildings and businesses: are they the ones the tract needed?

    Success has a price, and the price is rent. If the corridor works — hospital growing, housing building, businesses opening — land and housing costs inside and around the tract rise. That is what success looks like in a market, and it squeezes the very residents the eligibility numbers describe. No provision of §1400Z-2 manages that. Local tools do: the affordability layering in the housing piece (the Addison Grove model), permitting choices, and whether anyone in authority is watching the rent line as carefully as the investment line. This series will watch both.

    Product choice is local. The tax code cannot distinguish a workforce apartment building from a storage facility with the same return profile. People can. The City’s announced outreach phase, the projects owners choose to bring, and the public’s attention are the actual quality control. Towns that treated their zones as spectator sports got spectator results.

    The watch list for this tract

    So the series ends its caveats where it will spend the next ten years: watching specifics. For tract 53053073405, the questions that matter, in order:

    • What is the first project — its product type, its rent or price point, its employer count? The first announcement sets the tract’s tone for every funder watching.
    • Do local owners sell, partner, or build? Each path puts the value in different hands.
    • Does any operating business get funded, or only buildings? The least-used door is the jobs test.
    • When 2.0’s reporting starts publishing, what does the fund-level record for this tract actually say? We will read it here, in public, against this page’s questions.
    • What happens to rents in and around the tract as investment lands? The success metric and the warning light are the same number, read carefully.

    The first program’s honest verdict is: powerful tool, loosely aimed, poorly measured. The second program fixed the aim and the measuring. What it cannot fix is whether the people in the place are paying attention.

    In this town, at least, somebody is. That’s the whole point of the record we’re keeping on the hub.

    Sources: Opportunity Zone 1.0 capital estimates (~$100B across ~5,600 neighborhoods) via City of Spokane / Spokane Journal of Business reporting; Columbia Threadneedle Opportunity Zones program review (concentration of equity in advantaged neighborhoods); OZ 2.0 reforms under P.L. 119-21 §70421 as summarized by the Federal Reserve Community Development function and the 2026 Opportunity Zones Handbook (70% AMI test, contiguous-tract removal, 25% nomination cap, decennial remap, fund reporting). This article is general information, not tax, legal, or investment advice.

  • The Business Play: The Opportunity Zone Door Nobody Walks Through

    The Business Play: The Opportunity Zone Door Nobody Walks Through

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters, alongside The New Opportunity Zone Math, Between Two Growth Centers, The Hospital Play, and The Housing Play. This piece covers the door almost nobody walks through: the zone funds businesses, not just buildings.

    Ask a room of business owners what an Opportunity Zone is and you’ll hear about apartment buildings. The real estate story ate the whole program’s public image — partly because buildings are easy to photograph, and partly because most funds found property easier to underwrite than companies.

    But the statute has a second door, and for a tract anchored by a growing hospital, it may be the more important one: a Qualified Opportunity Fund can buy equity in an operating business inside the zone — a Qualified Opportunity Zone Business. Growth capital, from investors whose tax benefit requires them to stay for ten years, for companies that locate and operate inside the line.

    How a business qualifies, in plain English

    The rules are real, and they are tests, not vibes. Reduced to their working core, an operating business qualifies when:

    • Its tangible property is in the zone. At least 70% of the business’s tangible property — owned or leased — must be qualified zone business property: property acquired after 2017 (and, under 2.0, aligned to the new designation period), used in the zone, and either new or substantially improved.
    • Its income is earned in the zone. At least 50% of the business’s gross income must come from the active conduct of the business inside the zone. A company can’t just rent a mailbox in the tract and operate in Bellevue.
    • It is actually a business. Less than 5% of its assets can sit in stocks, bonds, and other nonqualified financial property (ordinary working capital and reasonable reserves aside), a substantial portion of any intangible property must be used in the zone’s active conduct, and the statute excludes a short list of “sin” categories — golf courses, gambling facilities, liquor stores, and their relatives need not apply.
    • The fund’s money works on a clock. Businesses get a working-capital safe harbor — up to 31 months under a written plan to deploy the capital — which is the provision that makes expansions and build-outs practical instead of theoretical.

    An owner reading that list will notice something: these tests describe a business that is genuinely there — property there, income there, operations there. That is not a loophole shape. That is the program working as designed.

    Why almost nobody uses this door

    Three honest reasons. First, funds are mostly built by real estate people; underwriting an operating company’s management and market is a different skill than underwriting a building, and most QOF platforms never acquired it. Second, the compliance testing is ongoing — a building stays qualified by standing there, while a business must keep passing its tests as it operates, hires, and grows. Third, the deal sizes are often smaller than fund economics prefer.

    The result is a strange gap: the program’s most job-creating mechanism is its least used. For Puyallup, that gap is an opportunity, because the tract’s demand story — a $430 million hospital expansion — generates business demand that buildings alone don’t answer.

    The businesses this tract is actually calling for

    Read the hospital’s ecology as a business list, because that is what it is:

    • Healthcare services around the campus — home health agencies, outpatient therapy, imaging and lab services, durable medical equipment, medical staffing. Businesses whose customers and referral sources are a short drive from the tract, whose workforce is local, and whose income is earned where their people work.
    • Childcare built for shift work — an operating business (not just a building) serving the hospital’s three-shift workforce, the single most-cited unmet need around every growing hospital campus in America.
    • Trades and light production — the corridor’s existing commercial fabric is full of service businesses, fabricators, and suppliers positioned between the Port of Tacoma’s freight economy and the South Hill retail engine; expansion-stage companies in that fabric are natural candidates for growth equity that doesn’t come with a bank’s five-year leash.
    • Food and daily services — the unglamorous, durable layer that a campus population of staff, patients, and visitors supports around the clock.

    What it means for an owner

    For a business owner inside the tract — or one willing to locate a real operation there — the QOF structure offers something bank debt doesn’t: equity whose owners are rewarded for staying. The fund’s full tax benefit requires a ten-year hold, which makes its capital structurally patient. The trade is real, too: equity means dilution and a partner, where debt means payments and a deadline. Which one fits depends on the business, the growth plan, and the owner’s appetite for company.

    The realistic paths in:

    • Expansion capital. An existing Pierce County business opens its growth location — second site, larger facility, new service line — inside the tract, structured so the fund’s equity funds the expansion entity.
    • Relocation with substance. A business moves real operations — property, people, income — into the zone and raises fund equity against the move and build-out.
    • Founder-stage location. A new business in the hospital’s service ecology chooses the tract as its home base from day one, raising patient equity instead of stacking early debt.

    Each path needs the same unglamorous first steps: confirm the address is inside tract 53053073405 on the official map, and structure the entity with counsel and a CPA who has actually read §1400Z-2 — before money moves, not after. The tests are passable; they are not forgiving of improvisation.

    The number that keeps this honest

    Nationally, the overwhelming share of the estimated $100 billion that flowed through Opportunity Zone 1.0 went to real estate. The business door stood open the whole time, comparatively unused. If Puyallup’s tract ends up funding even a handful of operating companies — employers, not just addresses — it will have used the program better than most of the map did.

    Buildings are what the zone is famous for. Businesses are what a town actually runs on. The scoreboard on the hub has a line waiting for the first one.

    Sources: IRC §1400Z-2 and QOZ Business requirements as summarized in the 2026 Opportunity Zones Handbook (70% tangible property test; 50% of gross income from active conduct in the zone; under 5% nonqualified financial property; excluded business categories; 31-month working capital safe harbor); Opportunity Zones 2.0 provisions under P.L. 119-21; Opportunity Zone 1.0 capital estimates (~$100B, predominantly real estate) via industry and city reporting. This article is general information, not tax, legal, or investment advice.

  • The Housing Play: Three Pierce County Models, One Obvious Next Site

    The Housing Play: Three Pierce County Models, One Obvious Next Site

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters, alongside The New Opportunity Zone Math, Between Two Growth Centers, and The Hospital Play. This piece is housing — and unlike most housing commentary, every model in it is a real building within ten miles of the tract.

    Housing is where Opportunity Zone money does its most visible work, and its most argued-about. It is also where Pierce County has an unusual advantage in this conversation: we don’t have to speculate about what OZ housing looks like. It is already built here, in two different flavors — and Puyallup itself just proved it can close a sophisticated housing deal in 90 days.

    Three buildings. Three capital models. One obvious next site.

    Model one: The Astor — the historic conversion (Tacoma)

    In downtown Tacoma, the Washington Building stood as a 1925 office tower, a landmark running out of economic lives. Unico Properties partnered with Pinnacle Partners — a firm that exists specifically to invest Qualified Opportunity Zone funds — and converted it into The Astor: 156 apartments, delivered in July 2022.

    The lesson for Puyallup is the mechanism. Adaptive reuse of an existing building under OZ rules runs on the substantial improvement test: within 30 months, the project must invest at least as much in improving the building as the building itself was worth (its basis, excluding the land). Buy a tired building for a basis of $800,000 and the rule requires another $800,000-plus of real construction into it. The rule is why OZ money loves sturdy old shells — the incentive literally pays for resurrection, not cosmetics.

    The tract between Downtown and South Hill has exactly this kind of stock: older commercial buildings with good bones and tired economics. The Astor is the proof, fifteen minutes away, that QOZ capital will underwrite their second lives.

    Model two: The Moraine — workforce housing, new build (Tacoma Hilltop)

    On Tacoma’s Hilltop, Ethos Development and Catalyst Opportunity Funds built The Moraine: 160 units of workforce housing — new construction, aimed at the people who staff a city’s hospitals, schools, and services rather than at the top of the rent market. It won CoStar’s 2025 Multifamily Development of the Year for the Seattle market.

    Workforce housing is the product OZ 2.0’s redesign quietly favors: the tightened eligibility tests push funds toward tracts with genuine need, and the new reporting requirements mean the “who lives there” question now gets asked in public. The Moraine shows the product can also be the best building in its market — workforce rents and an award-winning project are not a contradiction.

    For Puyallup, connect this model to the hospital play: Good Samaritan’s expansion will hire in waves for twenty years. Those hires are the Moraine’s tenant profile, and housing built for them — near the campus, at workforce rents — is the tract’s most defensible residential thesis.

    Model three: Addison Grove — the 90-day close (Puyallup, not OZ)

    The third building is the one skeptics should sit with. Addison Grove, right here in Puyallup, is 102 apartments for families earning 50–80% of area median income (90 of the 102 homes are reserved below 60% of AMI), developed by Great Expectations. It is not an Opportunity Zone project — its engine is the Washington Family Housing Fund, created by Ballmer Group with the Washington State Housing Finance Commission, which put in a $13.41 million subordinate forgivable loan. From application to closing: 90 days.

    Addison Grove matters to this series for three reasons. First, it proves Puyallup’s machinery works — land, entitlements, and a sophisticated capital stack, executed fast. Second, it proves local absorption: affordable and workforce product here leases into real demand, not projections. Third, it sets the honest contrast: where OZ equity is return-seeking capital that needs the math in the money piece to work, the Family Housing Fund is concessionary capital that optimizes for affordability per dollar. Different engines, both real.

    How the three models stack over one tract

    The mistake is treating these as competitors. Over a ten-year designation, a healthy tract uses all three:

    • Conversions (Astor model) for the older buildings the substantial-improvement rule fits — QOZ equity, market and workforce rents, historic fabric saved instead of scraped.
    • New workforce buildings (Moraine model) on the vacant and underutilized parcels the City’s application emphasized — QOZ equity again, aimed at the hospital-and-corridor workforce.
    • Layered affordable projects (Addison Grove model) where deeper affordability is the goal — concessionary and public capital in the stack, with OZ equity able to sit alongside other sources where a project is structured for it.

    That layering point is the one honest housing economists insist on, and this series will too: tax-advantaged equity on its own generally underwrites market and workforce rents. The deeper affordability — the 50–60% AMI homes — usually arrives when other capital takes the subordinated, patient position, exactly as the Family Housing Fund did. OZ 2.0’s reporting makes it harder to blur that distinction, which is a feature.

    What would actually get built first

    If the Pierce County record is the guide, the tract’s first housing moves are the Astor and Moraine plays, not the mega-project: an older building with the right basis math, converted; a vacant parcel near the corridor, built to workforce rents; both marketed to the workforce the hospital is hiring and the two growth centers already employ.

    The demand is documented — a 249-bed regional shortfall being built against, two designated growth centers, a fair that imports a million visitors a year past these blocks. The models are standing ten miles apart, visible from the freeway. The capital mechanism switches on January 1, 2027.

    What Puyallup adds, when the first project is announced, gets recorded on the hub’s scoreboard — which today still reads zero, and won’t for long.

    Sources: Unico Properties (The Astor — 156 units, Washington Building adaptive reuse with Pinnacle Partners, delivered July 2022); Catalyst Opportunity Funds (The Moraine — 160 workforce units with Ethos Development; CoStar 2025 Multifamily Development of the Year, Seattle market); Propmodo / Puget Sound Business Journal (Addison Grove — 102 units at 50–80% AMI, Washington Family Housing Fund $13.41M subordinate forgivable loan, 90-day close, developer Great Expectations); IRS/IRC §1400Z-2 substantial improvement standard (100% of building basis ex-land within 30 months, urban). This article is general information, not tax, legal, or investment advice.

  • The Hospital Play: What a $430 Million Expansion Builds Around Itself

    The Hospital Play: What a $430 Million Expansion Builds Around Itself

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters, alongside The New Opportunity Zone Math and Between Two Growth Centers. This piece is the engine: the hospital at the tract’s edge, and everything its expansion pulls into being around it.

    Every successful development district has an engine — something that generates demand on a schedule nobody has to guess at. Factories close. Retail follows rooftops, and rooftops follow fashion. But a hospital expansion is different: it is a twenty-year construction program bolted to a demographic certainty.

    Tract 53053073405’s engine is already permitted. That is what makes this tract different from the thousands of zones on the new national map whose boosters are still hoping an anchor shows up.

    The anchor: Good Samaritan’s twenty-year build

    MultiCare Good Samaritan Hospital is working through a 20-year master plan for its Puyallup campus. The Puyallup City Council authorized the development agreement for it on January 27, 2026 — the legal chassis that lets a project of this size phase over two decades.

    The centerpiece is a patient care tower budgeted at more than $430 million: 160 new licensed inpatient beds, plus 30 observation beds, plus a shelled floor built to hold 40 more beds when the region needs them. The wider program around the tower includes parking structures, medical office buildings, and a central support tower.

    And the demand side is not a developer’s projection. MultiCare’s own planning says the region will need 249 additional hospital beds by 2036. East Pierce County is growing, aging, and currently sending patients elsewhere. The tower is the system catching up — with a shelled floor that admits, in concrete, that even this build may not be the last one.

    Why a nonprofit anchor still powers a tax-incentive play

    Here is the part that confuses people: MultiCare is a nonprofit. Its tower does not need Opportunity Zone equity, and the hospital campus itself is not the OZ project. Some readers stop there and conclude the hospital is irrelevant to the zone.

    That gets the economics backwards. The incentive doesn’t need the anchor to be investable. It needs the anchor to be certain. A Qualified Opportunity Fund deciding where to place ten-year money is underwriting one question above all others: will demand still be there in year ten? A permitted, phased, $430-million hospital program — driven by a documented regional bed shortage — is about the strongest answer that question ever gets.

    The hospital is the sun. The zone projects are what grows in its light.

    What a hospital expansion actually demands around it

    A tower with 190 new beds and observation units runs on hundreds of people across three shifts, and it pulls an entire service ecology in behind it. Each item below is a category of private, for-profit development — the kind QOF capital exists to fund — that hospital growth makes necessary rather than speculative:

    • Medical office buildings. Physician groups, clinics, imaging, labs, and outpatient specialists cluster next to the hospital they refer into. The master plan itself names medical office buildings in its program — the hospital knows its own gravity. Private MOB development adjacent to a growing campus is one of the oldest, steadiest plays in healthcare real estate.
    • Workforce housing. Hospitals hire in waves — nurses, techs, therapists, support staff — and they hire people who work nights and need to live close. A workforce that cannot find housing within a sane commute is a recruiting problem the hospital cannot solve alone. Housing aimed at the hospital workforce is the tract’s most natural residential product, ahead of generic apartments.
    • Childcare built for shift work. Standard childcare runs banker’s hours; hospitals run 12-hour shifts starting before dawn. Early-opening, extended-hour childcare near a major hospital campus serves a captive, desperate customer base — and childcare businesses can themselves be qualified zone businesses, not just real estate.
    • Post-acute and rehab services. Discharged patients need skilled nursing, outpatient physical and occupational therapy, home health, and durable medical equipment. A bigger hospital discharges more patients into exactly these services, which prefer to locate minutes from the discharge door.
    • Travel-clinician and family lodging. Hospitals run partly on traveling clinicians who need furnished mid-term housing, and on patients’ families who need to stay near a long admission. Both are quiet, durable demand streams that generic market studies miss.
    • The daily-services layer. Food that serves a night shift, pharmacies, fitness and recovery, parking, and the small retail that a campus population of staff, patients, and visitors supports around the clock.

    Read that list against the tract the City described in its application — underutilized and vacant properties, established commercial areas, transportation connections — and the fit is obvious. The corridor does not need to invent a purpose. It needs to house the ecology of the institution already expanding beside it.

    The phasing advantage: a twenty-year ramp meets a ten-year clock

    Most development incentives fight a timing problem: the money must deploy fast, but demand arrives slowly. This tract inverts it.

    The Opportunity Zone benefit peaks at a ten-year hold. The hospital’s master plan runs twenty years. The zone investor’s clock sits comfortably inside the anchor’s construction and staffing ramp — the tower rising, beds licensing in phases, the shelled floor waiting as documented future demand. A project that opens alongside an early hospital phase gets a decade of the anchor still growing around it.

    There is a subtler point for the City’s outreach phase: because the demand is phased, the tract’s projects can be phased too. Medical office first, while the tower is under construction. Workforce housing timed to hiring waves. Services as the patient volume lands. Nobody has to bet the whole tract on a single opening day.

    The honest cautions

    Hospital timelines slip — construction costs, certificate-of-need processes, and system capital priorities have delayed bigger plans than this one, and a master plan is a framework, not a promise that every element lands on schedule. The development agreement and the bed-need projection make this anchor as solid as anchors get, but “solid” is not “guaranteed.”

    And the anchor’s gravity does not move parcels by itself. The surrounding projects still need owners willing to sell or build, developers willing to structure funds, and the City’s ordinary permitting to do its work. What the hospital changes is the risk math for everyone deciding — which, for ten-year money, is most of the decision.

    The zone maps in America are full of tracts whose story is hope. This one’s story is a construction schedule, a bed count, and a shelled floor poured for patients who haven’t arrived yet. Of all the pads in this series, the hospital play is the one whose demand you can read off a planning document — which is exactly why sophisticated capital reads planning documents.

    The same build, through two other lenses: the facilities version — Building on a Live Campus, on phasing a 20-year expansion without ever closing the hospital (Healthcare Facility Hub) — and the risk version — The Risk Stack on a $430 Million Hospital Build (Risk Coverage Hub).

    Sources: Puyallup City Council action authorizing the Good Samaritan Hospital expansion development agreement, January 27, 2026 (20-year master plan; patient care tower; parking structures; medical office buildings; central support tower), via Citizen Portal; South Sound Report on the $430M+ expansion (160 new licensed beds, 30 observation beds, shelled floor for 40 more); MultiCare regional projection of 249 additional beds needed by 2036; City of Puyallup Opportunity Zone news release, October 14, 2026. This article is general information, not tax, legal, or investment advice.

  • Between Two Growth Centers: An Anatomy of Tract 53053073405

    Between Two Growth Centers: An Anatomy of Tract 53053073405

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters. The companion piece, The New Opportunity Zone Math, covers how the money computes. This piece is the ground itself: what tract 53053073405 is, where it sits, and why it was chosen.

    Every Opportunity Zone story eventually becomes a map story. The incentive does not attach to a city, a neighborhood name, or a mayor’s priority list. It attaches to a census tract — an invisible statistical boundary most residents have never seen drawn — and everything inside that boundary plays by different financial rules for ten years.

    Puyallup’s nominated tract is 53053073405. The number itself is a small map: 53 is Washington, 053 is Pierce County, and 0734.05 is the tract. When the Treasury Department certifies the list — due by November 27, 2026 — that eleven-digit string becomes the most consequential geography in Puyallup’s economy.

    Where it sits: the between place

    The City’s announcement describes the tract precisely: it is “situated between two Regional Growth Centers and near MultiCare Good Samaritan Hospital.”

    The two growth centers are Puyallup Downtown and Puyallup South Hill — the region’s formally designated centers, the places county and regional plans already steer jobs, housing, and transit investment toward. Downtown carries the historic core, the fairgrounds, and the Sounder station. South Hill carries the mall corridor and the city’s big retail gravity.

    The tract is the ground between the two magnets — anchored on one side by Good Samaritan’s campus, the hospital now mid-way through a 20-year, $430-million-plus expansion. In planning language that’s called a corridor. In plain language: it’s the connective tissue of the city, the land you pass through between the two places you’re going, full of the underutilized and vacant properties the City’s application put at the center of its pitch.

    That in-between status is exactly what the City sold to the state. Puyallup’s application “emphasized the area’s strong potential for redevelopment, including underutilized and vacant properties that could benefit from new investment,” plus its “proximity to major employment centers, healthcare facilities, transportation connections, and established commercial areas.” Read that sentence again and you have the tract’s anatomy: older commercial fabric, room to rebuild, and demand anchors on every side.

    Why this tract qualified

    Opportunity Zones 2.0 tightened the door. Under the first program, a tract qualified at up to 80% of area median family income, and governors could also nominate tracts merely adjacent to qualifying ones — the loophole that put some already-gentrifying neighborhoods on the 2018 map.

    The new tests are stricter, and the side door is closed:

    • A tract must have a median family income at or below 70% of the area median, or
    • a poverty rate of at least 20% with median income at or below 125% of the area median, and
    • it must qualify on its own numbers — no contiguous-tract nominations.

    Governors could nominate only up to 25% of their states’ eligible tracts. Washington’s process drew 152 applications for 99 slots. Puyallup’s tract made a competitive cut under stricter math than the first map ever faced — which means the designation says something real about the ground: by the federal measures, this is a lower-income tract sitting inside a city whose overall numbers (43,730 residents; a citywide median household income of about $97,826) look comfortably middle-class. Both things are true at once. That tension — a prosperous small city with a genuinely strained corridor inside it — is precisely the profile the program was redesigned to find.

    What “inside the line” legally means

    Three clarifications that will matter for the next decade of local arguments:

    The designation covers the whole tract, not a project list. Any qualifying investment anywhere inside the boundary is eligible — a housing project, a renovated commercial building, an operating business that meets the tests. There is no roster of approved sites. Whoever owns land inside the line owns an option; what gets exercised is up to owners, developers, and the City’s normal permitting process.

    The line does not change zoning, taxes, or rules by itself. It changes the return math for private capital. A project still needs permits, still pays property tax, still goes through design review. The zone is an incentive layered over the city’s existing machinery — which is why the City’s announced next phase is outreach: connecting the people who own the ground to the people whose capital gains are looking for a home.

    Addresses, not vibes. Because the boundary is a census line, it cuts where census geography cuts — sometimes mid-block, sometimes through a parcel’s tax lot. The only way to know whether a specific property is in is to check the address against the official map. The Washington State Department of Commerce maintains the nomination map (an ArcGIS viewer linked from its Opportunity Zones page), and once Treasury certifies, the federal map is the final word. Anyone quoted a verbal assurance about a parcel should ask for the map printout instead.

    The anchors around the tract

    A tract does not succeed on its own acres; it succeeds on what surrounds it. This one’s surroundings are unusually strong for a qualifying low-income tract:

    • Good Samaritan Hospital. A 20-year master plan, a development agreement authorized by the City Council in January 2026, 160 new inpatient beds coming, and a regional projection of 249 more beds needed by 2036. Hospitals are decade-scale demand engines: staff, patients, visitors, suppliers, and every service that clusters around care.
    • Downtown and the fairgrounds. The Washington State Fair puts roughly a million visitors a year into the north end of this corridor; the downtown growth center carries the restaurants, services, and the Sounder commuter rail link to Tacoma and Seattle.
    • South Hill. The region’s retail center of gravity — the mall, the big boxes, and the traffic that comes with them — at the corridor’s other end.
    • A town already practicing. The same season brought a 134-vendor farmers market through environmental review and a 102-unit affordable housing project (Addison Grove) that closed its financing in 90 days. The machinery of getting things built here demonstrably works.

    The honest unknown

    What nobody can draw yet is the tract’s future project map — because it doesn’t exist. The scoreboard, as the hub piece puts it, is empty. Certification comes first (by November 27), then the January 1 starting gun, then the City’s outreach, then — if the work gets done — the first announcements.

    When they come, they will land somewhere inside an eleven-digit boundary most of us had never heard of before October. Now you know where the line is, and why it was drawn there. The rest of this series is about what gets built inside it.

    Sources: City of Puyallup news release, October 14, 2026 (tract description, application emphasis, next-phase outreach); Washington State Department of Commerce OZ 2.0 nomination records (152 applications, 99 nominations); Federal Reserve Community Development and the 2026 Opportunity Zones Handbook (2.0 eligibility tests, 25% nomination cap); Puget Sound Regional Council / Pierce County center designations via The Urbanist (Puyallup Downtown and Puyallup South Hill Regional Growth Centers); South Sound Magazine city snapshot (population 43,730; median household income $97,826, Census 2024). This article is general information, not tax, legal, or investment advice.

  • Five Years of Deferral, Ten Years to Tax-Free: The New Opportunity Zone Math

    Five Years of Deferral, Ten Years to Tax-Free: The New Opportunity Zone Math

    This is part of the series that starts with Inside the Line: Puyallup’s Opportunity Zone, Explained Like It Matters — the hub page for Puyallup’s nominated Opportunity Zone tract. This piece is the money: how the tax incentive actually computes.

    Opportunity Zone coverage usually dies in one of two ways: it waves at “tax benefits” without ever doing arithmetic, or it drowns in fund-manager vocabulary. Here is the middle path — the actual mechanics of Opportunity Zones 2.0, with numbers, using the same example throughout: a $1,000,000 capital gain, and a top federal rate of 23.8% (20% capital gains plus the 3.8% net investment income tax). Federal only; your rate and your state picture will differ. Illustrative, not tax advice.

    First, what changed: 1.0 versus 2.0

    The first Opportunity Zone program (2018–2026) had a design flaw baked in: its benefits expired on a fixed calendar. Deferral ended December 31, 2026 no matter when you invested, so every year the program aged, the incentive got weaker. The step-ups withered to zero. Rational money waited.

    The 2025 law (Public Law 119-21) rebuilt it as a permanent program:

    • Rolling deferral. Invest a gain on or after January 1, 2027, and the tax is deferred five years from your investment date — not to a fixed year-end.
    • The step-up is back, simplified. One step-up: 10% of the deferred gain is forgiven at the five-year mark. (The old 5-year/7-year ladder is gone. Qualified rural funds get 30% — Puyallup’s tract is urban, so 10% is the local number.)
    • The ten-year exclusion survives intact. Hold the fund investment at least ten years and the appreciation is excluded from federal tax — with a fair-market-value basis step-up available on sales up to the 30-year mark.
    • The map renews. New zones every ten years, tighter eligibility, and — new in 2.0 — real fund-level reporting, so the public can see what the money did.
    • The bridge rule that matters this winter. Which program you get depends on when the gain goes into the fund. Invest by December 31, 2026 and you are under the dying 1.0 rules, with the deferred gain taxed almost immediately. Invest the same gain on January 1, 2027 and the full 2.0 runway opens. One day, two different programs.

    The three clocks every investor is actually running

    Strip away the vocabulary and an Opportunity Zone investment is three clocks:

    Clock one: 180 days. From the day the gain is realized — the sale closes, the K-1 arrives — the investor has 180 days to place the gain in a Qualified Opportunity Fund. Miss it and the incentive is gone; this deadline, not the tax code’s fine print, is what kills most would-be OZ deals. (Partnership gains have their own start-date wrinkles — one of several places a CPA earns their fee.)

    Clock two: five years. The deferred gain comes due at the five-year anniversary of the investment. By then the step-up has applied, so the tax is computed on 90% of the original gain.

    Clock three: ten years. Cross ten years in the fund and the appreciation on the QOF investment itself becomes excludable. This is the clock that aligns the investor with the place: the full benefit only exists if the money stayed, worked, and grew inside zones for a decade.

    Three investors, one $1,000,000 gain

    Investor A pays the old-fashioned way. Sells in 2027, keeps the gain, invests wherever. Tax on $1,000,000 at 23.8%: $238,000, due with the 2027 return. Investable remainder: $762,000.

    Investor B uses the zone but leaves at year three. The $1,000,000 goes into a QOF inside a designated tract. Selling the fund interest early is an inclusion event: the deferral ends and the deferred gain is recognized — with no step-up yet and no exclusion. B got three years of float on the tax money and nothing else. The lesson is structural: this program does not reward tourists.

    Investor C stays for the whole design. Year five: the deferred gain is recognized at $900,000 after the step-up — tax of $214,200 instead of $238,000, a $23,800 saving, plus five years of deferral on the balance. Year ten: suppose the fund investment has doubled to $2,000,000. The $1,000,000 of appreciation is excluded — at the same rate, roughly $238,000 of tax that simply never happens. Combined effect versus Investor A: about $262,000 of federal tax avoided or deferred, before counting what five years of full principal working (instead of $762,000) did to the returns themselves.

    That last point is the quiet one. Deferral is not just a later tax bill; it is the government’s share of your gain working in your project for five years, interest-free.

    Who around here actually has a gain?

    The investor in these examples is not a caricature from a coastal fund brochure. In Pierce County, the people holding seven-figure gains in any given year are ordinary:

    • Business sellers. The owner who sells the company they built for thirty years — the single biggest gain most families ever realize, and it arrives all at once.
    • Real estate sellers. The family that sells the rental portfolio, the commercial building, or the development parcel.
    • Partners and shareholders. Anyone whose K-1 carries a share of a partnership’s sale gain — often people who never chose the timing at all.

    Each of them faces the same 180-day clock and the same fork: pay the tax and move on, or route the gain through a fund into places like tract 53053073405 and let the clocks run. Puyallup’s designation matters to them because a fund needs projects; projects need to be findable, packaged, and ready when somebody’s clock starts ticking.

    What a fund is, minus the mystique

    A Qualified Opportunity Fund is an investment vehicle — a corporation or partnership — that self-certifies to the IRS (Form 8996) and must hold at least 90% of its assets in qualified zone property: zone real estate being built or substantially improved, or stock and partnership interests in qualified zone businesses. Investors report their deferrals annually (Form 8997). Funds can be national platforms, regional specialists — Pierce County has already seen both models build real projects — or single-project vehicles formed around one development.

    Two cautions belong in any honest version of this piece. The tax benefit never rescues a bad project; a failed building with a step-up is still a failed building, and the incentive’s size (roughly a quarter of the gain, best case) is smaller than the swing between a good deal and a bad one. And Washington investors have a second layer to model: the state’s own capital gains excise tax is a separate system from the federal one, and how the two interact on a given gain is a question for your tax advisor, not a blog post.

    Why this matters before January 1

    The Puyallup tract’s designation, if Treasury certifies it as expected by late November, opens for 2.0 investments on January 1, 2027. Gains realized in late 2026 will hit their 180-day windows in the first half of 2027 — which means the investors who could fund the tract’s first projects are, right now, in the middle of the sales that create their gains.

    That is the real deadline pressure in this story. Not the tax code. The calendar of other people’s closings — and whether Puyallup has projects ready to be found when the clocks start.

    Next in the series: the map — an anatomy of tract 53053073405, between the Downtown and South Hill growth centers. Sources: P.L. 119-21 §70421 and IRC §1400Z-2 as amended (rolling five-year deferral, 10%/30% step-ups, 30-year exclusion window); 2026 Opportunity Zones Handbook; Federal Reserve Community Development, “Opportunity Zones 2.0 will offer place-based investment in low-income communities”; OZ HQ 1.0-vs-2.0 transition guidance (investment date determines the regime; Notice 2026-40). Figures are illustrative simplifications, not tax advice.