Tag: Commercial Restoration

  • The Puget Sound Playbook: How AI Decides Who Gets the Water-Damage Call

    The Puget Sound Playbook: How AI Decides Who Gets the Water-Damage Call

    The tactics in this playbook are the same ones we publish for every market: be readable to the machines, be named, be cited, measure it with the denominators showing. What changes in Puget Sound is that Puget Sound is not one market. It is at least six, stacked on top of each other along one highway — and the move that wins in Tacoma wastes money in Everett, while the move that matters most in Edmonds barely registers in Seattle. This is the local edition: the same doctrine, market by market, with our own measurements where we have them and honest labels where we don’t.

    It has two halves, because the playbook was always two books bound together. The first half is visibility: how the answer engines decide whose name a flooded homeowner hears. The second half is the specialty work — the fire extinguisher tag, the records room, the server rack, the art on the lobby wall — the plays that get a restoration company inside commercial buildings before anything breaks. Same Sound, same six markets, same rule in both halves: a tactic only earns its place here with a local reason, and where there is no local reason, we say so instead of swapping in a city name and calling it local.

    Every number below that carries a percentage was measured on our rig on October 18, 2026: real homeowner questions, asked mid-flood style — “who should I call,” “who’s best,” “who has the most reviews” — put to ChatGPT, Perplexity, Gemini, and Google AI Mode, with every answer scored for who got named and whose pages got cited. Google AI Overview returned no answer on any question in these batteries and is excluded everywhere below. A snapshot is not a census. It is one dated sample, with its denominators showing, and it is still the only honest way we know to talk about this.

    The doctrine, before the geography

    Named and cited are two different jobs. An answer engine can use your page as a source and still recommend somebody else — we have watched it happen, and the section on Everett below shows the receipt. Being named is the engine volunteering your company in the answer text. Being cited is your page appearing in the source list underneath it. The first job gets you the call. The second job is how the first one eventually happens. Any report that blends the two into one “visibility score” is hiding the only distinction that matters.

    Your website is a minority of what the engines say about you. The frame we use on our own offer comes from McKinsey’s research: a brand’s own website is a small share of the citations about that brand. The rest comes from the pages the models already trust — directories, association profiles, local references, roundup pages. That is why the work is the service pages, the insurance and certification language, and the outside profiles, in that combination. A beautiful website with thin directory presence is a company the engines can describe but rarely do.

    The competitor set is fixed, visible, and smaller than you think. Ask an engine who handles water damage in a city and it names one or two companies, out of a frame of maybe eight that ever appear. The frame repeats. The same names show up answer after answer, which means the game is not “rank higher” — it is “get into the frame, then take share inside it.” You can read your frame any time you want. We run a fixed list of prompts for exactly that reason.

    Reviews are machine food now, and the machines cross-check. The engines quote review counts back at homeowners — “over 160 five-star Google reviews” is the kind of clause that decides an answer. But the footprint has to agree with itself across the surfaces the engines read. A deep review base on one surface and a thin, stale profile on another reads to a model the way a half-finished job reads to an adjuster: possible, but not the safe recommendation.

    Each engine reads different sources, so “AI visibility” is not one number. In our measurements, Perplexity and Google AI Mode cite Yelp in roughly one answer in six; Gemini has never cited Yelp in our rig at all — zero of 35 answers. A tactic that feeds Perplexity may do nothing for Gemini. Anyone selling you a single score for all of AI is averaging away the part you could have acted on.

    Directories are citation infrastructure, not paperwork. Across 143 answers measured the same week, the directory order was BBB first, then Thumbtack, HomeAdvisor, and Yelp fourth — 21 Yelp citations, ahead of Expertise and Angi. When a homeowner asks an engine whether a specific company is any good, the engine goes to that company’s own directory pages: in all three Puget Sound branded checks we ran, the company’s Yelp business page was the page cited. Claimed, complete, current is not hygiene. It is the asset.

    Measure first, fix the biggest gap, re-measure. Every engagement we run starts with the same sequence: a fixed prompt list, scored answers, one highest-leverage fix, then the same list again after the fix so the movement is provable. The fix is usually unglamorous — a service page that does for one city what another of your pages already does for a different city, a directory profile completed, a name collision cleaned up. Small repairs, precisely aimed, beat a website rebuild aimed at everything.

    Seattle metro: the saturated frame

    Seattle is the hardest frame in the region to enter, because it is the one market here where franchise density and review volume stack on top of each other. When we asked ChatGPT which Seattle-area water damage company has the most reviews, the answer crowned listing names — shops whose review counts the engine could read and repeat — and never reached a local company holding 100+ five-star reviews of its own. In a saturated market, the engine’s shortlist is built from whatever is most legible at scale, and legibility at scale is what national brands manufacture for a living.

    The tactic that matters most in Seattle is citation capture on the questions franchises answer sloppily: the specific ones. “Who handles sewage cleanup in a condo building” is a different frame from “best water damage company,” and it is thinner. The tactic that matters least is another generic service page saying you do water damage in Seattle — the frame already has that page, written by a brand with two thousand locations. In Seattle you do not out-shout the wall. You find the doors in it.

    The Eastside: commercial money, quiet homeowners

    Bellevue, Redmond, and Kirkland run on a different economy than the rest of the Sound: higher-value homes, a deep commercial and property-management layer, and franchise-owned restoration territory. We have not run a dedicated Eastside measurement battery yet, so this section is doctrine, labeled as such — it will get its own snapshot before we treat it as anything more.

    The doctrine says the Eastside rewards the commercial signals: insurance billing fluency, documented response time, capacity language a property manager can forward to an owner. The buyer asking the question is often not the homeowner at all. It is the manager of a flooded HOA or a warehouse, asking an engine who can handle it — and the citation has to prove commercial capability, not just residential warmth. Review volume matters less here than it does in Seattle; a smaller, current, consistent profile across the directories beats a big stale one, because the questions are fewer and the reader is checking, not browsing.

    Tacoma and Pierce County: the winnable frame

    Tacoma is where we can prove a local leader can own serious share of the frame. In our October 18 battery — seven unbranded questions, 27 answers that named a company — the leading independent was named in 41% of answers. That is a real seat at the table. But the same battery shows the split that decides everything: the independent was cited in only 11% of answers, while SERVPRO was named in 59% and cited in 52%. The engines know the local company exists. They name it from memory and cite the franchise from evidence.

    The Tacoma battery also produced the single most instructive answer in our Puget Sound work. On Perplexity, asked for the best water damage company in Tacoma, the answer opened by calling SERVPRO of Tacoma “the strongest overall choice” — in the same market where the independent’s own Tacoma page ranks first on Google for that question. Winning Google and winning the answer are now separate competitions, and Tacoma is where the gap between them is easiest to close: the naming is already there, so the work is the cited evidence underneath it — the service pages, the directory records, the outside pages Perplexity actually reads.

    One more Tacoma lesson, and it is about humility at the engine layer: asked about a burst pipe in Kent — where the leading independent is headquartered — Gemini hedged on whether Kent was in Washington or Ohio, and named SERVPRO. Engines get local geography wrong in ways a human never would. Part of the local play is feeding them geography so plainly stated, in so many consistent places, that the machine cannot confuse your city with one in Ohio.

    Everett and Snohomish County: the wall, and the split

    Everett is the wall. In our battery — seven unbranded questions, 28 answers — SERVPRO was named in 71%. The leading independent, holding the deepest review base of any independent in the corridor (682 Google reviews, displayed on its own website), was named in 29% and cited in 18%. That is not an unknown company being ignored. That is a known company losing to a frame: SERVPRO, PuroClean, Roto-Rooter, and a rotation of local names divide the answers, and the independent’s share is real but third-tier.

    Everett also gave us the cleanest proof in the region that cited and named are different jobs. On one Gemini answer, the source list included the independent’s own Everett page — the engine read it, used it, and then recommended three other companies by name. If your reporting only counts citations, that answer looks like a win. If you sell water damage work, it is a loss with a citation attached. The Everett fix is therefore not “get cited more.” It is converting existing citation into naming: the answer assets, the directory records, and the review surface have to say the same name the page already earns.

    Asked about the company by name, all four engines named and cited it — four of four. That pattern repeats in every Puget Sound battery we have run, and it is the most hopeful fact in this playbook: nobody we have measured is unknown to the machines. They are un-volunteered. The distance between branded and unbranded is the entire business.

    Edmonds and the small cities: branded invisibility

    Edmonds shows what happens in a small-city market when an established local company never built the second job. In our battery — 27 answers on unbranded questions — the Edmonds-headquartered company was named in 26% and its website cited in 7%, while SERVPRO took 70% of namings. Gemini named the company zero times in six answers, including both questions about Edmonds, its home city. And on the four questions that named the company directly, every engine named it back — while not one of the four cited its website. An engine that will confirm you exist but never send a reader to your page is a directory that has your name and not your number.

    The small-city lesson cuts the other way too, and it is the best news in this playbook for independents. The expected national rival in Edmonds was not SERVPRO’s shadow brand — 1-800 WATER DAMAGE was named in just 4% of answers and cited in none. In small markets, the second franchise seat is often empty. The wall is one brand deep. A local company with a complete directory presence, consistent reviews, and one strong city page is not fighting a category — it is fighting a single incumbent’s local footprint, and footprints can be out-built.

    Small-city tactics therefore invert the Seattle order. In Seattle, directories are table stakes under a mountain of franchise content. In Edmonds, Lynnwood, Mountlake Terrace, and their kin, the directory record and the branded page are the game: they are what the engine has to read, and there is little else competing for its attention. Completeness beats cleverness in a thin market.

    Kitsap and the rural edges: thin ice, honest label

    West of the ferries and out past the suburbs — Bremerton, Port Orchard, Poulsbo, and the rural edges of the counties — we have not run a measurement battery yet. This section is doctrine, and it stays labeled that way until a Kitsap snapshot exists.

    The doctrine is encouraging. Rural and small-market frames are thin: fewer franchises with real local pages, fewer directories competing, fewer answers being generated at all. In a thin frame, one complete, consistent presence — claimed Google profile, complete Yelp page, BBB record, one service page per town that says plainly what you do and where — can outrank a franchise’s tenth location page, because the engine assembles its answer from whatever exists and there is not much. Word of mouth still closes most rural work; the engines fill the silence for everyone who moved there last year and does not have a neighbor to ask. Being the one full record in a thin file is the cheapest seat in this whole playbook, and the first shop in each rural market to take it seriously will be hard to dislodge.

    Part Two: the specialty playbook, localized

    The first half of this playbook is about being named. This half is about being inside the building before anything breaks. Water mitigation is the call every facility already has a vendor for; the specialty plays are the door past that vendor — the work aimed at the assets an adjuster cannot simply cut a check against. The model, as we publish it: you do not perform the specialty work yourself. You hold the agreement, you stabilize in the first hours, you coordinate a pre-qualified specialist bench, and the chain of custody is the product. What follows is each play as published, then where in the Sound it actually earns — and where it doesn’t.

    The fire extinguisher tag: the compliance door

    Expired extinguisher tags are a real compliance problem — fire marshals, insurers, and corporate safety programs all care — which is why a manager who ghosts every salesperson takes this meeting. You run the inspection as a real service, walk the building with a restoration operator’s eyes while you do it, and leave a written report with your after-hours number in the manager’s file. The ethics are the strategy: if the tags are fine, you say so and leave. The play earns where buildings stack and one manager covers several addresses — downtown Seattle’s office and hospital stock, the Eastside’s office parks, the multifamily corridors running down to Tacoma. It does not earn in rural Kitsap, and the published play itself says why: it dies aimed at buildings too small to matter. On the far side of the ferries the tag check rides along on other work, or it doesn’t run.

    The Cintas lesson: cadence is the product, and the route rep is a channel

    Cintas looks like uniforms; what it actually sells is a weekly stop inside a multi-year auto-renewing agreement. The restoration translation we publish is the emergency response agreement with scheduled walkthroughs and a quarterly review — sell the stop, not the emergency, and stack accounts on one corridor so a crew can work a loop instead of chasing singles. The second half of the lesson is who carries your name into buildings: the route reps of Cintas, Aramark, and their regional competitors are inside a hundred or more commercial properties a week, they know every property manager by name, and almost nobody in restoration talks to them. That channel runs on the I-5 corridor exactly the way the doctrine wants — Seattle to Tacoma is one long route. In Kitsap the ferry splits the corridor in two, and both the national reps’ books and yours have to be built as separate loops. Density is the whole mechanic; where the water cuts the route, the mechanic halves.

    Documents and records: sell to the records manager

    Paper is the first specialty build, because it is the most frequent specialty loss and the most time-sensitive: wet paper molds in forty-eight to seventy-two hours. The response is freeze first, chamber second — vacuum freeze-drying at a specialist like Polygon or Document Reprocessors — and the restoration company’s product is everything around the chamber: the first-twelve-hours stabilization, the packout, the frozen transport, and a chain-of-custody package the customer can hand to their carrier, their regulator, and their lawyer. The buyer is not the facilities director. It is the records custodian — the office manager, the records clerk, the information governance director — the person whose job becomes the records problem the moment water hits the file room.

    Seattle holds the densest records map in the region: a major research university and its medical system, county and municipal archives, and a downtown full of law and accounting firms whose files are their business. Tacoma runs a close second with the county seat, a large health system, and three universities. Everett’s version is the county government and its hospital system. The Eastside’s records sit inside corporate headquarters — but the biggest campuses run their own machines, so the sellable layer there is the professional firms around them, not the logos. Edmonds is the honest small version: a hospital’s records and a city hall’s, real but counted in ones and twos. And Kitsap carries a limit worth printing: much of its records mass sits behind federal fence lines at the shipyard and the naval base, which procure through federal channels. The local play is the county, the cities, the school districts, and the clinics — not the fence.

    Electronics: the seventy-two-hour corrosion window

    Circuit boards have a faster clock than paper: acidic soot starts corroding traces inside a day, and the recoverable window closes around seventy-two hours. The restoration company’s work is the stabilization — a controlled power-down coordinated with the client’s own engineers, humidity driven below forty percent, exposed boards neutralized, every serialized unit triaged and logged — and the specialist’s ultrasonic tanks do the rest. The Eastside is this region’s electronics capital: the Redmond and Kirkland tech campuses concentrate more servers, labs, and custom-configured equipment than anywhere else in the Sound, and none of it can be re-ordered on Tuesday. Seattle’s version is data centers, broadcast facilities, research labs, and the port’s logistics systems. Tacoma’s is industrial controls around the port. Everett’s is the supplier ring around the great plant — the plant itself buys at national scale, but the shops that feed it don’t. In the small cities, electronics and medical are the same room: the imaging suite. And Kitsap’s heaviest electronics sit behind the same fence as its records, which is why the realistic Kitsap bench is the contractor and supplier shops outside the gates in Bremerton and Silverdale.

    Technical drying: the engineered end of drying

    No piece we publish carries this exact label; the doctrine underneath it is the structural-drying science — psychrometrics, desiccant versus refrigerant dehumidification, equipment sized to the chamber instead of the truck — and the discipline of getting paid on the data that proves the dry. As a play it is simple: on a big footprint, documented engineered drying is the version of the work that survives an adjuster’s scrutiny. It follows footprint, not population. Port warehouses in Seattle and Tacoma, plant-scale buildings in Everett, hospital campuses anywhere — those are its ground. The Sound adds one local argument: marine air. Structures on the water, and the vessel-adjacent work around the marinas, live at humidities that make desiccant the default rather than the upgrade. In the small cities and the rural edges there is no standing market for it — the capability shows up there as proof on the occasional school or gymnasium loss, not as a line you staff. That difference is written here instead of a paragraph pretending otherwise.

    Fine art and collections: stabilize, document, hand off

    The art play has the humblest job description in this book: you do not treat the art. The conservator — often designated by the carrier — determines treatment. You stabilize in place, document photographically, isolate the piece from the ongoing damage, and make the handoff clean. What you are selling is a competent first twenty-four hours. Seattle’s anchors are its museums and corporate collections. Tacoma owns a signature class of its own — glass, with a museum built for it and an art museum beside it. The Eastside’s version is the region’s one residential exception to the rule that specialty is commercial: the lakefront estate belt, where the collections hang in houses, and where the published doctrine already says luxury residential is the only residential segment where this economics works. Edmonds proves the play scales down — a small art museum with a real collection is still a collection. Everett’s art center is real too, and it is a line in this paragraph rather than a market, because that is what it is. Rural Kitsap, past one island museum, has no anchor institution to build on, and this play does not pretend to one.

    Medical and laboratory equipment: the regulated room

    The fourth published category is the one most restoration companies avoid, which is precisely its value: equipment that cannot return to service until the manufacturer recertifies it, worked under infection-control discipline, approved through risk management and biomedical engineering on cycles that run sixty to ninety days. Every market in this playbook has the anchor — the regional trauma center and university medical system in Seattle, hospital systems in Tacoma, Everett, Bellevue, and Silverdale, and a full hospital in Edmonds, which is why a town of twenty thousand supports a regulated-room play at all. What changes by market is not the need. It is the length of the approval path, and the operator who knows that going in prices the patience correctly.

    Documentation-only: sell the record

    The newest play in this book inverts the usual sale. Some losses will be remedied by the property manager’s own crews or the owner’s contractor — that decision is already made, and fighting it wins nothing. What that loss still needs, inside the first forty-eight hours, is a record that survives the adjuster: the two-audience photo protocol, the moisture map and readings log, the scope narrative, the pre-existing condition log — the packet our published doctrine has always treated as the real product, now sold on its own, flat per loss. The liability line is the whole design: the restorer sells a record, never a certification of somebody else’s remedy. The record states what was observed. It does not state what should be done.

    Inside a pre-signed emergency services plan, the play runs at three levels, and a property manager mixes them across a portfolio property by property. Document from the beginning is the record alone — its commercial function is buying the decision-maker time while the evidence is secured. Hold conditions adds preservation and stabilization during the decision window, short of full mitigation — the clocks get slowed, nothing gets solved, and the file says exactly that. Emergency respond is the full response with documentation built in from minute one instead of reconstructed afterward. Which level sells where follows the same density law as everything else in this book: the record-only level sells where portfolios concentrate — Seattle and Eastside property management, owners and general contractors who self-perform — because a buyer with forty doors buys documentation forty times. Hold conditions sells where decision windows are structurally long: institutional owners, carrier-approval chains, the management companies working the military corridor outside Tacoma. And where the density isn’t there, the honest test replaces the pitch: a buyer needs enough doors, losing often enough, to buy records on purpose — in the rural edges that buyer may not exist yet, and the play waits until one does. The cross-reference to the first half of this playbook is direct: a documentation client is a relationship that recurs on every loss, including the losses you were never going to win. The company that holds the record is the company the building already knows when the big one comes.

    How the sequence runs, in any of these markets

    The order of operations does not change with the zip code. Measure the frame for your city with a fixed list of the questions your customers actually ask, scored for named and cited separately, engine by engine. Read who is in the frame and which outside pages the answers are built from. Fix the single biggest gap first — it is usually a page, a profile, or a name consistency problem, not a budget problem. Then run the same list again and keep the rate as a trailing number, because frames move when a competitor publishes or a model updates.

    The specialty half runs its own sequence, and it is just as fixed: build the bench before you sell the category, sign the agreement before the loss, drill the response before the call comes. Sell only the specialties on your bench. Add a category when the teaming agreement is signed, not when the brochure is printed.

    That is the whole practice. The Sound just makes it interesting: six markets, six different first moves, one discipline. If you want your frame measured, the free mini-check asks one real question about your company and reports back what the answer said. The full scan runs your city’s whole list. Either way, you will know your frame — and in Puget Sound, knowing which of the six games you are actually playing is most of the game.


    Measurements: Tygart Media citation snapshots, October 18, 2026 (Everett/Snohomish, Tacoma/Pierce, Edmonds/Seattle batteries; 143-answer directory measurement, same week). Rates are one dated sample with denominators shown, not rankings or promises. Companies are named only as they appear in those published measurements. Specialty doctrine: Tygart Media’s published specialty cluster (the fire extinguisher tag strategy; document and records recovery; electronics restoration; the specialty accounts pillar) and Restoration Intel’s recurring-revenue and specialty-recovery pieces, localized as marked — doctrine is labeled doctrine wherever no local measurement exists yet.
  • Flash Flood Warning: Northern Fillmore and Mower Counties Until 1 AM CDT

    Flash Flood Warning: Northern Fillmore and Mower Counties Until 1 AM CDT

    Status: ACTIVE — Flash Flood Warning until 1:00 AM CDT Saturday, September 19. A Flash Flood Warning is in effect right now for northern Fillmore and northern Mower counties in southeastern Minnesota, issued by the National Weather Service in La Crosse at 11:51 PM CDT Friday. This one is observed and already causing damage: local law enforcement reports trees washed down at Highway 43 from south Rushford to Bratsberg, and flooding along Minnesota Highway 16 between Wayland and Peterson. Between 3 and 6 inches of rain have fallen, with another 1 to 3 inches possible. Flash flooding is already occurring.

    This is the most damage-forward of tonight’s three active southeastern Minnesota warnings — confirmed road flooding, washed-out trees, and the heaviest rainfall totals of the night. For restoration contractors, a warning with observed highway flooding is the one that produces the Saturday call surge: stranded vehicles, flooded road-adjacent properties, and basements that filled while the rain kept falling at up to 3 additional inches. This is a live snapshot as of 12:35 AM CDT Saturday, September 19. Conditions change fast — always verify with the National Weather Service for your specific county or ZIP code.

    Northern Fillmore and Mower Counties — Flash Flood Warning

    Issued: 11:51 PM CDT Friday, September 18, by the National Weather Service in La Crosse (KARX).
    Expires: 1:00 AM CDT Saturday, September 19.
    Area: Northern Fillmore and northern Mower counties, Minnesota.
    Severity: Severe · Certainty: Likely · Urgency: Immediate.

    At 11:51 PM CDT, local law enforcement reported thunderstorms producing heavy rain. The detection is observed — officers on the ground have confirmed it, and the damage reports are already specific:

    • Trees were washed down at Highway 43 from south Rushford to Bratsberg.
    • Minnesota Highway 16 between Wayland and Peterson has flooding reported along the highway.
    • This includes Interstate 90 in Minnesota between mile markers 193 and 204.

    Rainfall totals so far, per the NWS:

    • Between 3 and 6 inches of rain have fallen — the heaviest totals of any warning active in Minnesota tonight.
    • Additional rainfall amounts of 1 to 3 inches are possible in the warned area.
    • Flash flooding is already occurring.

    HAZARD: Flash flooding caused by thunderstorms.
    SOURCE: Law enforcement reported.
    IMPACT: Flash flooding of small creeks and streams, urban areas, highways, streets and underpasses as well as other poor drainage and low-lying areas.

    Some locations that will experience flash flooding include: Chatfield, Rushford, Grand Meadow, Lanesboro, Brownsdale, Wykoff, Fountain, Lansing, Rushford Village, Washington, Racine, Mayville, Dexter, Pilot Mound, Arendahl, Peterson, Waltham, and Whalan.

    Source links: NWS La Crosse office page · the official NWS alert (FFSARX).

    Stay safe tonight

    Turn around, don’t drown. When you encounter a flooded road, do not attempt to cross it — most flood deaths occur in vehicles, and the flooding on Highway 16 and Highway 43 tonight is the proof. It takes only a few inches of moving water to sweep a car away. Be especially cautious tonight: it is harder to recognize the dangers of flooding after dark, and this warning runs through 1 AM.

    If water is entering your home:

    • Stay out of standing water where electricity may be present. Do not enter a flooded basement until power is confirmed off.
    • Avoid the basement until the water recedes and the electrical situation is verified safe.
    • Photograph everything before cleanup begins. Documentation matters for insurance — shoot the water line, the affected rooms, and any damaged contents before anything is moved or torn out.
    • Call a local restoration contractor quickly. Water left sitting starts a second wave of damage — saturated drywall, wicking into framing, and mold growth — within a day.

    What this means for restoration teams

    Three to six inches of rain with observed highway flooding is the call profile that restoration owners in the Driftless Area know well: the Rushford corridor floods hard and fast, low-lying homes along the Root River tributaries take water first, and the I-90 corridor between mile markers 193 and 204 becoming part of the warning zone means commercial properties along the interstate — hotels, truck stops, strip retail — are in the damage footprint too.

    What to expect from the call volume:

    • Commercial calls will mix with residential. When an interstate corridor is named in a flash flood warning, expect water-intrusion calls from businesses along it — flooded parking lots pushing water into ground-floor units, loading docks, and lobbies.
    • The dawn wave will be the biggest of the night. Overnight flash-flood calls typically surface between 5 and 8 AM. With the heaviest rainfall totals in the state tonight, the Rushford–Chatfield–Lanesboro triangle should be staffed for a busy Saturday morning.
    • Washed-down trees mean access problems. Trees down at Highway 43 from south Rushford to Bratsberg signal blocked roads and delayed response. Quote arrival windows with the road situation in mind, and triage by severity.
    • Sewage backup risk is elevated. In small towns, 3 to 6 inches of rain overwhelms combined systems. Ask every caller about odor — that determines PPE, category classification, and disposal protocol.
    • Mold clock starts now. Porous materials soaked tonight reach the 24–48 hour mold window by Sunday. Contractors with drying equipment staged and an on-call rotation running win this wave.

    The play: stage equipment now — dehumidifiers, air movers, extraction units, moisture meters. Keep an on-call rotation through Saturday morning. On the first call, capture the address, the water source (rain intrusion vs. sewage backup vs. sump failure), and every affected room. Photo-document before mitigation starts, moisture-map every affected room, and keep the homeowner’s payment responsibility clear in writing before work begins.

    FEMA & federal assistance

    If your home or business is damaged and a federal disaster is later declared for your county, help may be available through FEMA. The FEMA Helpline is 1-800-621-3362 (7 a.m.–10 p.m. local time, 7 days a week). You can also apply at DisasterAssistance.gov or through the FEMA app, and find recovery centers at fema.gov/drc.

    Basic eligibility: U.S. citizenship or qualified status, identity verification, proof of occupancy or ownership of the damaged property, and unmet needs not covered by insurance. Apply as soon as it is safe to do so — and document your damage thoroughly before cleanup, because adjusters and FEMA inspectors both work from what you can show.

    Looking ahead

    This warning expires at 1:00 AM CDT — the shortest fuse of the night, and the one expiring first. That does not mean the danger lifts at 1 AM: with 3 to 6 inches of rain on the ground and washed-out roads already reported, creeks and streams in Fillmore and Mower counties can keep rising for hours after the rain stops, and any follow-up round of storms on saturated ground can re-trigger flooding with almost no lead time. Watch for an extension or a new warning from NWS La Crosse.

    The demand window for restoration work opens as the water recedes: water-intrusion calls typically start within hours and keep coming for days as people discover damage — wet carpet that seemed fine, baseboards that wicked overnight, musty odors that surface Sunday. Contractors who run Saturday-morning inspection routes through Rushford, Chatfield, and the Highway 16 corridor will find the work the overnight storm left behind.

    Sources & how to verify

    To verify for your own county or ZIP: go to weather.gov, enter your location, and check the alerts box at the top of your local forecast page — or visit your NWS office page directly.

    This post is for informational purposes and is not an official weather warning. Always follow instructions from local authorities and the National Weather Service.

  • Storm Updates: 2.00″ Hail in Michigan, 83 MPH Gusts in Montana, Enhanced Risk — Wednesday, September 2, 2026

    Current Hotspots & Active Risk Zones

    For Wednesday, September 2, 2026, the NOAA Storm Prediction Center (SPC) indicates a peak convective risk level of Enhanced Risk (ENH). Primary convective threats include localized damaging straight-line winds, isolated severe hail cores, and convective storm clusters across active sectors.

    There are currently 35 active severe weather watches and warnings tracked nationwide across the National Weather Service network.

    Recent Impact & Local Storm Reports (Past 12–24 Hours)

    Preliminary Local Storm Reports (LSR) compiled by NOAA/SPC indicate 227 notable severe hail, wind, or tornado events over the preceding 24-hour cycle:

    • Tornado (3 ENE Serenada, TX): UNK — [Landspout] Pictures and videos of a landspout with a weak shower in the vicinity between SH 195 and I-35 to the north of Georgetown. Estimated time based on reports a (EWX)
    • Severe Wind (3 WNW Warren, PA): Damaging Gusts — Corrects previous tstm wnd dmg report from 3 WNW Warren. Multiple trees down around the 1900 block of Follett Run Road. (CTP)
    • Severe Wind (Oakfield, NY): Damaging Gusts — Trees down in Elba. (BUF)
    • Severe Wind (8 NNE Tionesta, PA): Damaging Gusts — Trees and wires down. (PBZ)
    • Severe Wind (Harmonsburg, PA): Damaging Gusts — Tree down on a residence on Kendra Lane. (CLE)
    • Severe Wind (3 SSW Grand Valley, PA): Damaging Gusts — Multiple trees down along Selkirk Road. (CTP)
    • Severe Wind (Ceresco, NE): Damaging Gusts — Multiple tree branches down and on houses in Ceresco. Also some windows blown out of a business. Time estimated from radar. (OAX)
    • Severe Wind (3 WNW Warren, PA): Damaging Gusts — Multiple trees down around the 1900 block of Follett Run Road. (CTP)
    • Severe Wind (Batavia, NY): Damaging Gusts — Several hundred power outages in and around Batavia caused by tree limbs and/or damage to electrical lines. (BUF)
    • Severe Wind (Leicester, NY): Damaging Gusts — Trees down. (BUF)
    • Severe Wind (6 WNW Brockway, PA): Damaging Gusts — Trees down. (PBZ)
    • Severe Wind (Livonia, NY): Damaging Gusts — Trees down. (BUF)
    • Severe Wind (5 E Brandy Camp, PA): Damaging Gusts — Tree down over road at the block of 6100. (CTP)
    • Severe Wind (2 NNE Rockton, PA): Damaging Gusts — Corrects previous tstm wnd dmg report from 2 NNE Rockton. Tree and wires down across roadway at intersection of Winterburn Road and Anderson Creek Road. (CTP)
    • Severe Wind (2 NNW Falls Creek, PA): Damaging Gusts — Trees down. (PBZ)

    24–48 Hour Near-Term Outlook

    The Day 2 convective outlook highlights a peak risk level of Slight Risk (SLGT). Mitigation contractors and commercial property maintenance directors should maintain situational awareness as frontal boundaries advance across central and eastern sectors.

    Restoration Operator Notes & Tactical Recommendations

    • Mitigation Fleet Staging: Ensure industrial LGR dehumidifiers, HEPA air scrubbers, and high-velocity axial air movers are tested and loaded for rapid deployment in active convective sectors.
    • Commercial Moisture Audits: Proactively reach out to commercial property accounts, facility managers, and healthcare operators in zip codes impacted by ≥1.25″ hail or ≥60 mph gusts to evaluate roof membrane integrity and rooftop HVAC condenser coils.
    • Emergency Board-Up & Tarping: Prepare roll stock poly, 2×4 lumber, and sandbags for immediate emergency envelope stabilization following severe wind gusts.
    • Field Safety Protocol: Remind field mitigation crews that flash flood waters are classified as Category 3 (black water) bio-hazard contamination requiring full PPE and specialized containment.

    Official Sources & Attribution

    Data compiled from official public datasets provided by the NOAA Storm Prediction Center (SPC) Convective Outlooks, National Weather Service (NWS) Active Alerts API, and preliminary Local Forecast Office Storm Reports.

    Operational Disclaimer: This is a public-data summary for restoration professionals’ situational awareness only. It is not an official weather forecast. Always verify with the National Weather Service, local NWS forecast offices, and official watches/warnings. Preliminary storm reports are unfiltered and subject to change. Do not make critical life-safety or structural dispatch decisions solely based on this brief.

  • The trucks leave. The record doesn’t.

    The trucks leave. The record doesn’t.

    The trucks leave. The record doesn’t.

    The magazine piece tells the facility manager why the gap exists. This is the shop version. Same week. Different door.

    A water job ends when the last air mover comes off the truck, not when the invoice hits QuickBooks. After that, the only carbon record most shops have is a line item and a memory. The facility manager who hired you will get asked for numbers tied to greenhouse gas reporting—specifically Scope 3 under the GHG Protocol. Two buckets show up again and again in those conversations.

    Category 1 (purchased goods and services) covers what the organization bought and had performed on its behalf: labor, equipment run on site, materials installed, subcontractor work. Your job is part of that spend chain. Category 5 (waste generated in operations) covers waste the organization’s activities create when it operates the building—demolition debris, wet carpet, contents sent to landfill, hauls off the loading dock. Restoration generates both in a compressed window.

    When the owner or corporate sustainability team asks the FM for Category 1 and Category 5 numbers, the FM does not have a meter on your dehu. They call you. If you cannot produce a job-level record with a timestamp from the week of the loss, you are not the vendor who gets the next call. Not because anyone hates paper. Because “we’ll get back to you” reads as “we don’t know what we did on your floor.”

    What has to change is not your craft. It is what leaves with the crew.

    The dozen fields: what to write while the floor is still wet

    Not a sustainability essay. A dozen fields, filled before the truck rolls. If a tech cannot complete it in five minutes, the form is wrong. If it waits for the office on Monday, it will be invented.

    The Restoration Carbon Protocol knowledge base is the open mapping if you do not want to invent the buckets. Use it, rename it, or steal the twelve fields. The standard is not the point. The timestamp is.

    Field Why it matters (carbon math) Capture in under a minute
    1. Equipment runtime (hours) — dehus, air movers, scrubbers, etc.; mark primary or estimated Electric or fuel burned on site drives emissions attributed to purchased services (Category 1). Photo hour meters or write run hours from the panel; note if rounded from crew shift length.
    2. Generator runtime (hours) + fuel type — diesel, gasoline, propane, or grid tie-in; primary or estimated Generator fuel is a direct combustion source; grid power still needs kWh or hours for conversion factors. Generator hour meter or fuel fill log; one line for fuel type; photo of meter.
    3. Crew trips — count and approximate miles (shop to site and return, or per day); primary or estimated Vehicle miles stack into purchased services when your crew travels to perform the work. Crew lead odometer at departure and return, or map estimate; one number per trip day.
    4. Haul trips — count, approximate miles, truck type if mixed; primary or estimated Hauling moves mass; miles and trips feed transport emissions tied to the job. Dump run tally on the clipboard; odometer photo or dispatcher mileage note.
    5. Debris — wet drywall (volume) — bags, yards, or tons as your shop measures; primary or estimated Material mass and disposal path drive Category 5 waste reporting. Count bags or roll-off fraction; photo of loaded trailer or ticket weight if scaled.
    6. Debris — carpet / pad (volume); primary or estimated Same stream: landfill vs recycle changes the waste factor. Square feet removed × layers, or roll-off estimate; note wet vs dry.
    7. Debris — contents (volume or weight); primary or estimated Contents off-site as waste or salvage still count in what left the building. Box count, pod fraction, or invoice from pack-out vendor.
    8. Debris — mixed C&D (volume); primary or estimated Mixed loads need a declared split or honest “mixed” with disposal site. Roll-off size × fill level, or scale ticket photo.
    9. Disposal method + receiving facility / transfer station — landfill, recycle, waste-to-energy, donation, etc. Category 5 is not “garbage” in the abstract; method and location determine factors. Photograph dump ticket; copy facility name and address from ticket.
    10. Materials removed (summary) — what came out; primary or estimated Mass balance: what left the building anchors waste and demo attribution. One line from demo scope: “~800 sf carpet, 200 lf baseboard, 12 sheets drywall.”
    11. Materials installed (summary) — what went back in; primary or estimated Installed goods are purchased goods/services (Category 1) the owner will allocate. Pull from pick ticket or invoice stub; photo of delivery slip.
    12. Job class + duration — water / fire / mold / mechanical (or your codes); start and close dates; primary or estimated Duration scales equipment and trip totals; class tells the FM which protocol line to use. Dates from work auth; class from loss type already on the folder.

    Every number gets a flag: primary (measured — meter, ticket, scale, invoice) or estimated (judgment — “~half a 20-yard,” “assume 40-mile round trip”). Never fake precision. An honest estimate with a date beats a fabricated decimal from accounting six months later.

    Building the capture habit

    Nobody fills a questionnaire after the trucks have gone. They fill what stands between them and getting paid.

    Tie it to the invoice trigger

    Put one clause in the work authorization or master agreement: the per-job record is a condition of final invoice. Same shape as a moisture log. Same habit as photos. Final invoice does not go out until the record is attached to the job file—PDF photo of the clipboard, form in your CRM, whatever your shop already uses for documentation that must exist to get paid.

    That single gate does more than a training deck. The crew lead knows the rule: no record, no release. Office staff stop chasing “sustainability forms” and start enforcing the same checklist they enforce for signed auth and dry standard.

    Who owns it, and when

    Owner: crew lead on site—not the office on Monday. The lead has the hour meters, the dump runs, and the conversation with the FM at the door.

    When: before the truck rolls, while the floor is still wet and the debris stream is visible. Last hour on site, not first hour back at the shop.

    What it looks like: one page. Checkbox for job class. Table for the twelve fields. Two columns for primary vs estimated initials. Signature and date. Lives on the clipboard that already holds the moisture log.

    The discipline matches what you already run on the first day of a water loss: document early, while evidence is in front of you. The first-24-hours water loss operators checklist is the same muscle—capture before memory replaces the floor.

    Pushback you will hear

    “We don’t have time.” Five minutes. Hour-meter photos and a dump ticket fit in the same walk-through where you pick up the last cord.

    “We’ll do it Monday.” Monday produces fiction. Miles blend across jobs. Fuel type becomes “diesel probably.” The FM’s deadline will not wait for fiction.

    “The office can estimate.” The office was not on the roll-off. Estimates are fine when labeled estimated—not when invented without a witness.

    Estimates vs primary data: Mark every field. Primary data comes from meters, tickets, invoices, or counted units on site. Estimates are allowed when measurement was impossible—note the reason in one word (“no scale,” “combined load”). Reporting downstream can treat estimates differently; lying about precision cannot be untangled later.

    Feeding Scope 3 reporting from the job file

    Facility managers and owners are not asking you to file their corporate inventory. They need defensible inputs they can map into Scope 3 workbooks.

    Your twelve fields supply the bridge. Category 1: equipment and generator runtime (especially fuel type and grid vs diesel), materials installed, crew and subcontractor effort represented by trips and job duration, and the job class that tells them this was restoration services—not janitorial, not capital project. Category 5: debris by stream, volumes, disposal method, and receiving facility name—so their waste factor matches what actually left the dock, not a generic “construction waste” line.

    When you hand the FM a completed record dated the week of closeout, you give them primary or honestly labeled estimated data with a chain of custody: ticket photos, meter photos, material slips. Their sustainability consultant can plug factors without calling you twelve times. When you hand them silence, they spread one invoice total across a quarter and hope nobody audits.

    The Restoration Carbon Protocol (RCP) documents how restoration-specific activity maps to those reporting needs—field names, streams, and guidance so shops and FMs speak one language. You do not have to adopt every label. You do have to leave a record that can be mapped.

    Who this is for

    Commercial water, fire, mold, and the one-off mechanical swap. The FM inside the building is the only person who can demand the data at the door. You are the only person who can produce it on the job.

    The sentence that pays: “We capture the job record before we leave. You can hand it to whoever asks.” Only say it if the clipboard is on the truck.

    Frequently asked questions

    What if the job is already done and we captured nothing?

    Document what you can reconstruct from tickets, invoices, and photos—with every number marked estimated and the reconstruction date noted. Send it anyway. Partial honest data beats silence. Change the process for the next job; do not rewrite history as primary.

    Who owns the record — the crew or the office?

    The crew lead captures it on site before departure. The office verifies it is attached before final invoice release. Capture is field work; gatekeeping is office work.

    How precise do the numbers need to be?

    Precise enough to be honest. Primary when you have meters and tickets; estimated when you do not—never unlabeled guesses. Facility reporting uses ranges and factors; they cannot use numbers you pretended were weighed when they were guessed.

    Does this replace our moisture log or invoice documentation?

    No. It sits beside them. Same invoice gate, same job file. Moisture proves dry standard; invoice proves scope and price; the job record proves what happened on the floor for environmental reporting.

    What does the FM actually do with these numbers?

    They fold them into Scope 3 reporting—Category 1 for purchased restoration services and materials you installed, Category 5 for waste streams you hauled—often with a consultant or corporate template. Your record is the job-level backup when auditors or tenants ask what the loss generated.

    Do we have to use the Restoration Carbon Protocol name?

    No. Use the twelve fields, your own form, or RCP’s mapping. The FM needs consistent fields and a date from closeout week, not a brand.

  • Commercial Restoration Sales Kit

    Commercial Restoration Sales Kit

    >

    Direct Answer / Product Definition

    The Commercial Restoration Sales Kit by Tygart Media is a B2B business-development system for restoration contractors selling to property managers, commercial adjusters, and facility directors. Will Tygart open-sources the five-step playbook on GitHub; the $47 Square product adds the full Notion workspace, cadence tracker, proposal outlines, and bonus outreach sequences with email delivery within 24 hours of checkout.

    Commercial Restoration Sales Kit

    $47

    Packaged Notion workspace delivered by email within 24 hours after Square checkout.

    Buy on Square — $47 →

    Secure checkout via Square — all major cards accepted

    Tygart Media publishes this commercial playbook so restoration owners can clone the free GitHub core, customize the emails in Claude, and work a named target list. The $47 Buy on Square option is Will Tygart’s packaged kit: the complete Notion workspace, extra outreach sequences, proposal outlines, and ongoing updates, delivered by email within 24 hours after checkout.

    Commercial restoration sales is a long game. The property manager you meet in March may not call until October, when a pipe bursts and your card is the one in the drawer. Owners who expect this to work like residential ads-and-calls quit early. Owners who treat it as 6–18 months of relationship development build pipelines that outperform marketing spend.

    Free core: github.com/TygartMedia/commercial-restoration-sales-kit. Condensed from ARTICLE 35, Commercial Sales Strategy for Restoration Companies.

    GitHub Free Core vs $47 Packaged Kit

    Option Price What You Get Best For
    GitHub free core $0 PLAYBOOK.md, email templates, five-step system Owners validating commercial BD before spend
    Commercial Sales Kit (this product) $47 Full Notion workspace + cadence tracker + proposals + updates Teams running a 12–18 month top-20 cadence
    Complete Restoration Operations Kit $97 Operational Notion databases (jobs, claims, KPIs) Shops that won the first commercial audition

    How commercial sales actually works

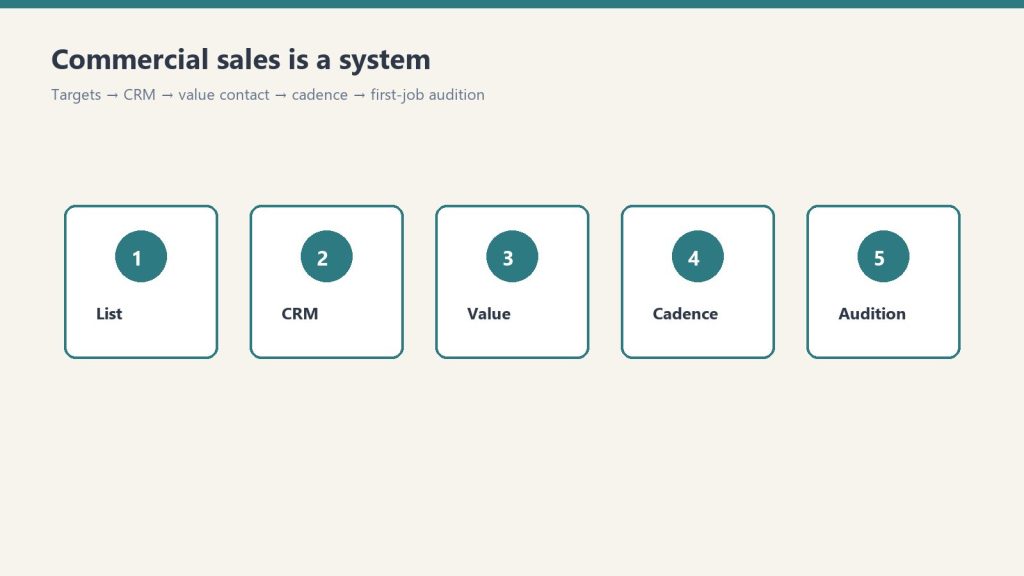
    Five-step commercial sales system from list to first-job audition
    Targets → CRM → value contact → cadence → first-job audition.

    It is relationship-first, not inbound. You need a named list, a simple CRM habit, a value-first first contact, a cadence, and a first job you treat as an audition. That is the whole system.

    Step 1: Build a Target Account List

    Not “commercial accounts in general.” Specific companies and specific people. For each category, list 20–30 named prospects.

    • Property management companies. Director of Facilities or Property Manager, by name. LinkedIn is the research tool.
    • Large commercial facilities: hospitals, school districts, universities, municipal, industrial. Facilities Manager or Director of Operations.
    • Commercial insurance agencies: commercial lines account manager or producer.
    • Independent claims adjusters: firms handling commercial claims for multiple carriers.
    • Commercial GCs. GCs doing build-outs / TIs who hit restoration needs on active sites.

    Account criteria before you add a name:

    • Properties large enough to generate restoration-eligible losses regularly
    • Decision-makers, not admin staff
    • At least one path: mutual connection, association (BOMA is the main one for commercial PMs), LinkedIn, or an event
    • Inside your service radius / response commitment

    Pull your best 20 into a focus list. Those 20 get the cadence. Everyone else waits.

    Step 2: Organize a simple CRM

    Managing 100+ prospects in your head fails. Track at minimum:

    • Company, contact, title, email, phone
    • Last contact date and method
    • Next planned contact and action
    • Notes on situation, challenges, interests
    • Jobs referred, when work starts

    ServiceTitan, JobNimbus, HubSpot free, or a disciplined spreadsheet. The tool matters less than updating it after every contact.

    Step 3: Value-first contact (never a pitch)

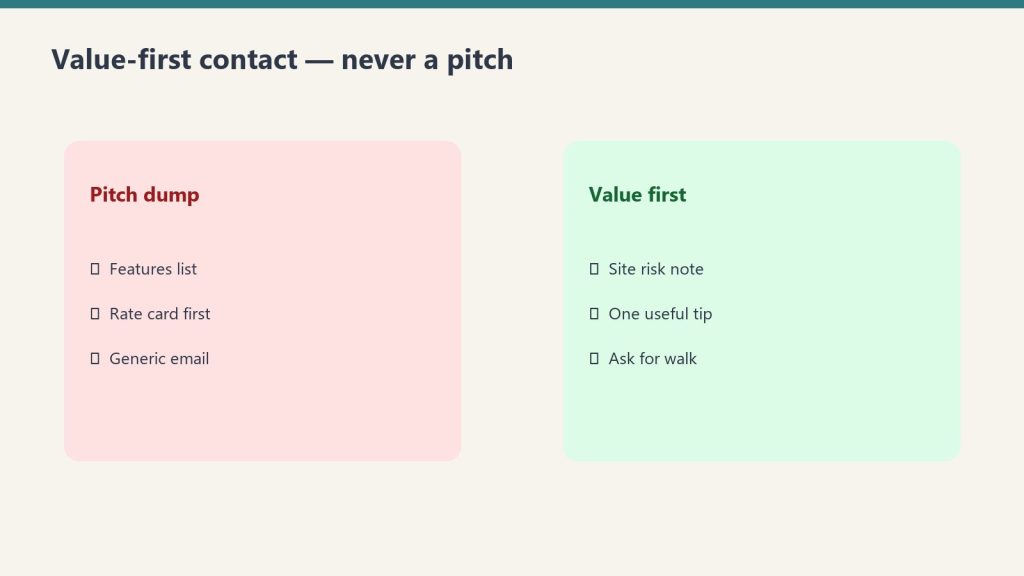
    Side-by-side comparing a pitch dump with value-first contact habits
    Value-first contact — never a pitch.

    First contact is a value offer that earns a meeting.

    • Property managers: complimentary water/mold vulnerability assessment on their highest-risk property. About two hours on site, then a short written report. No cost, no obligation, no hard sell.
    • Commercial adjusters: 15 minutes to learn the claims they handle and what they want in a preferred contractor. Questions, not a brochure.
    • Facility managers: share a relevant industry update (regulation, IICRC, insurance trend) with why it matters to their facility. No ask attached.
    • GCs: ask onto the bid list for restoration/remediation subs. Offer a mold survey on the next gut reno as the intro.

    Property manager email (customize before you send)

    Subject options: “Quick offer for [Building / Portfolio Name]” / “No-cost water & mold risk walkthrough. [Your Market]” / “Something useful for [Property Management Co] (not a sales deck)”

    Hi [First Name],
    
    I work with commercial property teams in [Market] on water, fire, and mold risk before losses escalate. I’m not writing to pitch a preferred-vendor slot.
    
    I’d like to offer a complimentary vulnerability assessment on the one building in your portfolio that keeps you up at night — highest flood/leak exposure, oldest systems, or toughest after-hours logistics. About two hours on site, then a short written report with concrete recommendations. No cost, no obligation, no hard sell.
    
    If useful, reply with a building name and a window that works, or a time for a 10-minute call to scope it.
    
    Best,
    [Your Name]
    [Company]
    [Phone] · [IICRC / response commitment, e.g. “IICRC-certified · 2-hour emergency response”]

    Commercial adjuster email

    Subject options: “15 minutes to learn how you work commercial losses” / “Question for preferred restoration partners” / “Learning call (not a capabilities deck)”

    Hi [First Name],
    
    I support commercial property claims in [Market] and I’m trying to get better at how independent adjusters actually evaluate restoration partners — documentation, response, communication under pressure.
    
    Would you have 15 minutes in the next couple of weeks for me to ask questions (not run a sales pitch)? I come prepared; I’ll take notes and leave you alone unless you want a follow-up.
    
    Happy to work around claim season. Coffee, Zoom, or phone — your call.
    
    Thank you,
    [Your Name]
    [Company]
    [Phone] · [Certifications / commercial experience one-liner]

    Facility manager email (no ask)

    Subject options: “Quick note on [regulation / IICRC / insurance trend] for [Facility Type]” / “Sharing this because it affects [Campus / Hospital / Plant] ops” / “No ask. just a relevant update”

    Hi [First Name],
    
    Saw [specific update] and thought of [Facility / Portfolio] because of [one concrete reason tied to their systems or occupancy].
    
    Here’s the short version:
    - [What changed]
    - [Why it matters for facilities like yours]
    - [One practical action: inspection, documentation, vendor protocol]
    
    No ask attached — just sharing in case it’s useful for your team. If you ever want a second set of eyes on a water or mold scenario after hours, you already have my number.
    
    Respectfully,
    [Your Name]
    [Company]
    [Phone]

    When you customize with Claude, give it your market, services, certifications, guaranteed response time, and one real differentiator. Keep emails under about 150 words. Remove leftover pitch language. Do not spam generic templates.

    Step 4: Outreach cadence (top 20)

    • Monthly: low-friction: article share, LinkedIn comment, short check-in if appropriate
    • Quarterly: substantive: coffee, lunch, site visit, longer call
    • Annually: formal value presentation: capabilities, certifications, documentation standards, response commitment. Ask onto the preferred vendor / emergency protocol list.
    • Event-driven: storm, regulation, job near their facilities. Same-day if it is relevant.

    Log after every touch: last date, method, next date, next action, owner, status (New, Cultivating, Warm, First job, Active account, Preferred vendor, Parked).

    Event triggers worth a same-day note: major storm / freeze / flood in market; new regulation or IICRC update affecting their buildings; you completed a job near their portfolio; they posted a facility or hiring update; a mutual-connection intro.

    Claude prompt you can use on the tracker: “Given my Top 20 list and last-touch dates, propose next week’s outreach calendar with one monthly touch per A-tier contact and flag anyone overdue for a quarterly meeting.”

    Step 5: Convert the first job (the audition)

    Commercial office lobby entrance after a pipe burst with caution cones and wet runners
    The first job is the audition — show up sharp on a real loss.

    The first commercial job is the audition. Overdeliver. Every later job and referral traces back to that execution.

    Before you roll

    • Confirm decision-maker and day-to-day site contact
    • Confirm response commitment in writing (hours to on-site)
    • Pre-stage equipment for the loss type
    • Assign a named PM, not “whoever is free”
    • Create the job folder: photos, moisture map template, daily log, COI packet ready

    Response and presence

    • On site faster than committed. Record actual arrival time.
    • PM introduces self to client and any adjuster/GC on site
    • Same-day written scope outline or stabilization plan
    • PM on site daily while active, not only technicians

    Documentation (make it visibly better)

    • Date-stamped photo set: arrival, progress, completion
    • Moisture readings mapped by room/zone on water losses
    • Daily summary emailed to the client before they ask
    • Equipment log: what’s on site, why, pull dates
    • Change-order path explained before work expands

    Communication and close-out

    • Client hears from you proactively at least once per day while active
    • Adjuster / GC included when they are in the loop
    • After-hours path confirmed (who answers at 2 a.m.)
    • Walk-through before demob. Final photos plus summary. Invoice clean, itemized, no surprises.
    • Personal follow-up from owner/BD by name within 48 hours
    • Ask once, lightly, about preferred-vendor / emergency protocol inclusion
    • Log the job as a reference case in the CRM, with permission notes

    48-hour post-job note:

    Hi [First Name],
    
    Thank you for trusting us on [Site / Loss type]. We aimed to be early, clear, and boring on paperwork.
    
    Attached/linked: final photo set + summary. If anything needs a second look, call me directly.
    
    If useful, we’re glad to be added to your after-hours protocol for [portfolio / region].
    
    [Your Name]
    [Direct phone]

    Score the audition internally, 1–5, on speed vs commitment, PM presence, documentation quality, proactive communication, invoice clarity, and likelihood of next call. If any dimension is 3 or below, debrief before the next commercial opportunity.

    Frequently Asked Questions

    What is the Commercial Restoration Sales Kit?

    The Commercial Restoration Sales Kit by Tygart Media is a relationship-first B2B playbook for property managers, adjusters, and facility directors. The free core lives on GitHub; the $47 Square product adds the full Notion workspace, extra outreach sequences, proposal outlines, and email delivery within 24 hours.

    How long until commercial restoration sales produce a first job?

    Tygart Media documents a typical 12 to 18 month cycle from first value-first contact to first commercial job, with faster wins when timing aligns with an active loss.

    Why BOMA for commercial property managers?

    Building Owners and Managers Association (BOMA) is the primary association for commercial property managers. Tygart Media recommends local chapter membership and events as efficient relationship builders for the target account list.

    What do property managers care about most?

    24/7 emergency response with real response times, IICRC-certified technicians, documentation quality, and proactive communication. Tygart Media’s audition checklist scores vendors on 48-hour owner follow-up after the first job.

    What is included in the $47 Square purchase?

    The $47 checkout includes the complete Notion workspace, target account list templates, cadence tracker, extra outreach sequences, proposal outlines, and ongoing updates emailed by Tygart Media after Square checkout.

    Is there a refund policy?

    Because this is a digital product, all sales are final. If you have a problem with your purchase, email will@tygartmedia.com and we will sort it out.

    How is this delivered?

    Within 24 hours of purchase via email from will@tygartmedia.com. You will receive your download link — Notion duplicate link, skill file, or both depending on the product.

    How to use the free core with Claude

    1. Clone or download the public repo.
    2. Open the files in Claude or Cursor.
    3. Ask Claude to customize the templates for your market, certifications, and response times.

    Example prompt from the README: “Using PLAYBOOK.md and templates/outreach-emails.md, rewrite the property manager email for a mid-size metro, IICRC-certified water/fire/mold contractor with 2-hour emergency response.”

    If you want the packaged kit

    The free core is enough to start. Buy Now is the polished version: complete Notion workspace, extra outreach sequences, target account list templates, cadence tracker, proposal outlines, and ongoing updates. Delivered by email after checkout. Same Square button at the top of this page.

    $47

    Full Notion workspace + sequences — email delivery within 24 hours via Square.

    Buy on Square — $47 →

    Related Operations & Systems

    Companion Systems: Complete Restoration Operations Kit ($97) · 4 Claude Skills ($29) · Tygart Media Shop.

    Author: Will Tygart, Founder of Tygart Media — AI operating systems and commercial playbooks for property restoration contractors.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.

    END_

  • Google Ads Analysis

    Google Ads Analysis

    Google Ads Analysis

    $250

    Delivered by email after checkout.

    Buy Now →

    Secure checkout via Square — all major cards accepted

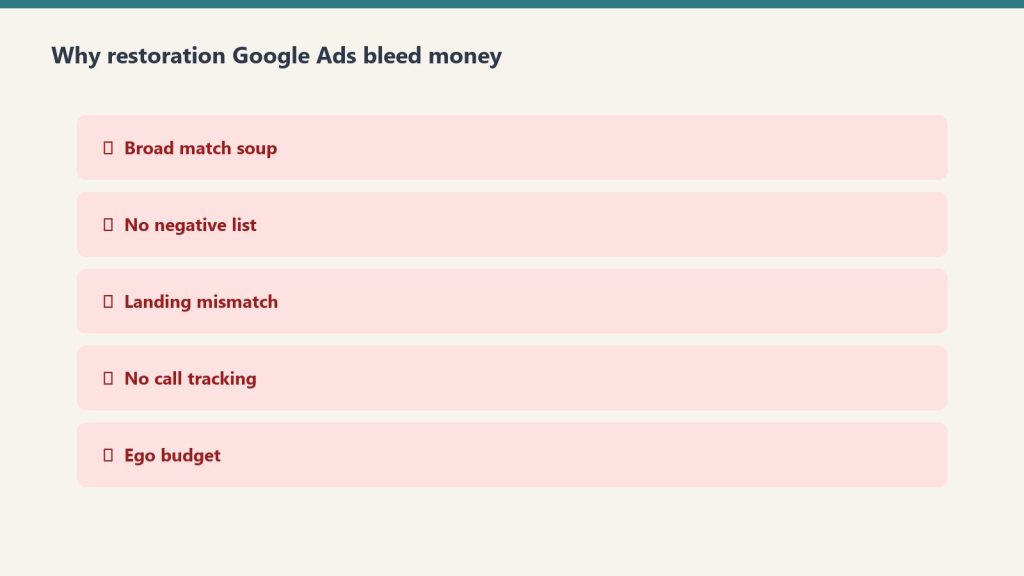
    You can copy this method and do it yourself. Split campaigns by service. Load negatives before you spend another week. Match every landing page to its ad group. Compute fully-loaded cost per acquired job, not just CPC. Buy Now is the packaged analysis delivered by email after checkout, so you are not assembling the read from a blank spreadsheet.

    Restoration PPC is an engineering problem, not a set-it-and-forget-it expense. Emergency water-damage keywords have been reported as high as $250 per click in competitive metros. Average emergency restoration keywords more commonly land in the $40-$150 range depending on geography. At those CPCs, structure and landing pages decide whether the phone pays you or you subsidize the auction.

    How to run the analysis

    1. Open the account. List every campaign, ad group, and the landing URL each ad actually hits.
    2. Mark the single-campaign trap if you see it: one campaign, one ad group, water / mold / fire / flood keywords fighting each other, every ad pointing at the homepage.
    3. Pull Search Terms for the last 30-60 days. Tag wasted queries (jobs, DIY, training, equipment rental).
    4. Check bidding against conversion volume. Under 30 conversions a month in a campaign is a different tool than 30+.
    5. Open each landing page on a phone. Does the H1 match the ad? Is click-to-call above the fold?
    6. Write fully-loaded cost per acquired job by channel: spend ÷ booked jobs from that channel, then layer close rate. CPC from the dashboard is not that number.

    1. Kill the single-campaign trap

    Red checklist of five reasons restoration Google Ads waste budget
    Kill the single-campaign trap first.

    The most common setup: one campaign, one ad group, a mix of water damage, mold removal, fire restoration, and flood cleanup keywords all fighting each other. Every click gets the same generic ad. Every ad points to the homepage.

    Quality Score is built on expected click-through rate, ad relevance, and landing page experience. When you stuff water damage and fire restoration into the same ad group, ad relevance tanks for both. A Quality Score of 9 can outrank a competitor bidding twice as much at a 5. Poor structure can inflate CPC by 30% or more while delivering fewer qualified leads.

    Split by service. Each ad group 10-20 tightly related keywords. Every keyword in the group has to fit the same ad and the same landing page. If they do not, split them.

    • Campaign 1. Emergency water damage. Ad groups for emergency water extraction, burst pipe, basement flooding, sewage backup. Separate ad copy. Landing page that opens with emergency water damage, not the homepage.
    • Campaign 2. Fire and smoke restoration. Fire damage, smoke damage, soot removal. Different call to action. Fire jobs are longer projects, a different sales conversation.
    • Campaign 3. Mold remediation. Mold testing, black mold removal, mold inspection. Often a separate buyer with a different timeline.

    Give Performance Max its own campaign and its own budget if you run it. PMax black-box reporting will otherwise hide whether Search is working.

    2. Negative keywords: the bill you are not seeing

    Three ranked panels: intent near need, catch overflow, compound trust
    Negatives are the bill you are not seeing.

    Most restoration PPC campaigns have a weak or nonexistent negative list. Every day without one, you pay for job seekers (“water damage restoration jobs near me”), DIY researchers (“how to do water damage restoration yourself”), students looking for training, and equipment renters who are not calling you for service.

    Campaigns that actively manage negatives see a reported 10-20% lower wasted spend and a 5-15% conversion-rate lift. On a $10,000/month budget, that is $1,000-$2,000 a month currently going to irrelevant clicks.

    Build a seed negative list before the campaign launches. Pull Search Terms weekly for the first 60 days. Add exact-match negatives first. Only go broader if the data supports it. Over-blocking with broad-match negatives will starve volume you actually want.

    3. Bidding: stop fighting the machine

    A large share of Google Ads spend now runs through Smart Bidding (Target CPA, Target ROAS, Maximize Conversions). Advertisers using AI bidding have been reported at roughly 22% lower cost per conversion versus manual CPC on average. For restoration, the right tool depends on data:

    • Under 30 conversions per month in a campaign. Maximize Clicks with a CPC cap while you accumulate signal. Smart Bidding starved of conversions produces garbage.
    • 30+ conversions per month. Move to Target CPA. Set the target from actual job margins, not aspirational ones. If a water job averages $12,000 and you close 25% of qualified leads, a $300 CPL target can still profit. If you close under 15%, fix sales before you fix bidding.
    • Large campaigns with consistent job data. Target ROAS becomes viable only if revenue tracking is actually wired into Google Ads. Most restoration accounts do not have that configured.

    The problem is rarely the channel. It is losing track of where the leads went after the phone call.

    4. The landing page has to match the ad

    Three cards for LSA, search ads, and SEO/AI authority channels
    Landing page must match the ad — or you paid for confusion.

    If the ad says “Emergency Basement Flooding, 24/7 Response” and the landing page is the homepage with a hero of a happy family and a form below the fold, you are burning the click you just paid for.

    A restoration PPC landing page needs: the emergency service name in the H1 above the fold; a click-to-call number prominent on mobile; a response-time claim only if you can back it up; one short form (name, phone, zip, issue); proof (reviews, IICRC, insurance logos).

    Do not send PPC traffic to the homepage. Do not build one landing page for all services. Match the ad to the page, the page to the ad group, the ad group to the keyword cluster. That chain is where Quality Score lives.

    5. Channel mix and the number that actually matters

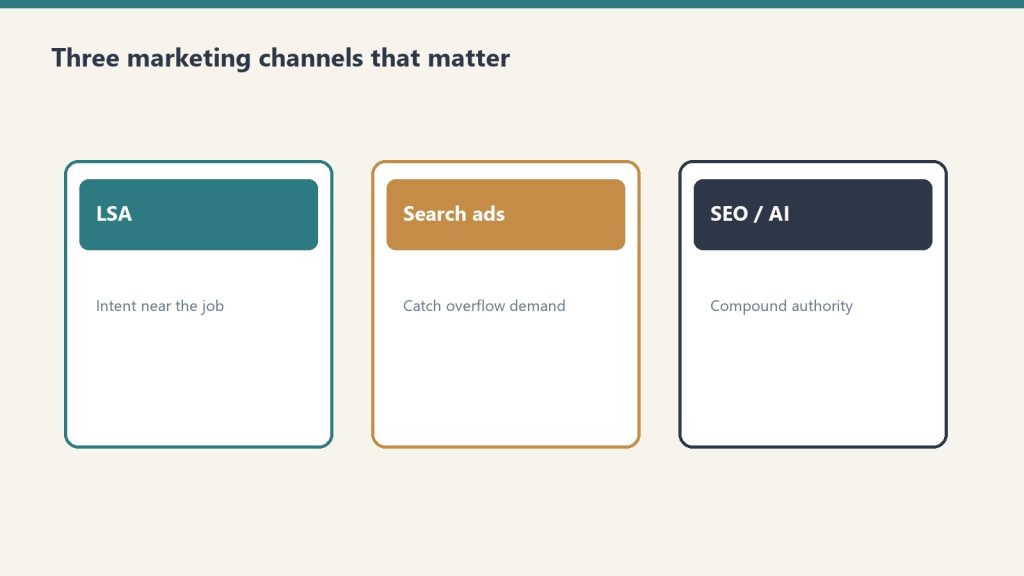
    Three channels do the heavy lifting. LSA (pay per qualified call; reported restoration CPL roughly $80-$200 depending on the write-up) is the highest-ROI paid lever for most residential operators, with a catch: Google ended credits for “job type not serviced” and “geo not serviced” in 2025, so junk leads come out of your pocket. Search Ads (reported CPL $150-$400+ structured, $400-$700+ not) buy control LSA does not have: commercial work, specific service lines, overflow when LSA hits a daily cap, brand defense. If you are spending more than $5,000 a month on Search and you do not have LSAs set up, that is the first fix. SEO is the compounding asset. Restoration SEO in competitive metros typically takes 12-18 months. Treat reported ranges as ranges, not promises.

    Cost-per-lead is the number every vendor reports. The number that matters is fully-loaded cost per acquired job: CPL divided by channel-specific close rate, plus CSR labor on the call, plus processing, minus franchise or TPA fee if it applies. Most shops have CPL from the platform and revenue from the job software, and the two systems have never talked. Fix that before you change a single bid.

    Budget ballparks (Search only, reported)

    • Mid-size market (pop. 200K-500K): $3,000-$6,000/month to generate 15-30 leads
    • Major metro (pop. 1M+): $8,000-$15,000/month to maintain consistent visibility
    • Specific suburb or tight service area: $1,500-$3,000/month if geo is tight and Quality Score is managed

    These are Search figures. They are ballparks from the published method, not a quote for your market.

    Done when

    You can show separate service campaigns, a negative list with at least 50 entries, a dedicated landing page for each major service, and a fully-loaded acquired-job cost by channel. If your current agency cannot show those four, the account is not being run as an engineering problem.

    If you want the packaged analysis

    You can run the six steps from the outline above on your own login. Buy Now is the analysis delivered by email after checkout. Same Square button at the top of this page.

    Marketing and operational read only. Not a media-buy, legal, or insurance engagement. Reported CPC and CPL ranges move by metro and by month. Use your own numbers.

    Related on Tygart Media: restoration Google Ads · marketing stack.

  • How Buyers Price a Restoration Company: 2026 Deal Killers

    How Buyers Price a Restoration Company: 2026 Deal Killers

    Most restoration buyers in 2026 are paying for the wrong things. They look at top-line revenue, the truck count, the trailing-twelve EBITDA — and miss the structural details that decide whether the company they just bought is a $4M business or a slow-motion writedown. Private equity has deployed over $6 billion across 50-plus platforms since 2018, and the buyers who keep winning at these multiples are the ones with a checklist that goes deeper than the broker’s pitch deck.

    Here is what the disciplined buyers — strategic acquirers, PE platforms, and operator-buyers — actually look at when they price a restoration company in 2026, and the five line items that quietly kill more deals than anything in the financials.

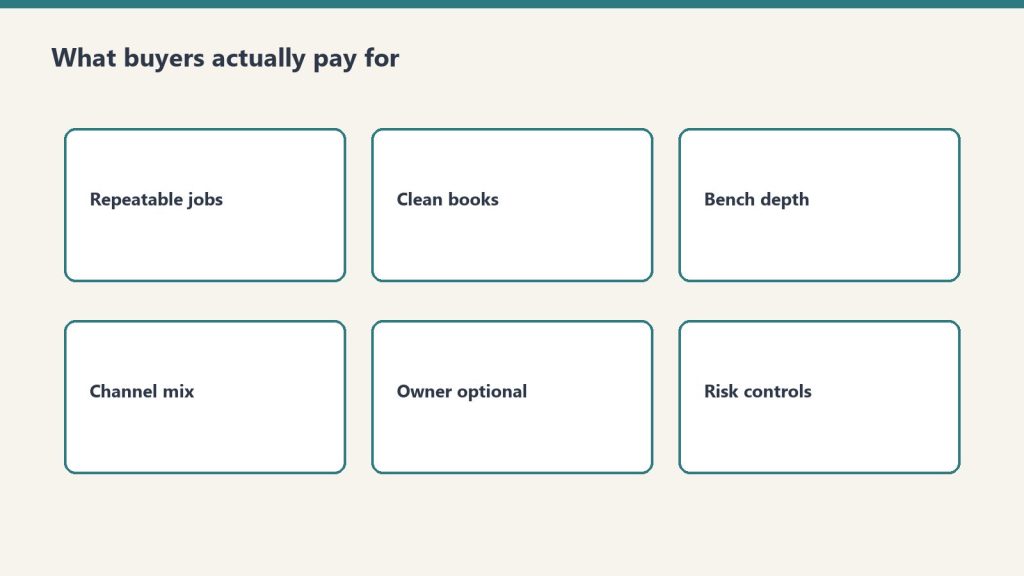
    What buyers are actually paying for in 2026

    Six cards: repeatable jobs, clean books, bench depth, channel mix, owner optional, risk controls
    What buyers pay for in 2026 — transferability over heroics.

    Median sale prices in restoration have risen to roughly $2.2M. Shops under $2M in revenue tend to clear at 2.5x to 3.0x SDE. The $2M to $5M EBITDA band — what the industry calls the PE feeder zone — trades at 4x to 6x EBITDA. Platforms above $10M EBITDA push 6x to 8x with strategic buyers willing to stretch further for the right geography or carrier panel. The spread between bottom and top of that range is not random. It is a function of five drivers that a thorough buyer will price line by line.

    Carrier preferred-vendor status is the first thing on every diligence sheet. A company on the preferred panel of two or more Tier 1 carriers — State Farm, Allstate, USAA, Liberty Mutual — gets a multiple premium because that revenue is durable, repeatable, and very hard for a new entrant to replicate. A company that depends on one TPA program for half its work gets discounted because that revenue is one phone call away from disappearing.

    Revenue mix matters almost as much. Mitigation-heavy companies — fast-turn water and emergency services — carry better margins and more predictable cash conversion than companies leaning on large-loss reconstruction. Reconstruction-heavy shops can still trade well, but buyers will model lower margins and longer working-capital cycles, which compresses the multiple.

    Management depth below the founder is the third lever. If the owner is the estimator, the rainmaker, and the operations lead, the buyer will assume a 12 to 24 month earnout structure and discount the price accordingly. A general manager, an estimating lead, and a production manager who are staying through transition can add an entire turn of EBITDA to the offer.

    CAT exposure is the fourth. Companies with more than 20-25% of revenue tied to catastrophic events get valued on a normalized basis — buyers strip the spike years out of the average. If you bought a restoration company on a peak hurricane year’s numbers, you overpaid. Sophisticated buyers know this and adjust before they sign the LOI.

    The fifth is books that survive a quality-of-earnings review. In about 85% of deals, the QoE adjusts down from the seller’s claimed EBITDA, and the average haircut runs 10 to 15%. Companies that have already run a sell-side QoE and addressed the easy adjustments hold their price better than companies that hand a buyer a QuickBooks export and a confident shrug.

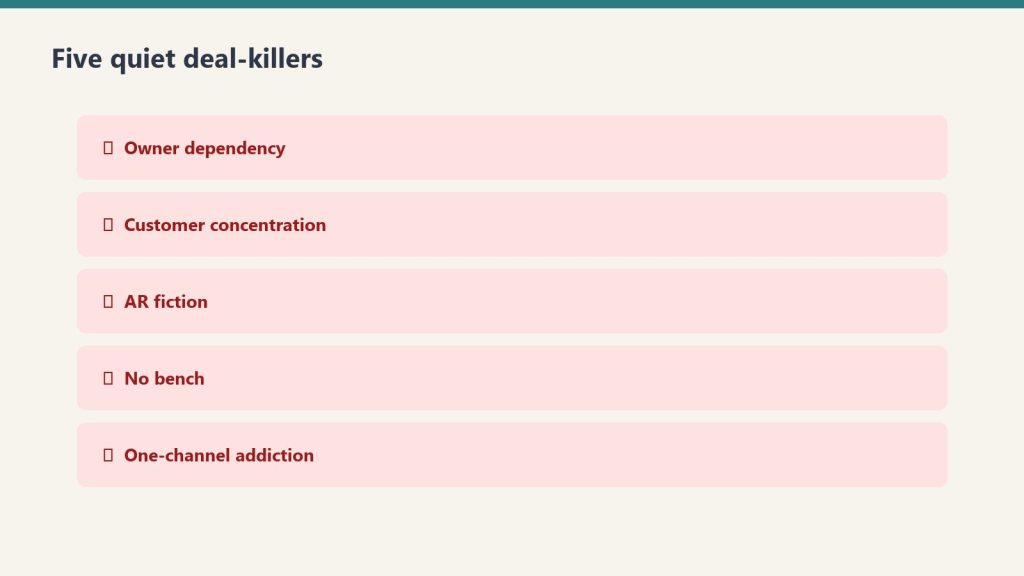
    The five quiet deal-killers

    Red checklist of five quiet deal killers for restoration M&A
    Five quiet deal-killers — fix before the LOI.

    Most deals do not die on price. They die in the back half of due diligence, when something surfaces that the seller either did not disclose or did not realize mattered. These are the five issues that show up most often, and what a disciplined buyer does about each one.

    1. Customer or carrier concentration over 20%. If a single carrier, TPA program, or property manager drives more than a fifth of revenue, the company has a single point of failure. Buyers either re-price the deal, structure a larger earnout tied to retention, or walk. The honest fix on the seller side is to diversify the book 18 months before going to market, but most do not have that luxury once they have decided to sell.

    2. Licensing and certification gaps. Restoration is a regulated trade in most states. Buyers verify IICRC firm certification, individual technician WRT and ASD credentials, AMRT for mold work, state contractor licenses, and any specialty endorsements required locally. A lapsed firm certification or an expired mold license is not always a deal-killer, but it is always a price renegotiation and sometimes a regulatory exposure that gets baked into the purchase agreement as an indemnity.

    3. Aged accounts receivable. Restoration AR ages slowly because insurance carriers and TPAs pay slowly. Buyers will look at the receivables aging report and discount anything over 90 days, sometimes severely. If a meaningful portion of the company’s "earnings" is actually trapped in 180+ day AR that nobody is going to collect, the working capital adjustment at close will swallow a real chunk of the purchase price.

    4. Founder dependency in estimating and sales. This is the single most common reason restoration deals collapse or restructure into heavy earnouts. If the founder writes 60% of the estimates and personally manages the top carrier relationships, buyers know the business does not transfer. The seller who builds a real estimating department and pushes carrier relationships down to a sales lead two years before sale will capture meaningfully more value.

    5. Compliance and labor exposure. 1099 versus W-2 misclassification, prevailing wage issues on commercial jobs, OSHA history, and EMR trends all surface in diligence. Buyers will hire an HR specialist on any deal above a few million in revenue, and a clean compliance picture is worth 0.25x to 0.5x of EBITDA on its own.

    What a buyer should actually run before the LOI

    Six cards covering job margin, cycle time, AR days, utilization, CAC, close rate
    Run unit economics before the LOI — not after.

    The minimum diligence package on a serious restoration acquisition includes: a quality-of-earnings review by a firm that has seen at least a dozen restoration deals, an independent verification of carrier preferred-vendor status and any TPA contracts, a customer concentration analysis at the carrier and account level, an AR aging review by a buyer-side accountant, an IICRC and state licensing audit, and a sit-down with the operations and estimating leads with the founder out of the room. That last item is the most underused and the most predictive.

    Buyers who skip any of these line items end up renegotiating after close or eating a writedown a year in. Buyers who run all of them tend to pay slightly less and own businesses that transfer cleanly.

    Bottom line

    The 2026 restoration market is the best buyer’s window of the next five years, but only for buyers with discipline. The capital is there, the seller pipeline is there as the founder generation exits, and the platform playbook has been proven by HighGround, American Restoration, and a half-dozen others. The companies worth buying at top-of-range multiples are the ones with diversified carrier mix, real management depth, and books that survive a serious QoE. Everything else is a turnaround dressed up as an acquisition — and turnarounds in restoration take 18 to 36 months to fix and often cost more than the purchase premium ever saved. Pay for what transfers. Walk from what does not.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.

    Frequently asked questions

    What multiple do restoration companies sell for in 2026?

    Sub-$2M revenue shops typically trade at 2.5x to 3.0x SDE. Companies in the $2M to $5M EBITDA range — the PE feeder zone — clear 4x to 6x EBITDA. Platforms above $10M EBITDA reach 6x to 8x, with strategic premiums pushing higher in the right geography or carrier panel.

    What kills restoration acquisition deals most often?

    Customer or carrier concentration above 20%, founder dependency in estimating and sales, aged accounts receivable that does not collect, licensing or IICRC certification gaps, and labor compliance exposure — in roughly that order of frequency.

    How long should a buyer-side diligence process take?

    For a sub-$5M revenue restoration acquisition, plan on 60 to 90 days from signed LOI to close. Quality of earnings runs three to five weeks, legal and licensing diligence runs parallel, and customer/carrier verification typically lands in the final two weeks before close.

    Is buying a restoration franchise better than buying an independent?

    Franchises like SERVPRO or ServiceMaster Restore deliver brand, training, and national-account access at the cost of royalties and territorial restrictions. Independents give you full margin upside and the freedom to build proprietary carrier relationships, but require self-built systems and certifications. For first-time operators, the franchise reduces execution risk. For experienced operators, an independent acquisition tends to compound faster.

  • Xactimate Sketch Workflows: Encircle vs DocuSketch Costs

    Xactimate Sketch Workflows: Encircle vs DocuSketch Costs

    Most restoration owners I know underestimate what their sketch workflow actually costs them. Not the per-claim app fee — the labor hour buried in every job where a tech spends 90 minutes measuring a flooded basement with a laser distance meter, then another 45 minutes back at the office rebuilding it in Xactimate Sketch. At a loaded labor rate of $45 an hour and ten water jobs a week, those 135 minutes per job add up to roughly $52,000 a year in tech hours tied up in measurement and sketch rebuild — a meaningful chunk of which is not directly billable. The sketch is the foundation of every line item Xactimate calculates — walls, floors, ceilings, missing wall openings, ceiling height multipliers — and if it’s wrong, the entire estimate inherits the error. So the question is not whether to invest in a sketch workflow. It’s which one.

    Why the sketch is the most expensive five minutes in restoration

    Four steps: phone capture, sketch in Xactimate, review, supplement
    Sketch is expensive when you redo it — capture once.

    Xactimate utilizes the sketch to drive line item quantities — square footage of drywall, linear feet of base trim, square footage of ceiling, paint surfaces, area for antimicrobial application. Get the ceiling height wrong by six inches in a 200-square-foot room and you’ve quietly undercut your paint and wall labor by roughly 100 surface square feet. Forget to draw a missing wall between a kitchen and a dining room and Xactimate treats them as two separate sealed rooms — doubling perimeter trim, ignoring shared dry-out airflow, and producing a scope that any seasoned adjuster will flag and ask you to redo.

    Common sketch errors compound: rushing through measurements without verification, failing to account for wall thickness, overlooking irregular features like soffits or knee walls, and using incorrect roof pitch on exterior sketches. The result is either lost revenue on your end (you underbilled) or a denial cycle on the carrier side (the adjuster sends it back and your cash conversion stretches). Either way, the sketch is where the money leaks out.

    The three sketch workflows actually used in the field

    Gloved hands using a pin-type moisture meter on wet drywall during inspection
    Three field workflows — pick one and train it.

    Despite a dozen marketing pitches, restoration contractors use one of three approaches. Each has a real cost and a real time profile.

    1. Manual Xactimate Sketch (laser distance meter + on-screen drawing)

    The default. A tech walks the loss with a Bosch or Leica laser, writes measurements on a clipboard or phone notes app, then either sketches on-site in the X1 mobile app or rebuilds it at the office. Cost is whatever you already pay for Xactimate (Professional runs around $185/month per user on subscription pricing as of early 2026, per Verisk’s published rates — verify on your own contract because Verisk negotiates).

    Realistic time for a competent tech on a 1,500-square-foot residential water loss: 45–60 minutes on-site for measurements and photos, plus 30–45 minutes back at the office to build the sketch in Xactimate. Call it 90 minutes total. The advantage: no extra software cost, full control. The disadvantage: every minute of that 90 is a minute a tech is not on another job, and your sketch accuracy depends entirely on how disciplined your tech is with a laser.

    2. Encircle Floor Plan

    Encircle’s floor plan product converts a smartphone video walkthrough into a Xactimate-ready ESX or FML import. Their published per-claim pricing is around $25 per claim as of 2026, with subscription bundles available — confirm current pricing with Encircle directly, as restoration software vendors revise tiered pricing frequently. Encircle’s marketing claims floor plans are delivered in under 6 hours, but in practice most users report same-day to next-morning turnaround.

    The actual workflow advantage is not the speed of delivery — it’s that your tech leaves the loss with a video, not a sketch. On-site time drops to roughly 15–25 minutes. The office labor for sketch rebuild drops to near zero because Encircle delivers an importable file. If you’re running 40 claims a month and trimming 60 minutes per claim, that’s 40 hours of tech labor recaptured — roughly $1,800 a month in labor against $1,000 in Encircle fees. The math works above about 25–30 claims a month.

    3. DocuSketch

    DocuSketch uses a 360 camera kit instead of a smartphone video. The contractor captures spherical photos at each room, uploads, and DocuSketch returns an ESX file. Per their public materials, ESX and FML files are typically delivered 1 to 3 days after capture. Per-claim cost at scale runs around $70 when amortizing the Express plan ($1,095/month), the $795 camera kit, and overnight delivery fees against 20 projects a month — based on DocuSketch’s published comparison materials.

    DocuSketch’s appeal is the 360 photo documentation that comes with the sketch — useful for supplement defense and for adjuster file packages. The disadvantage versus Encircle: slower turnaround (days, not hours), higher per-claim cost, and a camera kit your techs have to actually carry and use. For high-volume shops doing large losses and commercial work where 360 documentation has independent value, DocuSketch can earn its keep. For a typical residential water mitigation shop, the price-per-claim is hard to justify against Encircle.

    The bottom line for restoration owners

    White restoration work van with ladder rack parked at a suburban jobsite curb
    Bottom line: faster accurate sketches protect margin.

    If you’re under 20 claims a month, manual sketching is fine. Buy your techs better lasers and train them on Xactimate Sketch keyboard shortcuts (CTRL+click and drag to pull new rooms from existing ones is the single highest-leverage shortcut Xactimate ships). Sending a tech to one of the regular Xactimate fundamentals classes pays for itself the first month — it’s the cheapest sketch optimization you can buy.

    If you’re between 20 and 60 claims a month and most of your volume is residential water, Encircle Floor Plan is the obvious move. The labor recapture pays for the subscription several times over, and your techs spend less time at the office rebuilding sketches and more time at the next loss. Make sure your techs actually shoot the video correctly — Encircle’s output quality depends on input quality.

    If you’re north of 60 claims a month, running commercial losses, or losing supplements because your documentation packages are thin, evaluate DocuSketch alongside Encircle. The 360 documentation is a real defensible asset when you’re supplementing six months after the original scope. Some shops run both — Encircle for residential water mitigation, DocuSketch for commercial and large-loss reconstruction.

    One workflow truth nobody likes to say out loud: the sketch tool only matters if your techs use it consistently. The shops that get the most out of Encircle or DocuSketch are the ones where the office manager refuses to accept a claim file without a video or 360 capture. Without that enforcement, you’re paying for software and still rebuilding sketches at the office because half your techs forgot to use it.

    Pick the workflow that fits your claim volume, then enforce it. The sketch is the foundation of every line item Xactimate calculates. It’s worth more attention than most owners give it.

    Related on Tygart Media: Starlink on a water job · S500 in the van · local SEO for restoration.

  • Commercial Specialty Loss: Insurance & Adjuster Dynamics

    Commercial Specialty Loss: Insurance & Adjuster Dynamics

    Updated Oct 31, 2026 — added the free specialty loss room map, room map pack, and insurance decoder bot book downloads to this guide.

    Direct answer: On a commercial specialty loss, the room is bigger than most restoration operators assume. The carrier has a staff, independent, or TPA adjuster running the file. The facility has a risk manager and often a broker. A public adjuster may be retained. A large loss brings in large-loss specialists, accountants for business interruption, and technical experts for specialty valuations. The restoration company that understands this room — who decides what, what documentation each party needs, and how specialty work fits into commercial policy structures — is treated as a participant in the claim rather than as a vendor waiting for scope approval. That shift in positioning is worth more revenue over time than any rate-sheet negotiation.

    The previous seven articles in this cluster have built the operational case for the specialty wedge: what the categories are, what the ESA looks like, what accounts respond to it, and how the specialist bench gets built. This article covers the financial and contractual mechanics that run in parallel — the insurance and adjusting side of every commercial specialty loss. Miss this side and the operational work does not convert into paid work.

    Commercial insurance is structurally different from residential insurance in ways that matter for every decision a restoration company makes on a specialty event. Policies are written on different forms. Deductibles are higher and sometimes paid out-of-pocket by the insured before the carrier engages. Business interruption is a live coverage that runs on its own clock. Scope of loss is adjudicated against policy language and often against pre-existing replacement-cost-value schedules. Specialty items frequently carry their own endorsements, riders, or scheduled coverages separate from the main property form. And the adjusting function is distributed across multiple roles rather than concentrated in one person. A restoration company that enters this environment with residential habits — “I’ll do the work and the carrier will pay the invoice” — spends two years getting punished by the system before learning how it actually works.

    The rest of this article is the operator-level map.

    Instant Operational Downloads

    Master the Commercial Claims Room or Feed Your AI Assistant

    Field-ready tools built on ISO commercial property forms, adjuster authority hierarchies, coinsurance math, and business interruption clocks.

    Quick Reference FREE

    Who’s In The Room: Specialty Loss Quick Map

    2-page field card: The guide’s 8-seat stakeholder breakdown (Insured, Broker, Staff/IA/TPA Adjuster, PA, GA, Consultants, Examiner, Counsel) condensed onto a rapid reference map.

    Download Free PDF

    Direct download • No email gate

    Working Pack $7

    Commercial Specialty Loss: Room Map Pack

    Printable/fillable working instruments: Tabletop map ($50K vs $5M), Adjuster-type authority sheet, Policy structure audit (ISO vs Manuscript), Coinsurance checker, and BI clock sheet.

    Get Room Map Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots $17

    Insurance Decoder: Book for Bots

    Feed to ChatGPT or Claude: 5 AI-run routines (Room Mapper, Adjuster Decoder, Coverage Audit, Settlement-Math Checker, BI Clock Alignment) with embedded output router.

    Get Bot Book ($17) →

    Software made of words • Instant delivery

    Who is actually in the room

    Clipboard and tablet on a kitchen counter during an insurance adjuster walkthrough after water loss
    Who is in the room on a commercial specialty loss.

    The parties at the table on a commercial specialty loss, in roughly the order they appear:

    The insured. The facility itself — through its facilities director, risk manager, operations leader, or corporate real estate director. This is the party whose property is damaged and whose coverage is at stake. On significant losses, the insured is represented by its risk function, which is materially different from the facilities function. Risk manages the policy relationship and the financial outcome; facilities manages operations. Both matter. They do not always agree with each other.

    The broker. Most commercial policies are placed through a broker — Aon, Marsh, Willis, Lockton, Gallagher, Alliant, Brown & Brown, Hub, and many regional and specialty brokers. The broker is the insured’s advocate with the carrier, is paid by the carrier out of premium, and usually has a long relationship with the insured’s risk function. On large losses, the broker’s claims advocacy team is actively involved in negotiating scope and settlement.

    The carrier’s adjuster. This is the person running the claim on the carrier’s side. Three variants exist. A staff adjuster is a carrier employee; common on small to mid-size losses and on carriers that use in-house handling. An independent adjuster (IA) is a contractor deployed by the carrier through firms like Alacrity Solutions, Pilot Catastrophe, Eberl, Worley, Crawford, or Sedgwick; common on large losses, CAT events, and geographically dispersed exposure. A TPA (third-party administrator) adjuster is the primary handler for carriers that outsource claims administration and for self-insured and captive-insured programs; common on commercial programs, public entities, and corporate risk-management structures. The restoration company’s ability to work productively with the adjuster depends significantly on which type is assigned, because their authority, their time horizon, and their reporting structure differ.

    The public adjuster. When retained by the insured (usually on significant losses where the insured wants its own adjusting advocate), the public adjuster — PA — is paid by the insured, typically on a percentage of settlement, and represents the insured’s interests in scope development and negotiation. PAs are regulated state by state; several states prohibit them on commercial losses, others allow them with restrictions. On losses where a PA is involved, the dynamic shifts — negotiations take longer, documentation is scrutinized harder, and the restoration company needs to provide tighter scope evidence.

    The large-loss adjuster or general adjuster. On losses above a dollar threshold — typically $250,000 to $1 million depending on the carrier — the file escalates to a large-loss or general adjuster. These are senior, experienced adjusters with broader authority and usually a more commercial orientation. Some are staff, some are GA-track independents. When a large-loss adjuster takes the file, the restoration company’s interaction becomes more substantive and more documentation-driven.

    Specialty consultants. On large or technically complex losses, the carrier commonly retains technical experts: a forensic engineer for cause-and-origin, a certified industrial hygienist for environmental and IAQ work, a forensic accountant for business interruption, a specialty valuer for art or antique items, a cost consultant for high-dollar reconstruction, and sometimes a building consultant for envelope or structural issues. These specialists produce deliverables that drive scope decisions.

    The TPA’s file examiner. When a TPA is administering claims, an examiner manages the file behind the scenes — reviewing adjuster work product, authorizing payments, and enforcing the program’s service-level standards. The examiner is rarely on site and is often invisible to the restoration company, but their decisions affect payment timing and scope approval.

    Coverage counsel. On disputed losses or large losses where coverage issues surface, the carrier will engage coverage counsel. The insured may engage its own. At this point the claim has become a negotiation in a legal frame. The restoration company’s documentation becomes evidence.

    The restoration company does not work with all of these parties on every loss. On a $50,000 commercial water event, it may be only the insured and an independent adjuster. On a $5,000,000 hospital fire with specialty equipment and business interruption, it may be all of them. The operator’s task is to map who is at the table on each event and communicate with each party at the right level of technical and contractual detail.

    Commercial policy structures and what they cover on specialty losses

    Commercial property policies are not written on a single form. Four families of forms matter for the restoration company’s day-to-day work.

    ISO Commercial Property program. The Insurance Services Office writes standardized forms — Building and Personal Property Coverage Form (CP 00 10), Causes of Loss forms (Basic, Broad, Special), and various endorsements. Most mid-market commercial policies are written on ISO forms or close variants. Specialty items get coverage through the Building and Personal Property form unless they are scheduled out into separate endorsements.

    Manuscript forms and package policies. Large commercial accounts and specialized verticals (healthcare, universities, financial services, real estate portfolios, manufacturing) often have carrier-specific or manuscript forms that modify or replace ISO language. AIG, Zurich, Chubb, FM Global, Travelers, Liberty Mutual, and The Hartford all publish proprietary commercial forms. These forms generally provide broader coverage than ISO Special Form but with more complex conditions and sublimits.

    Scheduled property. Certain high-value items are scheduled individually rather than covered under the general property form. Fine art (blanket or itemized scheduled), rare books, specialty medical equipment, trading-floor technology, and specific pieces of machinery are often scheduled with specific values, specific covered perils, and sometimes specific named conservators or repair vendors.

    Inland marine. Specialty coverages that sit outside the building are often written as inland marine — fine art (scheduled or blanket), medical equipment on lease (Motor Truck Cargo for mobile medical imaging, for example), contractor’s equipment, and data-processing equipment at multiple locations.

    The implication for restoration companies: the answer to “is this covered?” on a specialty item is rarely obvious from the general property policy. The insured’s broker or risk manager will know how a specific item is scheduled, endorsed, or covered. The restoration company should ask — politely, early — about coverage structure on high-value items before assuming the work will be paid under the mainline property form.

    Three coverage concepts that appear on most commercial losses:

    Replacement cost value vs. actual cash value. RCV settles at the cost to replace with like kind and quality. ACV settles at RCV less depreciation. Most commercial forms pay RCV if the insured repairs or replaces, but pay ACV initially with a holdback until repair is proven. For restoration services, this distinction matters because the invoice structure has to support the RCV conversion — which means documented scope, documented completion, and invoicing that tracks to the carrier’s RCV recovery process.

    Coinsurance. Commercial property forms usually contain a coinsurance clause requiring the insured to carry coverage at a specified percentage (commonly 80%, 90%, or 100%) of the insured value. Under-insurance triggers a penalty that reduces the settlement. This is not usually a restoration company problem, but it affects the insured’s willingness to accept an aggressive scope because a scope that triggers a coinsurance penalty is a scope that costs the insured money. Restoration companies that scope aggressively without understanding the policy structure damage the insured’s financial outcome and the relationship.

    Sublimits. Commercial policies routinely have sublimits for specific categories: contents in rooms subject to flood, fine art, electronic data, business records, and items in specific storage configurations. A loss that exceeds a sublimit is paid only up to the sublimit, regardless of the full loss value. Restoration companies working on specialty losses should know the sublimits in play so they can scope and communicate realistically.

    Business interruption and the restoration clock

    Commercial office lobby entrance after a pipe burst with caution cones and wet runners
    Business interruption and the restoration clock.

    Business interruption coverage is the financial engine behind commercial restoration urgency and is the single coverage most often misunderstood by operators.

    BI pays the insured for lost income during the period of restoration — the time from the loss event until the property can, with reasonable speed, be repaired or replaced and operations restored. The clock runs during restoration. The longer the restoration, the more BI the insured collects — which sometimes makes people assume that slower restoration is better for the insured. That is backwards in most cases. BI is capped by period-of-indemnity limits (often 12 months), by policy sublimits on dependent property and civil authority extensions, by extra expense limits that may be exhausted mid-loss, and by the insured’s actual lost margin — which includes lost customers who do not return when operations resume.

    The correct operational posture is that the insured and the restoration company share an interest in restoring quickly. BI is not an excuse to slow down; it is the mechanism that funds the urgency. Specialty work is directly BI-sensitive — a hospital whose imaging is down is losing procedure revenue and triggering BI; a financial firm whose records are off-site in freeze-drying is limited in its operations; a cultural institution whose galleries are closed is generating BI on lost admissions and event revenue. The specialty wedge reduces BI duration, which is often the strongest ROI argument for the ESA in the first place.

    Three BI-adjacent coverages that restoration companies should know:

    Extra expense. Pays the insured for costs incurred to continue operations or accelerate restoration beyond normal costs. A temporary imaging suite rental, expedited manufacturer recertification, priority freeze-drying at premium rates, emergency specialist activation — these are often extra expense items. Getting them pre-approved by the adjuster at the time of incurrence is cleaner than arguing about them at invoice.

    Civil authority coverage. Pays BI when a civil authority prohibits access to the insured property because of damage at an adjacent property. Relevant on CAT events and in urban environments.

    Dependent property / contingent business interruption. Pays BI when a dependent property (a supplier, a customer, a key logistics node) suffers a loss that impacts the insured. Emerging in commercial coverage and usually outside the scope of restoration work, but sometimes in play when the specialty loss affects a contract manufacturer, logistics hub, or shared facility.

    The scope-of-loss process

    The scope of loss is the formal document that defines what the restoration work is. It is the central artifact of any commercial claim, and the quality of the scope drives the quality of the payment.

    The standard scope-of-loss process on commercial work:

    Initial inspection. Carrier adjuster, insured or PA, and restoration company walk the loss. Observations recorded by all parties. On large losses, specialists from the specialty bench may be present on the walk-through.

    Mitigation scope. The emergency services work — water extraction, dry-out, containment, specialty stabilization — is scoped separately and billed early, often before the full scope of loss is developed. This is priced against the ESA rate schedule or against Xactimate mitigation line items.

    Full scope of loss. After the property is stable, the carrier’s adjuster, often with specialists (engineering, IAQ, specialty valuers), develops a full scope covering structural repair, contents, specialty items, and business interruption. This scope is the basis for settlement of the claim and the basis for the restoration company’s reconstruction and specialty work pricing.

    Scope approval and work authorization. The insured and the carrier agree on scope. The restoration company receives authorization for each phase of work.

    Execution and documentation. Work is performed. Documentation is produced on a rolling basis — daily notes, photographs, moisture logs for drying, chain-of-custody logs for document work, biomed sign-offs for medical equipment, conservator reports for art. This documentation is the evidence that the work was performed to scope.

    Invoice and payment. Invoices submitted against approved scope with supporting documentation. Payment processed through the adjuster or directly through the carrier’s claims system. Some carriers pay through an insured-controlled account (insured pays the contractor, carrier reimburses the insured); some pay direct to the contractor (common when there is an AOB or direct-bill arrangement); some pay jointly (to insured and contractor).

    Xactimate is the dominant estimating platform. Approximately 80% of property claims are estimated in Xactimate. Restoration companies working commercial need Xactimate proficiency — either an in-house estimator with Level 1 or Level 2 certification or a relationship with a third-party estimating service. Scope developed in Xactimate using current carrier price lists settles faster than scope developed in other formats. Scope that deviates from Xactimate norms needs specific justification — unique conditions, specialty pricing not in the standard price list, or negotiated departures from default pricing.

    Specialty scope is where Xactimate runs out of detail. Freeze-drying a pallet of documents, ultrasonic cleaning of a rack of servers, biomed recertification of a CT scanner, conservation of a damaged oil painting — none of these live cleanly inside Xactimate line items. The restoration company, in partnership with the specialist, has to develop specialty scope separately using the specialist’s own pricing methodology (per cubic foot, per square foot of material, per piece, per instrument) and then incorporate that into the overall scope. The adjuster may or may not accept the specialty scope at face value. On significant losses, the carrier will often retain a specialty consultant to validate the specialty scope and pricing. Being ready for that validation — with chain-of-custody documentation, technical evidence of the recovery need, and industry-standard pricing references — is what converts specialty scope into paid work.

    Documentation discipline on specialty losses

    Labeled contents pack-out boxes and bins stacked in a living room for inventory
    Documentation discipline on specialty losses.

    The documentation produced during a specialty loss is both operational evidence and financial instrument. On commercial losses, the quality of documentation drives settlement speed, settlement value, and audit defensibility. Five documentation streams that belong on every specialty loss:

    Loss environment documentation. Photographs at arrival, photographs during stabilization, photographs at completion. Moisture mapping. Environmental readings (temperature, relative humidity, particulate, air pressure). Atmospheric condition logs for the first 72 hours (the window in which most specialty loss decisions are made). Any readings beyond normal environmental parameters — toxic vapor, asbestos disturbance, lead dust — with documentation of the protective measures deployed.

    Chain of custody. Every physical item removed from the site, every location it travels to, every person who handles it, every environmental condition it is stored in, every return event. For documents, this is boxes and pallets tracked by RFID or barcode. For electronics, this is serialized equipment with date/time/handler logs. For art, this is object-level tracking including photographic documentation of condition at each transfer. For medical equipment, this is serial-number-tracked items with biomed sign-off at each transfer. Chain-of-custody is the single most important specialty documentation stream and the one most often underbuilt.

    Scope evidence. Line-item justification for every scope item. Xactimate documentation for standard items. Specialty-specific pricing documentation with industry references where possible (freeze-drying per cubic foot reference ranges, ultrasonic cleaning per square inch, conservation per hour with AIC conservator rate guidance, biomed recertification per OEM schedule).

    Specialist technical reports. Each specialty subcontractor produces a technical report on their portion of the work: conservator’s treatment report, biomed’s recertification documentation, electronics restoration’s testing and clearance reports, document recovery’s drying logs and post-processing condition reports. These reports are the basis for specialty scope, specialty pricing, and specialty settlement.

    Compliance documentation. For regulated environments — HIPAA, GxP, FERPA, PCI — documentation of the compliance posture maintained during the loss. BAA references, data-handling logs, secure-destruction certificates, access logs, training records for on-site personnel. This documentation is what defends against a regulatory finding layered on top of the loss.

    The documentation produced during a specialty loss should be assembled into a final loss package at closure — a single comprehensive deliverable that the carrier, the insured, and the broker each receive. This final package is the artifact that closes the claim cleanly and that serves as evidence if any part of the claim is later disputed or audited.

    Commercial Claims Discipline

    Equip Your Team with Tabletop Maps or Deploy AI Claims Analytics

    When a commercial specialty loss hits, amateur documentation and misunderstanding the adjuster hierarchy will result in slashed scopes and delayed payments. Shift from commodity vendor to indispensable claims participant with field-tested working worksheets or our AI prompt decoder.

    📋

    What’s In The Toolkit:

    • Who’s-In-The-Room Tabletop: $50K vs $5M matrix.
    • Adjuster Authority Sheet: Staff / IA / TPA profiles.
    • Policy Form Audit: ISO CP 00 10 vs Manuscript.
    • Ask-Early Script: Broker & Risk Manager intake.
    • Coinsurance Calculator: 80/90/100% penalty check.
    • BI Clock & Extra Expense: Indemnity cap tool.
    • AI Decoder Routines ($17): 5 AI workflows & router.
    Secure 1-Click Square Checkout

    How the restoration company earns a seat at the table

    Commercial restoration companies are rarely invited to participate in scope discussions. They are usually asked to submit estimates and then wait for approvals. The specialty wedge changes this dynamic for two reasons. First, the specialty work requires technical input the adjuster does not have — the carrier needs the specialist’s voice to develop the scope. Second, the ESA relationship pre-establishes the restoration company as a known, trusted, pre-vetted party with an existing relationship with the insured.

    The combination of technical specialty and pre-loss relationship is what converts the restoration company from vendor to participant. Concrete behaviors that accelerate that conversion:

    Bring specialty expertise to the scope meeting. The first walk-through after a specialty loss should include the specialty subcontractor, not just the restoration company’s general lead. A walk-through where the specialist points out what the carrier’s generalist adjuster will miss — environmental degradation windows, irreversible damage thresholds, specialty-specific salvage considerations — is a walk-through where the restoration company demonstrates value beyond commodity labor.

    Build credibility with the adjusting community. The commercial adjusting world is relationship-dense. Independent adjusters working for multiple carriers carry reputations from job to job. TPA file examiners talk to each other. Large-loss adjusters know the handful of restoration companies that operate at a high-specialty level. Sustained, consistent, high-documentation work on a handful of losses produces a reputation that compounds — and eventually a reputation that the adjusting community refers work to rather than one that chases work.

    Communicate in the adjusters’ language. The restoration company that can speak about scope in terms of ISO forms, sublimits, coinsurance, RCV versus ACV, extra expense allowance, dependent property coverage, and specific Xactimate line items is taken seriously by the adjuster. The restoration company that speaks only in operational terms is relegated to operational status. The language is learnable — a few IICRC-adjacent certifications (NICA or RIA’s classes on insurance, Xactimate certification, a few hours reading ISO CP form language) is enough to change the conversation.

    Avoid adversarial postures on ordinary disputes. The scope process produces routine disagreements over items, pricing, and methods. These are negotiations, not fights. Restoration companies that treat every disagreement as a fight train the adjuster to minimize future interaction; restoration companies that negotiate professionally with evidence build relationships that pay forward. Reserve adversarial postures for the few cases where a carrier is genuinely behaving inappropriately, and handle those through coverage counsel and the broker rather than directly.

    Invest in the broker relationship. Brokers are often the most overlooked party in the room. A strong broker-side relationship means the restoration company is referenced when the broker is advising a client after a loss, and sometimes means the broker recommends the restoration company for the ESA conversation in the first place. Time with brokers, participation in broker-hosted client events, and involvement in broker-sponsored risk-management content are all high-ROI activities for restoration companies targeting commercial accounts.

    When the relationship should route through a public adjuster

    On significant commercial losses, the insured may retain a public adjuster. This changes the dynamic. PAs are paid by the insured as a percentage of settlement, which means they are motivated to maximize scope and valuation. That motivation aligns with the restoration company’s interest in being paid fully for the work but can create tension with the carrier’s cost-control interest.

    Operating effectively when a PA is on the file:

    Recognize the PA as the insured’s advocate. The PA will push hard on scope, pricing, and documentation. The restoration company’s job is to be ready — scope that was developed casually will be scrutinized, pricing that was loose will be challenged, documentation that was informal will be demanded in finished form. The PA is not the enemy; they are the scope’s quality control.

    Keep the carrier relationship professional. The carrier will respond to a PA’s scope pressure in kind. If the restoration company appears aligned with the PA against the carrier, the carrier’s cooperation evaporates. The restoration company’s proper posture is neutral service provider with documented scope and professional communication on both sides.

    Watch for PA fees coming out of the restoration company’s invoice. In a few states and a few PA contracts, the PA’s percentage fee is calculated against the total settlement including mitigation and restoration payments to the contractor. This can effectively reduce the contractor’s payment. Restoration companies should understand how the PA fee structure flows and negotiate for pre-deducted arrangements when possible.

    Regulatory and coverage exposure the restoration company carries

    A specialty commercial loss creates a handful of exposures the restoration company needs to manage regardless of how the insurance pays out.

    HIPAA and data regulations. Discussed in earlier cluster articles. A healthcare-loss mishandling triggers direct regulatory exposure under HIPAA. A financial-services-loss mishandling may trigger GLBA or state financial-privacy law. A student-records mishandling triggers FERPA. These regulatory exposures are not paid by the insured’s insurance and are the restoration company’s own problem.

    Contractual indemnification to the facility. Discussed in the ESA article. Indemnity provisions in the ESA govern how losses caused by the restoration company’s performance route back. Insurance is the funding mechanism; the contract is the liability structure. Restoration companies operating at the commercial specialty level need adequate general liability and professional liability coverage to support the indemnity they have agreed to.

    Subcontractor liability. Specialty work performed by subcontractors flows back to the restoration company through the master subcontractor agreements. Insurance coordination between the restoration company and the specialist is what funds this liability. The additional-insured posture and the certificate-of-insurance cross-referencing from the earlier bench and ESA articles is the operational answer.

    State-specific licensing and consumer-protection exposure. Many states regulate insurance-restoration contracts, including post-loss AOBs, fixed-price contracts, work authorizations, and cooling-off periods. Restoration companies operating multi-state need to know their exposure in each state they work. A contract that is enforceable in one state may be void in another.

    Xactimate scrutiny and audit. Repeated carrier work produces audit patterns over time. Consistent overbilling patterns, scope padding, or line-item inflation are tracked across the industry and eventually produce carrier pushback, reduced approvals, or removal from preferred-vendor lists. The operational discipline of scoping honestly, pricing against Xactimate as the default, and negotiating deviations transparently is what preserves long-term commercial work.

    How this article completes the specialty cluster

    The pillar and seven cluster articles before this one have covered, in sequence: why specialty is a commercial door-opener, what the four specialty categories are, what the ESA needs to contain, what accounts to pursue, how to build the specialist bench. This article covers the financial mechanics that make the system sustainable.

    The specialty restoration wedge as a commercial strategy depends on operating competently in each of these domains simultaneously. A restoration company with a great bench but weak ESA structure loses to the contract. A restoration company with a great ESA but thin bench loses to the event. A restoration company with both but no understanding of the adjusting dynamics gets paid slowly, paid incompletely, or paid after disputes that erode the relationship. The system works when every layer works.

    The operator’s takeaway: the specialty wedge is not a single product. It is an integrated capability that includes operational specialty execution, contract infrastructure, account-portfolio focus, bench relationships, and claims-handling competence. Any restoration company building toward this model should treat the eight articles in this cluster as a checklist. A company that has made progress on six or seven of the eight dimensions is a company that will convert commercial specialty opportunities. A company that has only focused on one or two dimensions will keep losing to companies that have covered all eight.

    Related on Tygart Media: commercial accounts to target · emergency services agreement · specialty bench vetting.

    Choose Your Commercial Specialty Claims Rung

    Select the resource tier that matches your company’s commercial operational scale:

    Free Field Summary

    Specialty Loss Quick Map

    2-page quick card covering the 8 seats in the room, $50K vs $5M comparison, and the 5 documentation streams.

    FREE direct download
    • The 8 seats in the room (who hires, pays & decides)
    • $50K water vs $5M complex fire stakeholder comparison
    • Adjuster language translation: ISO, RCV, BI, Sublimits
    • The 5 mandatory specialty documentation streams
    • Final Loss Package deliverable architecture
    Download Free PDF

    Instant download • No email gate

    Static Working Pack

    Who’s In The Room Map Pack

    Printable and fillable forms: tabletop maps, adjuster authority matrix, policy audit worksheets, and BI clock tools.

    $7 one-time payment
    • Who’s-In-The-Room Tabletop Map with payor & threshold logs
    • Adjuster-Type Quick-Reference: Staff vs IA firms vs TPA vs GA
    • Commercial Policy Structure Worksheet: ISO vs Manuscript
    • Polite Ask-Early Script for Broker & Risk Manager intake
    • RCV vs ACV holdback checklist & Coinsurance Penalty checker
    • Business Interruption Clock Sheet & Extra Expense tool
    • 5 Documentation Streams & Final Loss Package checklist
    Get Room Map Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Software Made of Words

    Insurance Decoder: Book for Bots

    Feed directly to ChatGPT or Claude to map claim stakeholders, audit carrier policies, calculate settlement math, and align BI clocks.

    $17 one-time payment
    • Room Mapper Interview (/ROSTER): Scale & seat diagnostic
    • Adjuster Decoder (/ADJUSTER): IA/TPA authority blueprint
    • Coverage Audit (/POLICY): Form gap & inland marine check
    • Settlement-Math Checker (/MATH): Coinsurance penalty math
    • BI Clock Alignment (/CLOCK): Extra Expense ROI optimizer
    • Final Loss Package Compiler (/PACKAGE): Delivery manifest
    • Embedded Output Router: Autonomous LLM dispatch engine
    Get Bot Book ($17) →

    Instant checkout • Square verified

    Frequently asked questions

    How is a commercial claim different from a residential claim from the restoration company’s perspective? Three practical differences. First, the adjusting is distributed across more parties (broker, adjuster, PA, specialists, large-loss adjuster, coverage counsel) rather than concentrated in one adjuster. Second, the policy is more complex — specialty items are often scheduled or sub-limited, business interruption is a live coverage, and the language matters more. Third, the documentation bar is higher. Commercial claims are audited more aggressively, disputed more technically, and settled more formally than residential claims.

    What is the most common reason specialty scope is denied or reduced? Insufficient technical documentation. A specialist saying “this needs freeze-drying” is not enough. The scope needs to document why the material is unstable, what the degradation window is, what the alternative (replacement or reconstruction) would cost, and why the specialty work is the economically correct choice. Adjusters reduce scope they cannot defend to their file examiners. Technical documentation is what makes scope defensible.

    How do we avoid being paid slowly on commercial work? Invoice promptly with complete documentation. Incomplete invoices delay payment more than anything else. Invoice against approved scope, reference approvals in the invoice, attach supporting documentation in standard format, and follow up on the adjuster’s payment-processing timeline. Restoration companies that become easy to pay get paid faster.

    When should we recommend the insured retain a public adjuster? Rarely. Recommending a PA creates apparent alignment with the insured against the carrier and damages the restoration company’s neutrality. If the insured asks whether to retain a PA, the appropriate answer is that this is a decision for the insured, the broker, and the insured’s counsel, and that the restoration company works effectively with or without a PA on the file. State law also matters — in some states, a restoration company recommending a PA can itself be a licensing violation.

    How much Xactimate competence do we actually need? Enough to produce a defensible mitigation estimate in Xactimate format, enough to read and discuss an adjuster’s Xactimate scope, and enough to identify line items that are mis-applied or missing. Level 1 certification meets this bar. Anything beyond is useful but optional. Specialty work does not live inside Xactimate, but everything around the specialty work does, so Xactimate fluency is the table-stakes communication layer.

    What role does the broker play and how do we engage them? The broker is the insured’s advocate with the carrier and is often involved in large-loss scope discussions. Engaging the broker means building relationships before the loss — meeting commercial brokers in the region, participating in broker-hosted events, and being referenceable as a restoration partner. Brokers who have worked with the restoration company on prior losses are far more likely to recommend the company in future situations.

    What happens when a specialty item exceeds its scheduled coverage? The item is paid up to the scheduled limit, and the excess is the insured’s uninsured loss. Restoration companies should understand this before developing scope on scheduled items, because scoping aggressively on an item that is already at its coverage limit pushes the insured into out-of-pocket territory. A scope discussion that acknowledges the coverage ceiling and negotiates trade-offs is more useful than a scope that exceeds the ceiling and creates a conflict.

    How do large-loss adjusters differ from regular adjusters, and how should we behave differently? Large-loss adjusters have broader authority, more technical experience, and less tolerance for informal handling. Behaviors that work on a $30,000 loss with a junior adjuster will not work on a $3,000,000 loss with a GA. The restoration company’s posture on a large loss should be more documented, more formal, more specialist-integrated, and more patient. Large-loss claims are settled on their documentation; shortcuts cost real money.

    What is the single most important piece of advice for a restoration company starting to work commercial specialty losses? Invest in understanding commercial insurance before you chase commercial accounts. A few weeks of study — ISO property forms, Xactimate certification, the basics of commercial underwriting, familiarity with the major carrier claims programs — is worth more than a year of trying to figure it out one loss at a time. The language and the structure of commercial insurance is learnable. Once learned, it converts specialty capability from a sales pitch into a durable commercial practice.

    What closes this cluster? This cluster closes the specialty restoration wedge as a complete commercial strategy: the categories, the contract, the accounts, the bench, and now the financial mechanics. The remaining work is execution — picking two verticals, building the bench, signing the first two or three ESAs, running the first few real events, and iterating. The framework is in place. The specialty wedge is durable because it serves a real need that commercial facilities feel and that general restoration positioning does not answer. Build it, run it, and protect it.

  • Specialty Restoration Bench: How to Vet Subcontractors

    Specialty Restoration Bench: How to Vet Subcontractors

    Direct answer: The specialty restoration bench is the infrastructure that makes the commercial wedge real. It consists of pre-qualified, pre-contracted, and operationally rehearsed specialist partners across four categories — document and records recovery, electronics and data equipment, fine art and collections conservation, and medical and laboratory equipment — plus the internal systems to activate them quickly, manage them during a loss, and bill them accurately afterward. Without the bench, the managed-service pitch is a brochure. With the bench, the restoration company is the one facility relationship and the coordinator of a national-grade specialist network.

    The previous six articles in this cluster have built toward a specific operational claim: that a restoration company becomes a commercial door-opener not because it does specialty work internally, but because it manages a curated specialist bench that covers the four categories most facilities can neither service in-house nor source independently on the night of a loss. That claim is only credible if the bench actually exists, actually performs, and actually stays activated. This article walks through how to build it.

    The bench is not a vendor list. A vendor list is something a facilities director keeps on a bulletin board. The bench is a working infrastructure: pre-qualified companies with current insurance, active mutual-aid or subcontract agreements, defined activation protocols, negotiated rate frameworks, completed compliance documentation, and actual relationships between named operational leaders on both sides. Building that infrastructure takes ninety to one hundred eighty days for the first three or four specialists and becomes a continuous operation after that. The rest of this article breaks down what that work looks like, specialty by specialty.

    The four specialty categories and why the bench maps to them

    Every major commercial loss touches two or three of these categories. A hospital water event touches medical equipment, documents, and often electronics. A law firm fire touches documents, electronics, and sometimes art. A museum pipe break touches fine art, documents, and occasionally electronics. A corporate office flood touches electronics, documents, and sometimes art. The bench covers all four because the loss does not respect neat categories, and because the facility wants one call — not four — when the event hits.

    The four categories, from most common to least common in a typical commercial restoration company’s loss mix:

    Document and records recovery. The most frequent specialty activation. Paper is in every commercial environment, water is the most common loss type, and document recovery is the most operationally mature of the four categories.

    Electronics and data equipment recovery. The second most frequent, and trending up. Every commercial facility has technology infrastructure, and losses that used to be “dry out the room and replace the laptops” increasingly involve mission-critical systems, server rooms, and specialty equipment where replacement is slower and costlier than restoration.

    Medical and laboratory equipment recovery. High-value, high-regulation, high-margin. Occurs in healthcare, research, biotech, pharmaceutical, veterinary, and education verticals. Lower volume than documents or electronics but often the highest per-event value in the bench.

    Fine art and collections conservation. The lowest volume of the four but the highest reputational impact per event. Occurs across cultural institutions, corporate collections, law firms, financial services, private clients with high-value holdings in commercial facilities, and real estate portfolios with significant public art.

    The bench does not need to be equally deep in all four. For a restoration company serving a region heavy in healthcare, the medical bench should be the deepest. For a region heavy in law firms and financial services, the document bench takes priority. Match the bench depth to the account portfolio and to the geographic realities of the specialists you can realistically activate inside a useful response window.

    Document recovery bench

    Labeled contents pack-out boxes and bins stacked in a living room for inventory
    Document recovery bench — pack-out discipline starts here.

    The document specialist landscape is the most mature and easiest to populate. Three companies dominate at the national level, and each operates differently enough that most sophisticated restoration companies keep at least two of them in the bench plus a regional or specialized option.

    BELFOR Property Restoration maintains specialized document laboratories across North America with vacuum freeze-dry chambers, molecular sieves, desiccant drying capability, refrigerated transport trucks, and stationary and mobile processing capacity. Their document and media recovery division services losses ranging from single boxes to institutional-scale events. Useful for: larger events, insurance-carrier-preferred work, national footprint coverage, and situations where the carrier specifically wants BELFOR involvement.

    Polygon operates document recovery services globally with more than twenty-five years of experience. Polygon uses vacuum freeze-drying with negative-pressure chambers, desiccant dehumidification, and specialized chambers for maps, blueprints, books, and bound materials. Their claimed turnaround efficiency is 20-30% faster on back-processing time. Useful for: libraries, museums, government agencies, medical offices, any record-dense facility, and large-volume drying projects.

    Document Reprocessors pioneered the Thermaline® vacuum freeze-drying process and specializes in the highest-value and most technically challenging document recovery work — rare books, archival materials, historical documents, art on paper, maps, blueprints, and any material where dimensional stability matters. Their Thermaline process restrains books from warping and distorting during the drying cycle. Useful for: cultural institutions, law firms with original documents, archives, rare collection materials, and any situation where the materials are irreplaceable.

    Regional and specialized options worth investigating for the bench: local archival-services firms for small-volume high-value work, paper conservators (AIC credentialed) for fine-art-adjacent paper materials, commercial records-management companies with emergency-response capability for bulk business records.

    Qualification criteria for the document bench. Current certificate of insurance at appropriate limits. Named contact at the operational level (not just sales). Documented freeze-drying capacity (cubic feet or pallet equivalents) available within twenty-four hours of activation. Transportation capability for wet materials — refrigerated trucks, freezer trailers, or rapid-mobilization partners. Chain-of-custody documentation systems. HIPAA BAA for medical-adjacent work. Confidentiality posture appropriate for law-firm work. Geographic coverage matching the restoration company’s account footprint.

    Electronics restoration bench

    The electronics specialist landscape is also mature but more fragmented. Four companies are commonly referenced at the national level, and the choice among them often comes down to which carrier or facility the work is being done for.

    BELFOR’s electronics restoration division provides large-scale technical electronics and machinery restoration including drying, decontamination, corrosion control, data recovery coordination, and manufacturer-recertification pathways. Their capability scales from single-server losses to full data center events.

    Prism Specialties restores electronics, appliances, and commercial machinery across a franchise network covering most of the United States. Prism also operates a data recovery division for damaged storage media and has specialty capability across textiles, electronics, art, and documents — some restoration companies work with Prism across multiple specialty categories.

    CRDN (Certified Restoration Drycleaning Network) operates as a franchised network specializing in textiles, electronics, and contents restoration. Their electronics capability includes functional testing, restoration, and data recovery services, and their commercial division handles losses from retail through medical and industrial facilities.

    Cotton GDS provides electronics restoration and data recovery as part of a broader commercial disaster services platform. Cotton is particularly relevant for restoration companies that work in Texas, the Gulf, and parts of the South where Cotton’s regional density is highest.

    Regional and specialized options: data-center-specific cleaning firms (several operate specifically inside the mission-critical space), printed circuit board cleaning specialists, manufacturer-authorized service organizations for specific equipment categories, and certified data recovery laboratories (SalvationDATA, DriveSavers, Ontrack, Kroll) for media-level data recovery when the storage medium itself has failed.

    Qualification criteria for the electronics bench. Ultrasonic cleaning capacity with deionized water and pH-neutral detergent protocols. Desiccant dehumidification capacity appropriate for the facility sizes you serve. HEPA filtration at negative-air rates appropriate for commercial server rooms. Manufacturer-certified or manufacturer-authorized status for major OEMs you encounter (Dell, HP, Cisco, IBM, depending on the accounts). SOC 2 Type II or equivalent security posture for data-touching work. NAID AAA certification or equivalent for secure data destruction. Insurance limits appropriate to the equipment values handled. Geographic response capability within the activation window.

    Fine art and collections conservation bench

    The art and collections bench works differently from the other three categories. For art, the bench is not dominated by large restoration companies — it is a network of individual AIC-credentialed conservators, regional conservation laboratories, and specialty firms that service specific media. The restoration company’s role is not to vet an equivalent of BELFOR; it is to build relationships with the conservator network and to have the AIC-CERT 24-hour emergency assistance hotline (202-661-8068) wired into the activation protocol.

    The structural layers of the art bench, from top of stack down:

    AIC-CERT — the American Institute for Conservation Collections Emergency Response Team — is the first call for any cultural-institution event and for any significant non-institutional art loss. AIC-CERT provides 24-hour phone advice and can dispatch a team for on-site damage assessment and salvage organization. For institutional accounts (museums, libraries, archives), AIC-CERT is often already in the facility’s emergency plan, and the restoration company’s job is to coordinate rather than duplicate.

    FAIC National Heritage Responders is AIC’s national volunteer network of conservators available for response to major disasters affecting cultural collections. Activation is usually through AIC-CERT and is most relevant for large-scale or CAT-event responses affecting multiple institutions.

    Regional conservation laboratories — the largest in the country include B.R. Howard & Associates, Fine Arts Conservancy, the American Conservation Consortium, Stella Conservation, the Campbell Center’s affiliated conservators, and a number of museum-affiliated conservation facilities that take private work. Most restoration companies cultivate relationships with two or three regional labs covering their geographic area rather than trying to maintain national coverage.

    Independent AIC-credentialed conservators — several hundred operate privately across the United States, organized by specialty (paintings, paper, objects, photographs, books and paper, textiles, architectural, digital media, time-based media). The AIC member directory is searchable by specialty and region and is the starting point for building local relationships.

    Specialty firms for specific media — these include picture-framing specialists for works on paper and photographs, sculpture mount-makers, specialty crating firms (Atelier 4, ICEFAT members) for transport of high-value pieces, and climate-controlled art-storage firms for interim holding.

    Qualification criteria for the art bench. AIC professional membership for the lead conservator on any engagement. AIC-CERT participation for institutional work where available. Current insurance including fine art coverage or specialty endorsement. Demonstrated experience with the specific media involved (painting conservators cannot responsibly service sculpture; paper conservators cannot responsibly service architectural works). Relationship with a credible AIC-CERT-connected escalation pathway for events beyond the conservator’s own capacity. Demonstrated discipline about conservator-led decision-making — a conservator who treats the restoration company as a subordinate is a better partner than one who lets the restoration company dictate conservation methodology.

    Medical and laboratory equipment bench

    The medical equipment bench is the most complex and the most regulated of the four. It requires a different kind of infrastructure because the specialty is not really “restoration” — it is clinical engineering and biomedical equipment service, which is a different industry with different credentialing, different supply chains, and different operational rhythms.

    The bench for medical equipment has three layers: restoration-industry specialists with healthcare capability, OEM and independent biomedical service organizations, and the in-hospital biomed department itself as a co-responder.

    Restoration-industry healthcare specialists. BELFOR Healthcare operates a dedicated healthcare division with ICRA-credentialed crews and the insurance, compliance, and operational posture required for hospital work. Cotton GDS, First Onsite, ATI Restoration, and other national and large-regional players have developed healthcare practice areas with similar capability. For major hospital events, these are often the prime-level partners because no regional restoration company can independently meet the full healthcare qualification bar.

    OEM and independent biomedical service organizations. These are the companies that actually service and recertify medical equipment — the biomed side of the bench. Agiliti provides nationwide biomedical technicians, ISO 13485:2016 certified clinical engineering services, and OEM parts access across general biomedical equipment, specialty beds, and diagnostic imaging systems. BMES specializes in patient monitor and telemetry repair with OEM-specific test stations and depot repair services. GE HealthCare Service, Philips Healthcare, and Siemens Healthineers each operate service networks that can recertify their own branded equipment after restoration — and for major imaging equipment, the manufacturer recertification is usually non-negotiable. Elite Biomedical Solutions and similar companies support biomed departments with OEM-level replacement parts and repairs.

    In-hospital biomed as co-responder. The hospital’s own biomedical engineering department is the first technical decision-maker for any equipment-involving event. The restoration company’s activation protocol must engage biomed from hour one, not after the containment is built. The bench relationship that matters most for medical equipment is often the relationship with the hospital’s biomed director, not an external specialist — because biomed controls which equipment can be restored, which must be recertified, which must be replaced, and who performs each decision.

    Qualification criteria for the medical bench. ISO 13485 for clinical engineering capability where applicable. ICRA 2.0 credentialing for any on-site work in patient-care areas. HIPAA BAA execution. Current insurance at healthcare-appropriate limits (often five million general liability plus specialty coverages). OEM certifications or authorized-service relationships for equipment categories common in the accounts served. GxP documentation capability for research and pharmaceutical accounts. State-specific medical-device-handling compliance where relevant.

    Building the bench: the vetting process

    Restoration technicians training in a shop bay with equipment demo and whiteboard
    Vetting process: credentials, capacity, night-of activation.

    Populating the bench is not a procurement exercise. It is a relationship exercise run through a procurement framework. The process that works, in order:

    Identify candidates. Use industry association directories (RIA, AIC, ISSA, AHA supply chain resources), referrals from peer restoration companies, carrier-preferred-vendor intelligence, and direct outreach to specialists who appear on major losses in your market. A bench of five to eight specialists across the four categories is enough for most regional restoration companies. More than that is hard to maintain actively.

    Request qualification documentation. Standard package: current W-9, current certificates of insurance with adequate limits and appropriate endorsements, corporate organizational information, state licenses where applicable, industry certifications, safety record and OSHA 300 logs, equipment and capacity documentation, and reference list from recent engagements.

    Conduct operational interview. This is the step most restoration companies skip and should not. A sixty-minute conversation with the specialist’s operational leader (not sales) to walk through activation protocol, response time commitments, capacity under CAT conditions, chain-of-custody documentation, invoicing workflow, insurance interaction norms, and any hard constraints the specialist will not flex on. The operational interview is what separates a specialist you will trust on a 2 a.m. call from one you will hesitate to activate.

    Execute a master subcontractor agreement. One-time legal work that covers the relationship framework: scope, insurance, indemnification, confidentiality, payment terms, dispute resolution, and the same eight-provision structure that governs the ESAs with facilities. The master agreement is the contractual spine; individual engagements are executed through work authorizations that reference the master.

    Dry-run activation. Before the bench goes live in real emergencies, run at least one tabletop exercise with each specialist. A simulated 2 a.m. event — water in a document-dense commercial facility, or a fire suppression discharge in a data center, or a water event in a hospital imaging suite — with full activation protocol, call tree execution, and after-action review. Tabletops reveal protocol gaps that no amount of document review will surface.

    Ongoing maintenance. Quarterly check-in calls with each specialist’s operational leader, annual insurance renewal tracking, annual master agreement review, and continuous capture of after-action lessons from real events. Bench relationships decay when unexercised — a specialist you have not activated in twelve months should get a maintenance call to confirm they are still a real option before the next event.

    Activation protocol: how the bench works on the night of a loss

    Restoration SOP clipboard with checklist, moisture meter, and gloves on a jobsite table
    Activation protocol — the bench only matters if it works at 2 a.m.

    The activation protocol is the operational sequence that converts bench infrastructure into specialist hands on site. It has to be fast, documented, and rehearsed. The sequence that works for most commercial losses:

    Hour zero to hour one. Restoration company dispatched, on-site lead identifies loss category and probable specialty involvement. Facility contacts notified, authority-to-commence obtained. Initial scoping call back to operations center.

    Hour one to hour three. Specialty categories confirmed through walk-through. For each category, operations center activates the primary specialist from the bench. Activation call includes loss location, nature and volume of affected materials, initial access logistics, facility-specific requirements (ICRA, HIPAA, clearance, credentialing), and specialist ETA commitment. Secondary specialist notified if primary cannot meet the window.

    Hour three to hour twelve. Primary specialist on site. Restoration company provides on-site coordinator who interfaces between facility operations, the specialist, the adjuster (if on scene), and any in-facility technical leadership (biomed for hospital, IT for data center, conservator for cultural institution). Scope documentation begins on both sides — restoration company documents general conditions, specialist documents specialty-specific findings.

    Hour twelve through day three. Specialty stabilization progresses. Restoration company continues to own environmental conditions, containment, site security, and documentation coordination. Specialist owns technical execution within their category. Dual documentation streams are reconciled daily and distributed to the adjuster.

    Day three onward. Scope of loss is fully developed. Specialty work moves from emergency stabilization into extended restoration (off-site freeze-drying, vendor-recertification of medical equipment, conservation treatment of art, forensic data recovery of electronics). Restoration company continues as relationship owner and coordinator while specialist executes. Invoicing and documentation flow on the schedule negotiated in the master subcontractor agreement.

    Pricing and financial structure

    Three models exist for how specialty pricing flows through the bench. All are defensible; the right choice depends on the restoration company’s risk posture and the facility’s and carrier’s preferences.

    Pass-through with coordination fee. Specialist bills the restoration company at their standard commercial rate. Restoration company bills the carrier or facility at the same rate with a coordination fee layered on (typically 10-15% depending on the specialty and the carrier’s norms). Simplest model, clearest audit trail, and the one most carriers default to.

    Direct-bill to carrier. Specialist bills the carrier directly on a separate invoice. Restoration company receives a coordination fee billed to the carrier or facility separately. Common for fine art conservation (where conservator fees almost always route direct) and for major manufacturer recertification work (where OEM invoices come direct).

    Markup and prime-bill. Specialist bills the restoration company at a negotiated subcontractor rate (below list). Restoration company bills the carrier at the list rate and keeps the margin. This model is legal and common but carriers increasingly scrutinize it, and transparent audit-trail documentation is essential to avoid dispute.

    Some specialists will only operate in certain of these models. Major OEMs typically only direct-bill. AIC conservators often direct-bill to carriers. Document recovery firms are flexible. Electronics restoration firms are often willing to operate in any of the three. Negotiate the model into the master subcontractor agreement so it is pre-decided rather than argued after each event.

    What the bench does for the restoration company’s own business

    Beyond the obvious operational function, the bench provides three strategic advantages that justify the investment.

    Commercial credibility. A restoration company with a documented bench across four specialties answers the commercial facility’s first and hardest question — “can you handle the specialty work this facility actually has?” — with yes. Without the bench, the answer is a soft yes that evaporates on inspection. With the bench, the answer is a hard yes backed by named partners and documented capability.

    Margin protection. Specialty work is margin-rich for the coordinating restoration company because the coordination fee is high-margin revenue against low direct cost. A restoration company that only does general mitigation runs at commodity margins; a restoration company that coordinates specialty recovery adds high-margin revenue on top of the general mitigation revenue without adding proportional operational risk.

    Pipeline insulation. Commercial accounts that sign ESAs with specialty coverage provide revenue floor even in years where general restoration demand is soft. When a restoration company’s revenue is weighted toward emergency services agreements with sophisticated commercial facilities rather than toward residential claims cycling through carrier preferred-vendor programs, the business becomes more predictable and less exposed to carrier-program volatility.

    What the bench does not do

    The bench does not make a restoration company a specialty firm. The restoration company coordinates; it does not perform. Trying to blur that line — claiming in-house specialty capability that is actually subcontracted, or displacing specialist decision-making during an event — will damage both the specialist relationships and the facility relationships. Discipline about the coordinator role is what makes the bench work.

    The bench does not eliminate risk. Poorly coordinated specialty work can still fail. A freeze-drying run that damages bindings, an ultrasonic cleaning protocol that damages circuit boards, an ICRA barrier breach during hospital work, or a conservation decision made without conservator approval — any of these can happen even with a vetted bench, and the restoration company as coordinator carries real exposure. The master subcontractor agreements, the insurance structure, and the operational protocol all exist to manage this exposure but cannot eliminate it.

    The bench does not replace the facility relationship. Specialists are subcontractors and partners, but the relationship with the commercial facility is owned by the restoration company. A facility that starts calling the specialist directly is a facility that no longer needs the restoration company. The operational discipline is to keep the facility relationship centered on the restoration company as coordinator, even when the specialist is doing the visible technical work.

    Related on Tygart Media: commercial specialty loss · accounts to target · commercial restoration sales.

    Frequently asked questions

    Do we need exclusive subcontractor agreements with our specialists, or non-exclusive? Non-exclusive, in nearly every case. The leading specialists work with dozens of restoration companies and will not accept exclusivity. Forcing the question early damages the relationship. The operational posture that works is non-exclusive agreements with clear commitment to priority response for pre-loss-covered accounts, backed by enough business volume that you are a priority customer for the specialist even without contractual exclusivity.

    How do we handle a specialist who becomes difficult or underperforms? The same way any subcontractor performance issue is handled: document, confront directly, give an improvement opportunity if the relationship is worth preserving, and terminate per the master agreement if not. The bench is a living roster, not a permanent commitment. Annual re-qualification is appropriate.

    What if the facility has its own preferred specialist we do not have on the bench? This happens regularly, especially with cultural institutions (who have pre-existing conservator relationships), hospitals (who have pre-existing biomed relationships), and data centers (who have pre-existing technology vendor relationships). The right posture is to incorporate the facility’s specialist into the activation protocol as a co-responder, execute a short-form subcontract for the engagement, and preserve the restoration company’s role as site coordinator. Fighting to replace a specialist the facility already trusts is almost never worth it.

    How many specialists per category is the right bench depth? Two is the floor, three is comfortable, four starts to become hard to actively maintain. For document and electronics, where national capacity is mature, two is usually enough because the major players have national reach. For art and medical, where specialty expertise is regional and capacity is thinner, three specialists in the primary service geography is often appropriate.

    What happens when the specialist’s primary capacity is exhausted during a CAT event? This is the operational stress test the bench is most likely to fail. The defense is to build the bench with enough depth that secondary specialists are available when primaries are saturated, and to acknowledge CAT limitations explicitly in the ESAs with facilities. Honest CAT communication is better than bench overcommitment.

    How does the bench change between residential and commercial work? Residential losses rarely activate the specialty bench. The individual dollar values, the regulatory overlays, and the irreplaceable-asset dynamics do not scale down to most residential work. The bench is primarily a commercial asset, which is why this cluster focuses on commercial accounts.

    What investments does building the bench actually require? Legal fees for master subcontractor agreements (2,000-5,000 for the first agreement, then 500-1,500 per additional specialist with the template), travel for operational interviews and tabletops (minimal if done remotely, moderate if done in-person), and time — forty to eighty hours over ninety days for the initial bench build, then ongoing maintenance of two to four hours per specialist per quarter. Compared to the revenue uplift from signed commercial accounts that depend on the bench, these numbers are trivial.

    What is the single most important piece of advice for a restoration company building its first bench? Start with one category and do it well before expanding. A restoration company with a real documented bench in document recovery — two or three qualified specialists with current insurance, executed subcontractor agreements, operational-leader relationships, and at least one tabletop exercise completed — is already ahead of most of its competitors. Adding electronics next, then medical or art based on account portfolio, keeps the work focused and prevents the bench from becoming a paper exercise that looks good in a pitch deck but falls apart on the night of an event.

    What is the difference between a specialist bench and a preferred vendor list? A preferred vendor list is a roster of companies a facility calls first. A specialist bench is a pre-contracted, pre-qualified, rehearsed operational infrastructure with executed master agreements, documented activation protocols, tracked insurance renewals, and an after-action feedback loop. The list is what most restoration companies call their bench. The actual bench is what the best restoration companies operate.