If you own a restoration company doing somewhere between $2M and $10M a year, you are operating in the most actively consolidated environment this industry has ever seen. Reported figures put the U.S. restoration market at roughly $7.1B in 2025, growing in the 5–6% CAGR range, with 50+ private equity platforms reportedly acquiring operators at multiples in the 4x–7x EBITDA range. Quality scaled operators in the $8M+ range have reportedly traded at the upper end — approximately 6x–8x EBITDA — when the asset is built right.
Almost none of that value gets captured by accident. The org chart you build at $2M determines whether you can survive $5M. The systems you install at $5M determine whether $10M makes you or breaks you. And the structure at $10M determines whether a PE platform sees you as a bolt-on at a discount or a regional anchor at a premium.
Here is the honest breakdown of what the org should look like at each revenue milestone, what the typical owner gets wrong, and what an exit-aware growth path actually requires.
$2M: The owner-operator squeeze
At $2M, the owner is still the bottleneck of every consequential decision. A typical structure: the owner does sales, estimating, and major-loss oversight; one office admin handles AR/AP and scheduling; six to eight technicians split across two to three trucks; one lead tech runs supplements informally. Reconstruction is either non-existent or subcontracted ad hoc.
What this stage actually feels like: gross margins on mitigation can run in the reported 65–75% range, but the owner’s labor is uncosted. If you charged your own time at the rate of a real operations manager (approximately $80K–$110K fully loaded), most $2M shops would discover their actual margin is thinner than their P&L suggests.
The mistake at this stage: hiring more techs to grow revenue. More techs at $2M without a coordination layer creates more chaos, not more profit. The next hire is not a fifth tech. It is the first non-owner decision-maker.
$5M: The operations manager inflection
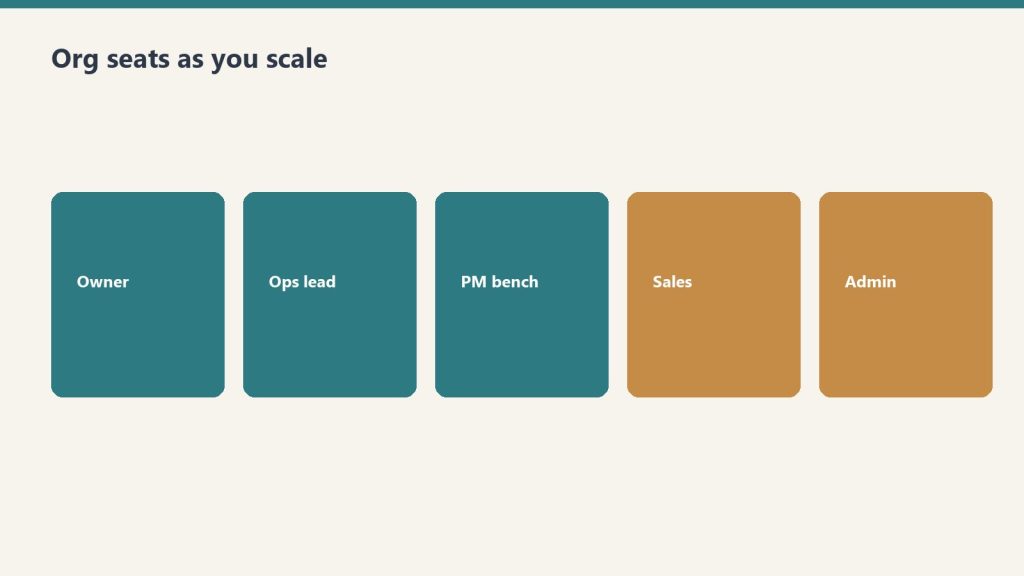
Seats change as revenue changes — titles are not the strategy.
$5M is where the structure has to change or the owner will burn out. The proven move is to hire a real operations manager — someone who owns the mitigation P&L day to day so the owner can focus on relationships, supplements, and growth. Reported compensation ranges for restoration operations managers cluster around $80K–$120K base plus variable, depending on market.
The $5M org typically looks like: owner; operations manager; one project manager for mitigation; one project manager (or a lead carpenter functioning as one) for reconstruction; office admin handling AR/AP; a dedicated estimator or supplement coordinator; 10–14 technicians across 4–6 trucks; one or two carpenters or subs handling reconstruction in-house.
This is also the stage where adding reconstruction matters disproportionately. Reported gross margins on reconstruction land in the 25–40% range — lower than mitigation but on much larger ticket sizes. A company that captures 25–30% of its mitigation revenue as in-house reconstruction by Year 3 of scaling tends to be substantially more valuable at exit, because reconstruction revenue is harder to replicate and stickier with carriers.
The mistake at this stage: the owner refuses to fully hand over the mitigation P&L. The operations manager becomes a dispatcher instead of a real GM. The org gets stuck at $5M for years.
$10M: The platform-decision stage
Platform-decision stage: managers own the week.
At $10M, the question is no longer “how do we grow?” — it is “what are we growing into?” There are two paths and they require different org structures.
Path A — single-market dominance. Stay in one metro, deepen TPA relationships (typically expanding from 2–3 carrier programs to 4–6), build a dedicated commercial division, and push toward $15M–$18M in a single footprint. Org: owner shifts to CEO role; operations manager promoted to COO; one mitigation manager; one reconstruction manager; commercial division lead; in-house controller or fractional CFO; dedicated marketing manager; office admin team of 2–3; 20–30 field staff.
Path B — multi-location expansion. Open a second branch in an adjacent market. This is where most $10M companies break. The org has to duplicate without doubling overhead: branch manager who reports to a regional operations leader; standardized SOPs, training, and KPIs; shared back-office (AR/AP, HR, marketing) from the home office; one finance function across both branches.
Reported industry experience is that the second location is the hardest. Branch three and four are dramatically easier if branch two is run with discipline. Most owners who fail at multi-location failed because they opened branch two as a bolted-on copy of branch one and did not build a real regional management layer in between.
$25M: Platform-ready
By $25M, the company is no longer a restoration business in the operational sense. It is a portfolio of branches with a central operating system. Org at this stage typically includes: CEO; COO; CFO (real, not fractional); VP of operations; regional operations managers (one per 2–3 branches); a dedicated commercial sales team; a marketing director; HR director; training manager; and 60–120+ field staff.
This is the structure PE platforms actually pay premiums for. The reported pattern: companies built around the owner trade at the lower end of the 4x–7x EBITDA range. Companies built around a system, with EBITDA visibility, repeatable branch economics, and a non-owner-dependent management team, trade at the upper end — approximately 6x–8x EBITDA, with some strategic transactions reportedly going higher.
The exit-aware framing
Exit-aware framing — org chart is part of the multiple.
Most restoration owners build the org chart they need today. Owners who exit well build the org chart their next buyer will want. The functional difference is small. The financial difference is enormous.
At $5M EBITDA of $1M, the difference between a 4x exit and a 7x exit is $3M. That gap is almost entirely a function of org structure, not revenue. Two restoration companies with identical revenue and identical margins will trade at different multiples if one is owner-dependent and the other is system-dependent.
Bottom line
The growth path is not a revenue chart. It is a sequence of structural inflection points. At $2M, the next hire is not a tech — it is a manager. At $5M, the next decision is not “more sales” — it is whether the owner will actually hand over the mitigation P&L. At $10M, the decision is single-market depth versus regional expansion, and the org has to be built before the second branch opens. At $25M, the company is either a platform asset or a glorified job shop — and the buyer can tell the difference in the first meeting.
The market is paying premium multiples for companies that look like platforms. Build the org that gets paid.
What is the right first non-tech hire for a $2M restoration company?
An operations manager or general manager who can own the mitigation P&L day to day, freeing the owner to focus on sales, supplements, and growth. Hiring another technician at this stage typically adds chaos, not profit, because the coordination bottleneck is the owner, not the field capacity.
When should a restoration company add in-house reconstruction?
Most owners benefit from adding reconstruction once they hit roughly $3M–$5M in mitigation revenue and have a stable operations manager in place. Reconstruction increases average ticket size, deepens carrier relationships, and is harder to replicate, which raises the exit multiple. Adding reconstruction before the org can support it usually just adds risk and overhead.
What EBITDA multiple do restoration companies sell for in 2026?
Reported ranges put quality restoration operators at 4x–7x EBITDA, with companies scaled to $8M+ in revenue and built around a system rather than the owner reportedly trading at the upper end of approximately 6x–8x EBITDA. Smaller operations under $500K in SDE often transact closer to 2.8x–3x on an SDE basis rather than an EBITDA basis. Numbers vary by region, carrier relationships, and quality of management team.
Is multi-location expansion or single-market depth the better growth strategy?
Both work, but they require different org investments. Single-market depth at $15M–$18M from one footprint can produce strong cash flow with less management complexity. Multi-location expansion produces higher exit valuations and platform optionality, but only if a regional management layer is built before the second branch opens. The most common failure mode is opening a second location without that layer in place.
Restoration company marketing is one of the most expensive paid-search categories in the United States. “Water damage restoration” keywords routinely clear $60–$85 per click in competitive markets, with reported outlier bids running well over $200 in metros like New York, Houston, and South Florida. Industry tracking has flagged some emergency-restoration terms breaking $500 per click in specific moments. Meanwhile, the average home-services lead via Google Local Service Ads (LSA) is roughly $53 — but water damage restoration sits at the premium end, with reported LSA cost-per-lead ranges of approximately $80–$180 depending on market.
If you run a $3M–$15M restoration company, this is the single biggest line item that nobody on your team is staring at correctly. Owners hear “marketing” and think website. The real fight in 2026 is channel allocation: how much should you spend on LSA, how much on Google Search Ads, and how much on owned SEO — and at what point does each one stop scaling? Here is the honest breakdown a $5M owner needs before their next marketing budget meeting.
The three channels that actually matter
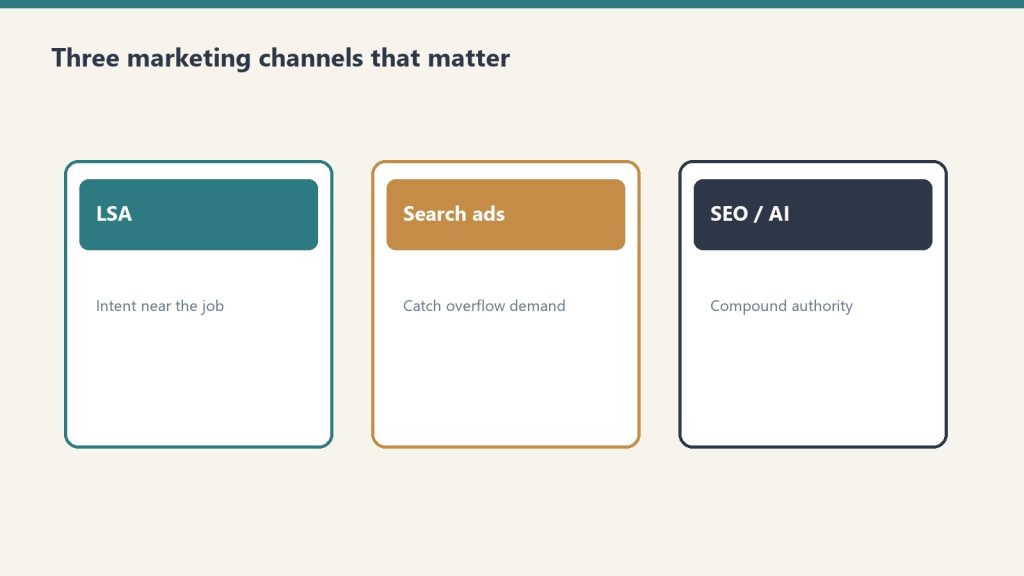
Three channels that actually matter for restoration demand.
For commercial water and fire restoration in 2026, three channels do the heavy lifting: Google Local Service Ads (the LSA “Google Guaranteed” boxes at the very top of the SERP), Google Search Ads (the paid text ads below LSA), and organic SEO (the map pack plus blue links). Everything else — Yelp, Angi, HomeAdvisor, Facebook, programmatic display, lead-broker buys — is either supplemental, declining, or actively cannibalizing your margin. The first decision is choosing where the bulk of your new-customer budget goes among those three.
Local Service Ads (LSA) — the default starting point in 2026
LSA is the highest-real-estate placement on a phone screen, period. For emergency-driven categories like water damage and mold, that real estate matters more than anything else. Reported 2026 cost-per-lead for water damage restoration through LSA generally falls in the $80–$180 range, with some markets reporting averages closer to $100 in stable competitive conditions. On a $6,000 average ticket, even a $150 LSA lead at a 25–35% close rate produces a customer acquisition cost (CAC) of roughly $450–$600 — which is workable on jobs that gross $1,800–$2,400.
The catch: Google removed credits for “job type not serviced” and “geo not serviced” leads in 2025, meaning every junk lead now hits your card with no recourse. You have to dispute leads inside Google’s dispute window and you have to answer your phone in under 30 seconds. LSA also weights reviews more heavily than any other channel — a 4.6 average will visibly underperform a 4.9 in the same zip code. If your review velocity is under 8 per month, fix that before you scale LSA spend.
Google Search Ads — the diminishing-returns layer
Below LSA, traditional Google Search Ads remain expensive and uneven. Reported 2026 average CPC for water damage restoration keywords falls into bands: bottom-of-funnel emergency keywords like “emergency water damage [city]” run $60–$85; less-direct terms like “water damage cleanup near me” run $40–$65; awareness-stage keywords like “what to do after a flood” run $20–$40. The trap is that close rates on Search Ads have been compressing for three reasons: LSA is taking the highest-intent clicks, AI Overviews are stealing informational queries, and click fraud from competitor bots remains nontrivial.
For most restoration owners, Search Ads should be a defense-and-coverage play, not a primary growth channel. Bid on your own brand name to keep TPA programs and franchise competitors from arbitraging your traffic. Bid on the keywords LSA does not cover well (commercial, mold remediation, biohazard, contents pack-out). Cap monthly spend. Watch the CAC, not the CPC.
SEO — the compounding asset that owners under-invest in
Owned SEO — Google Business Profile plus a real content engine on the company website — is where the math eventually breaks in your favor. Multiple cross-industry benchmarks in 2025–2026 put the cost-per-lead delta between SEO and paid search at roughly 4x–6x lower for SEO once a site is mature (typically 12–18 months in). One widely cited cross-industry benchmark places SEO CPL near $31 versus paid search closer to $181. Restoration-specific tracking from agencies serving the category has reported organic CPL well under $50 in established markets after 18+ months of investment, while paid CPL stays in the $150+ band.
The painful truth: SEO has a CAC of essentially zero on the marginal lead, but you cannot start it in January and expect leads in March. The owners who win SEO in restoration started 24 months ago, publish 6–12 useful pieces a month, and have a Google Business Profile with 500+ reviews and weekly post activity. If you have not started, your starting line is today — not next quarter.
The honest allocation for a $5M restoration company in 2026
A defensible 2026 marketing budget for a $5M residential and small-commercial restoration company, assuming 60% TPA-fed and 40% self-generated, looks roughly like this on the self-gen side:
LSA: 45–55% of self-gen ad spend. Highest immediate ROI. Cap by service area until close rate clears 30%.
Google Search Ads: 15–20%. Brand defense plus commercial, mold, and biohazard keywords LSA underweights.
SEO and Google Business Profile: 25–35%. This is content, on-site technical work, review-generation systems, and GBP weekly posts. Treat it as an asset, not a cost.
Everything else (Yelp, Angi, Nextdoor, paid social): under 5% combined, and only with tracked phone numbers per channel.
If your current mix is 80%+ LSA and 0% SEO, you are renting your customer pipeline from Google at a rate that will keep rising. If your current mix is 80%+ SEO and 0% LSA, you are leaving the highest-intent emergency calls on the table for competitors who will outbid you for them.
What to measure, not what to chase
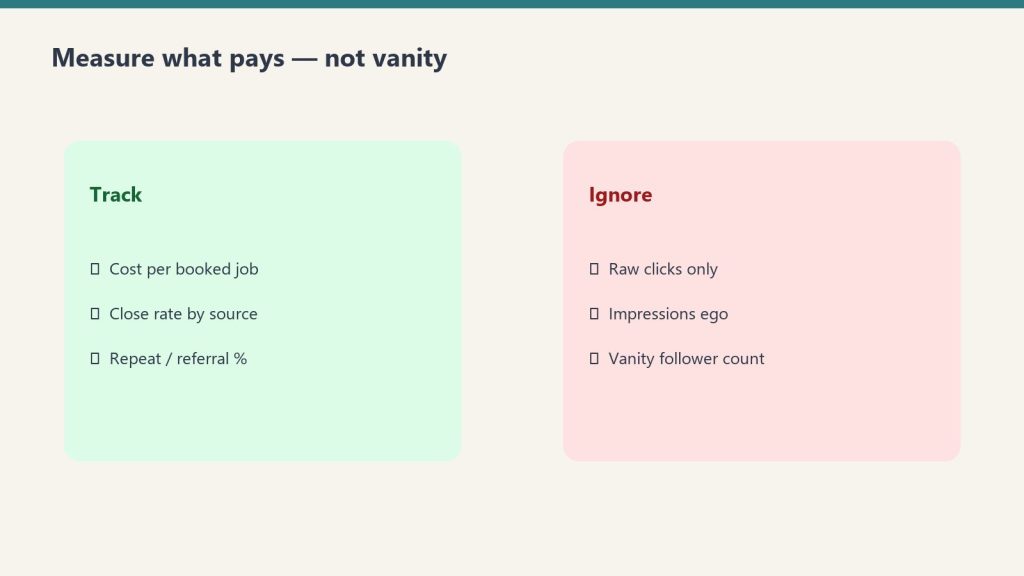
Measure what pays — not vanity.
CPC, CPL, and CAC are not the same number. Restoration owners chase CPC because Google Ads dashboards make it visible. The metric that should sit on your monitor is blended CAC by channel, calculated quarterly: total channel spend divided by booked jobs from that channel. Track three more numbers next to it — close rate from lead to booked job, average ticket size by channel, and lifetime value adjustments for repeat and referral. A $180 LSA lead with a 35% close on $7,000 average ticket is a different business than a $40 organic lead with a 12% close on $2,200 average ticket — even though the CPL looks better in column B.
Bottom line
Bottom line: booked jobs beat pretty dashboards.
In 2026, LSA pays the bills, Search Ads defends the perimeter, and SEO is the only channel that compounds. The restoration owners who will be writing larger checks to their estimators in 2028 are the ones who fund all three this year — and the ones who refuse to pay $150 for a water damage lead because “that’s expensive” will keep watching franchise competitors and out-of-town aggregators win the calls that finance their own retirement. The expensive lead is the one you didn’t bid on at 2 a.m. when the house was actively flooding.
What is a good cost per lead for a water damage restoration company in 2026?
Reported 2026 ranges put water damage LSA cost-per-lead at roughly $80–$180, with some stable markets averaging closer to $100. Google Search Ads CPL is generally higher and more volatile. Organic SEO CPL trends well under $50 in mature programs after 12–18 months. Evaluate against your average job size and close rate, not against a flat industry number.
Are Google Local Service Ads still worth it for restoration companies?
Yes, for emergency categories LSA remains the most cost-efficient paid channel in 2026 because of its top-of-screen placement and pay-per-lead structure. The caveats: Google removed credit for off-service-area and wrong-job-type leads, review velocity matters more than ever, and you have to answer the phone in under 30 seconds to keep ranking.
How long until SEO produces restoration leads?
Plan on 9–12 months for a Google Business Profile and review-driven program to generate meaningful local-pack volume, and 12–18 months for content-driven organic leads to show up in any volume. Owners who treat SEO as a 6-month sprint nearly always abandon it 30 days before it would have started working.
Should I use a marketing agency or build in-house?
Under $3M revenue, hire one credible local agency for LSA plus GBP and own SEO with a part-time writer. From $3M–$10M, split LSA/Search Ads with an agency and bring SEO content in-house under a marketing coordinator. Above $10M, build the function internally with a director-level hire — at that size your marketing spend funds a salary and the data needs to live on your side of the firewall.
Every restoration owner over fifty has the same question stuck in the back of their head: what is this thing actually worth? The honest answer in 2026 is somewhere between 2.3x SDE and 7x EBITDA — and the spread between those two numbers is not luck. It is the difference between a company a buyer wants and a company a buyer tolerates.
Here is what is happening in the market right now, what private equity is paying, and what kills the deal at the eleventh hour.
The 2026 Multiple Spread
Restoration M&A in 2026 sorts cleanly into three tiers. The cutoffs matter — they are not aesthetic.
Tier 1 — Sub-$2M revenue shops. Owner-operator businesses with one or two trucks, dependent on the founder for sales and crew leadership. These transact on Seller’s Discretionary Earnings (SDE), not EBITDA. Typical multiples: 2.3x to 3.0x SDE. The buyer is usually another restoration owner, a search-fund operator, or an industry veteran on their second act. There is no PE in this tier. The owner doing the work IS the asset, and that is exactly the problem.
Tier 2 — $2M to $5M revenue shops. The PE feeder zone. These get bought by platforms like BluSky, First Onsite, Belfor, ATI, and Code Red as bolt-on acquisitions. Multiples: 3.0x to 3.5x SDE, or 4x to 5x EBITDA if the company is clean enough to have real EBITDA at all. Purchase prices land between $900K and $2.5M. This is the sweet spot for industry roll-ups — large enough to have a real second-in-command, small enough to absorb without indigestion.
Tier 3 — $10M+ revenue, $2M+ EBITDA platforms. Now you are talking to PE directly, not through a strategic. Multiples: 5x to 7x EBITDA, occasionally higher for the right footprint. BluSky has announced 13 acquisitions in the last six years under Kohlberg & Company and Partners Group ownership. American Restoration rolled up 8 brands before exiting to Morgan Stanley. HighGround did 13 deals in five years before selling to Knox Lane. The playbook is well-documented. PE has put more than $6 billion into the space since 2018.
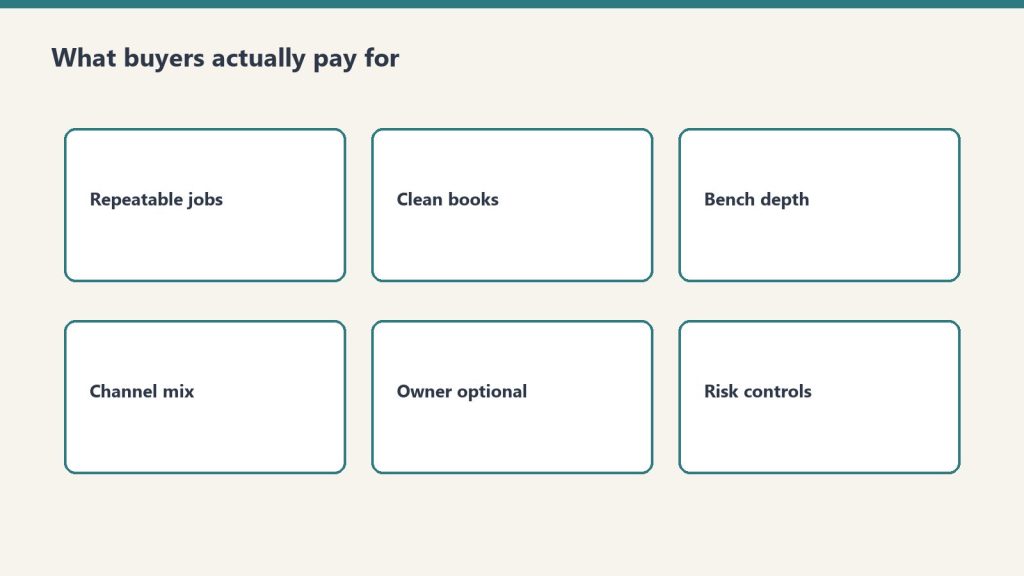
What Buyers Actually Pay For
Buyers pay for transferability — not heroic owners.
The multiple is a function of risk, not affection. Sophisticated buyers pay up for five things, in roughly this order:
1. Insurance carrier preferred-vendor status. If you are on the panel for State Farm, Allstate, USAA, Liberty Mutual, or any TPA program — Contractor Connection, Alacrity, Code Blue — that contract is the asset. It is also the hardest thing to replicate. Buyers will pay a premium for it because they cannot buy it any other way except by buying you.
2. Mitigation-heavy revenue mix. Water mitigation runs gross margins around 70-80%. Reconstruction often runs 10% or less. A company that is 65% mitigation and 35% reconstruction is worth materially more than the same revenue split inverted. Buyers will pull your job-cost reports line by line during diligence to confirm the mix is real and not just how you are categorizing.
3. Management depth below the founder. If you can take a two-week vacation and revenue does not blink, your multiple goes up by half a turn. If the phones stop ringing the moment you leave, you are selling a job, not a business. Hire a real general manager 18 months before you list.
4. CAT exposure under 20%. Catastrophic event revenue is lumpy and cannot be modeled. If 40% of your last three years came from one hurricane season, buyers will discount that revenue heavily — sometimes valuing CAT-driven dollars at half the multiple of recurring carrier work. Diversify your revenue base before going to market.
5. Clean books with a Quality of Earnings opinion. Every PE-backed deal includes a QoE — an outside accounting firm that re-audits your trailing twelve months and normalizes EBITDA. If your books are run on a personal-finance app and your CPA does taxes once a year, expect the QoE to find $200K-$500K of EBITDA adjustments that go against you. Spend $40K on a CFO-for-hire and a real GAAP P&L two years before sale.
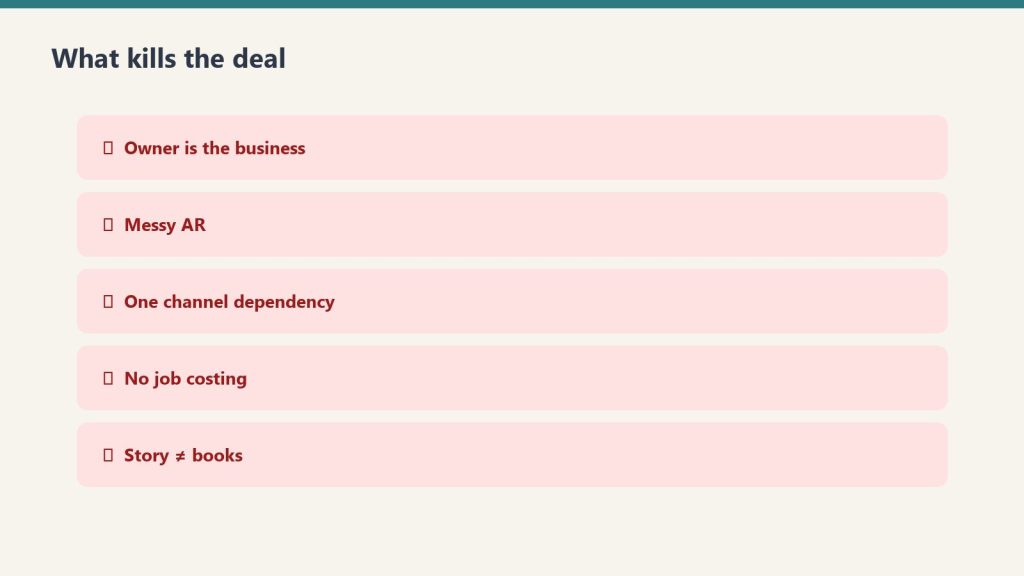
What Kills the Deal
What kills the deal is usually quiet and operational.
Roughly 30-40% of restoration LOIs do not close. Almost always for reasons the seller could have prevented.
The biggest deal-killer is customer concentration. If one TPA program represents more than 35% of revenue, buyers panic. They have seen what happens when Contractor Connection decides to rebid a region — entire $8M revenue lines disappear in a quarter. Diversify before you list.
The second is uncollected aged receivables. Restoration AR over 90 days is not an asset, it is a write-down waiting to happen. Buyers will deduct uncollected AR from purchase price dollar-for-dollar. Aggressively collect or write off everything before you go to market.
The third is licensing and certification gaps. IICRC, state contractor licenses, mold remediation certifications by state — buyers run a full compliance audit. A single expired contractor license in a key state can cost $50K-$150K at close.
The fourth is founder dependency on first-call relationships. If the property manager calls you personally when there is a flood — not a dispatch number, not a sales rep — buyers will require an earnout structure that makes you stay another three to five years. Most owners hate earnouts because they convert sale price into deferred contingent comp. Build the dispatch infrastructure before you list, and you keep the cash up front.
The Honest Bottom Line
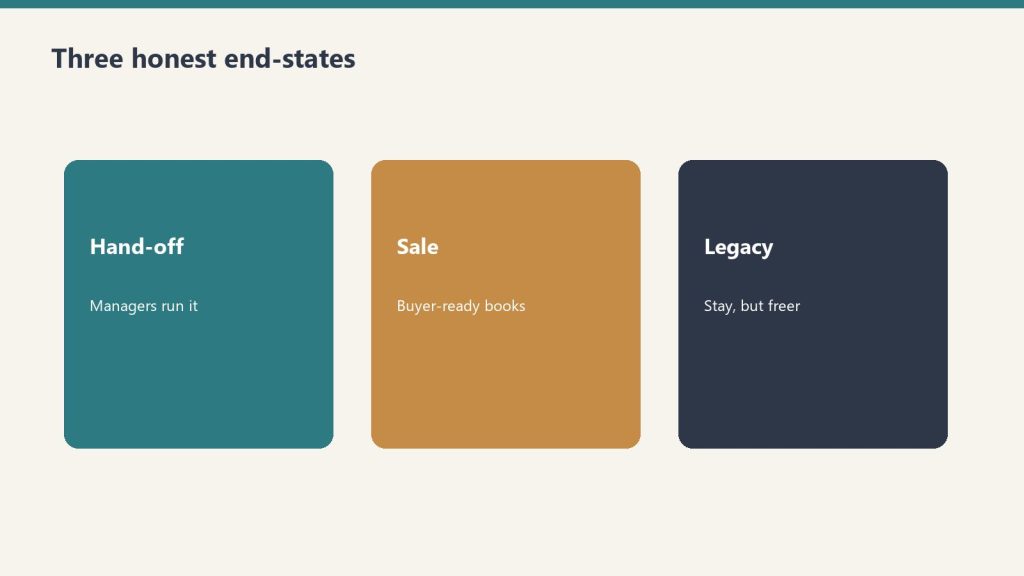
Honest bottom line: pick an end-state and work backward.
If you are a $3M revenue restoration company today and you want a clean exit at a real multiple, you have an 18-to-24 month preparation window. Use it to get the books on accrual, hire a GM, diversify off any single TPA, build mitigation revenue past 60% of mix, and get every certification current.
Do that, and a $3M shop running 18% EBITDA margins ($540K) sells at 4.5x to a strategic — about $2.4M cash at close. Skip it, and the same company sells at 2.6x SDE — closer to $1.4M, often with a punishing earnout attached.
The difference is one million dollars. The work to capture it is roughly nine months of operator focus. That is the highest-ROI work an exiting restoration owner can do.
Property owners and asset managers in institutional real estate operate in an increasingly layered ESG disclosure environment. GRESB drives investor-facing ESG scoring. CDP provides voluntary supply chain disclosure that is increasingly investor-requested. California SB 253 mandates Scope 3 disclosure for large entities. And the EU’s Corporate Sustainability Reporting Directive (CSRD) extends mandatory ESG reporting to European operations and, through supply chain due diligence requirements, reaches global real estate companies with EU exposure.
For BOMA members — building owners, REITs, asset managers — understanding which framework governs which obligations, and where they overlap, is essential for building an ESG program that satisfies all of them without duplicating work. This article maps each framework against the specific Scope 3 obligations it creates for property owners, with particular focus on the contractor supply chain data gap that sits at the intersection of all three.
GRESB: Investor-Driven, Asset-Level, Annual
GRESB — investor-driven, asset-level, annual.
GRESB is the primary ESG accountability mechanism for institutional real estate globally. It is not a regulation — it is an investor-driven benchmark that most institutional property owners participate in voluntarily because their capital partners require it. GRESB assessments are annual, asset-level, and scored on a 0–100 scale that investors use to compare portfolio ESG performance.
For Scope 3, GRESB evaluates both governance (do you have a Scope 3 target and supply chain policy?) and performance (do you have actual Scope 3 data?). Contractor emissions — Scope 3 Category 1 — factor into both components. Property owners without contractor data collection programs score lower on supply chain governance and leave Category 1 data fields blank in the Performance section.
GRESB is the most immediate Scope 3 pressure for most BOMA members because it directly affects your capital relationships. A poor GRESB score can affect asset valuations, borrowing costs, and investor mandates in ways that regulatory compliance does not.
CDP: Voluntary, Supply Chain Driven, Escalating
CDP’s supply chain program allows large corporations — including real estate companies’ major tenants and capital partners — to request Scope 3 supply chain data from their vendors. For property owners, CDP requests typically arrive from two directions: from institutional tenants whose corporate ESG programs require supply chain data from their landlords, and from institutional investors whose own CDP commitments require portfolio-level Scope 3 supply chain data.
CDP participation is voluntary, but declining a CDP request from a major tenant or capital partner has commercial consequences. As CDP participation expands — the program now covers thousands of companies — the probability that a significant counterparty will request Scope 3 data from your organization continues to increase.
California SB 253: Mandatory, Regulated, Enforced
California SB 253 — mandatory and enforced.
SB 253 is the only mandatory framework in this set, at least for US-domiciled organizations. It applies to entities doing business in California with revenues above the threshold, requires Scope 1 and 2 disclosure starting with fiscal year 2025 data, and adds Scope 3 starting with fiscal year 2026 data. CARB administers the program and has authority to assess penalties for non-compliance and material misstatement.
For real estate entities with California assets, SB 253 transforms the Scope 3 contractor data question from an investor relations consideration into a legal compliance obligation. The same contractor emissions data that improves your GRESB score and satisfies CDP supply chain requests now also needs to be accurate enough to withstand CARB review.
Where Restoration Contractor Data Fits in Each Framework
Where restoration contractor data fits.
The Restoration Carbon Protocol addresses the same data gap across all three frameworks. An RCP-compliant restoration contractor provides project-level emissions data in a format aligned with GHG Protocol Category 1. That data feeds directly into your GRESB Performance section, satisfies CDP supply chain data requests for Category 1, and provides the documented, methodology-backed Scope 3 Category 1 data that SB 253 requires.
The strategic efficiency argument for RCP adoption by property owners is that solving the restoration contractor data problem once solves it for all three frameworks simultaneously. You do not need different data for GRESB, CDP, and SB 253 — you need GHG Protocol Category 1 data, and RCP produces it in that format.
Building a Unified Response
For BOMA members navigating GRESB, CDP, and SB 253 simultaneously, the most efficient path is a unified Scope 3 data program rather than three separate compliance efforts. The foundation is a GHG Protocol-aligned inventory methodology that covers all fifteen Scope 3 categories. Contractor data — collected through RCP-compliant vendor agreements and green lease extensions — feeds into that inventory once and satisfies all three frameworks.
The timeline pressure is real: SB 253 Scope 3 data collection for fiscal year 2026 should already be underway, GRESB 2026 assessments will open in the first quarter, and CDP supply chain requests arrive year-round. The property owners who have built the contractor data infrastructure now — preferred vendor panels with RCP adoption, ESG clauses in service agreements, documented methodology — will be the ones with defensible Scope 3 inventories when all three frameworks converge on the same data set in 2027.
Both require Scope 3 GHG data aligned with the GHG Protocol Corporate Standard. GRESB collects it through an annual assessment submitted to the benchmark platform. SB 253 requires public disclosure filed with CARB. The underlying data set is the same — a GHG Protocol-compliant Scope 3 inventory by category — which is why building one unified inventory program satisfies both frameworks efficiently.
How does CSRD affect US-based property owners?
The EU’s Corporate Sustainability Reporting Directive (CSRD) applies directly to large EU-domiciled companies and EU subsidiaries of non-EU companies above defined thresholds. For US-based real estate companies with EU operations or EU-listed capital partners, CSRD may apply directly. Even for those it does not reach directly, CSRD’s supply chain due diligence requirements mean EU-based capital partners and tenants will increasingly request Scope 3 supply chain data from their US counterparties as part of their own CSRD compliance.
What is the Restoration Carbon Protocol and why do BOMA members need it?
The Restoration Carbon Protocol (RCP) is an industry self-standard that gives restoration contractors a structured GHG accounting methodology for project-level emissions reporting. For BOMA members, RCP-compliant contractors provide the Scope 3 Category 1 data needed for GRESB performance scores, CDP supply chain responses, and SB 253 mandatory disclosure — in a format directly compatible with GHG Protocol reporting requirements.
Green leases have been a standard tool in the institutional real estate ESG toolkit for over a decade. Originally designed to align landlord and tenant incentives around energy efficiency, green lease clauses have evolved to cover data sharing, sustainability reporting, and — in more sophisticated agreements — explicit GHG emissions obligations.
The same contractual logic that makes green leases effective for tenant emissions management can be applied to the contractor supply chain. Property owners who have invested in green lease programs for tenant Scope 3 (Category 13) data now have a parallel opportunity: using vendor agreement language to systematically collect Scope 3 Category 1 data from the contractors who perform work on their assets.
What Green Lease Language Has Achieved — and Where It Stops
What green lease language has achieved — and where it stops.
Modern green lease frameworks — developed by BOMA, the Institute for Market Transformation, the Urban Land Institute, and others — have established standard clauses for energy data sharing, sub-metering requirements, sustainable operations standards, and ENERGY STAR reporting. These clauses give property owners a contractual mechanism to collect the tenant data needed for GRESB Category 13 reporting and corporate GHG inventories.
Green leases stop at the tenant boundary. They do not govern the contractors the property owner engages for capital projects, maintenance, and emergency response. Those contractor relationships are covered by master service agreements, purchase orders, and emergency vendor panel arrangements — none of which have traditionally included GHG data reporting requirements.
Extending the Logic: Contractor ESG Clauses
Extending the logic — contractor ESG clauses.
The Green Lease 2.0 framework extends the proven lease-language approach to contractor agreements. The principle is identical: establish a contractual data delivery obligation, specify the format and methodology, and make compliance a condition of the vendor relationship.
For restoration contractors specifically, the relevant clause structure covers three elements. A methodology requirement — specifying that the contractor must use a recognized GHG accounting methodology (such as the Restoration Carbon Protocol) for calculating project emissions. A data delivery requirement — specifying that a project emissions report in a format compatible with GHG Protocol Category 1 reporting must be delivered within 30 days of project completion. And a pre-qualification requirement — specifying that participation in the property owner’s preferred restoration vendor panel requires demonstrated GHG reporting capability prior to emergency deployment.
Why the Pre-Qualification Step Matters
The most important element of the contractor ESG clause framework is pre-qualification — establishing GHG reporting capability before the loss event occurs. Property owners cannot negotiate data requirements at 2 AM when a pipe bursts. The contractual infrastructure needs to exist before the emergency.
Pre-qualification creates a preferred vendor panel of restoration contractors who have adopted RCP or an equivalent methodology and are contractually committed to delivering project emissions data. When a loss event occurs, the property manager calls from that panel — and GHG data collection is already built into the engagement.
What This Looks Like for GRESB and SB 253
What this looks like for GRESB and SB 253.
For GRESB participants, a documented contractor ESG clause program with demonstrated adoption across your preferred vendor panel satisfies the supply chain governance requirements in the Management component of the GRESB assessment. It shows that your organization has policies in place, that those policies have contractual teeth, and that you are actively collecting contractor emissions data — not estimating it.
For SB 253, the contractor ESG clause approach provides the documented data collection methodology that CARB’s guidance suggests as the evidentiary standard for Scope 3 Category 1 reporting. Organizations that can demonstrate a systematic contractor data collection program — rather than spend-based estimation — are better positioned for both initial compliance and the audit scrutiny that mandatory disclosure programs inevitably generate over time.
Green Lease 2.0 is not a dramatic reinvention. It is the application of a framework that already works — for tenants — to the contractor relationships where property owners have an equivalent data obligation and an equivalent contractual lever to close it.
Property owners managing large commercial real estate portfolios have made significant progress on Scope 1 and Scope 2 emissions. Energy management systems, green building certifications, and utility procurement strategies have given asset managers real tools for reducing and reporting direct and indirect energy emissions. Scope 3 Category 1 — the contractor supply chain — has been the persistent blind spot.
The Restoration Carbon Protocol (RCP) is designed to close the most acute piece of that gap: the emissions generated by restoration contractors during loss events and emergency response projects. This article explains what the RCP covers, how it generates the data property owners need, and how to integrate it into your ESG program and vendor management processes.
Why Restoration Contractors Are a Unique Scope 3 Challenge
Why restoration contractors are a unique Scope 3 challenge.
Most contractor Scope 3 challenges can be addressed through procurement policy — adding ESG reporting requirements to RFPs, master service agreements, and annual vendor reviews. This works for planned, recurring vendor relationships where you control the selection process and the contract terms.
Restoration contractors operate differently. They are engaged reactively, after a loss event. The property manager calls whoever is on the emergency vendor panel. The contractor mobilizes immediately. There is no competitive procurement, no ESG pre-qualification review, and no time to negotiate reporting requirements before work begins. The emissions happen regardless of whether data is collected.
This is why the RCP matters: it establishes the data collection methodology on the contractor’s side, before the loss event. A contractor who has adopted the RCP arrives at your property already equipped to generate the emissions data you need — no negotiation required at the time of loss.
What the RCP Measures
What the RCP measures.
The Restoration Carbon Protocol covers four primary emissions categories for a typical restoration project. Equipment fuel consumption — diesel generators, drying equipment, dehumidifiers, extraction units, and vehicles — is measured against hours of operation and fuel consumption logs. Materials with embedded carbon — replacement drywall, flooring, insulation, and structural components — are estimated using industry-standard embodied carbon factors. Waste generation — demolition debris, contaminated materials, and packaging — is tracked by weight and disposal method. Transportation — contractor vehicle miles, equipment hauling, and materials delivery — is calculated using distance and load data.
The RCP output is a project-level emissions report expressed in metric tons of CO2 equivalent, broken down by category. That format maps directly to GHG Protocol Scope 3 Category 1 reporting requirements — making it usable for GRESB data submissions, CDP supply chain responses, and SB 253 Scope 3 inventory filings.
How to Ask Your Vendors About RCP
For property owners building RCP adoption into their vendor management process, the conversation with restoration contractors has three components. First, ask whether the contractor has adopted the RCP or an equivalent GHG reporting methodology — this establishes whether data collection infrastructure exists. Second, ask what the output format looks like and whether it maps to GHG Protocol Category 1 — this determines whether the data is actually usable for your reporting obligations. Third, ask about the delivery timeline — GRESB, CDP, and SB 253 all require annual inventory data, and you need project-level data within the fiscal year it occurred.
Contractors who have not adopted RCP but are aware of it may be willing to do so if a significant client requests it. The RCP is an industry self-standard, not a certification program with fees or audits — the barrier to adoption is methodology, not cost.
Integrating RCP Data into Your ESG Program
Integrating RCP data into your ESG program.
Once you have RCP-compliant contractors on your preferred vendor panel, the data integration is straightforward. Each completed project generates an emissions report. Those reports are aggregated annually by property and portfolio. The totals feed into your Scope 3 Category 1 inventory alongside data from other contractor categories. The result is a documented, methodology-backed contractor emissions number — not a spend-based estimate — that satisfies the evidentiary standard for GRESB, CDP, and SB 253 reporting.
For BOMA members managing portfolios under institutional ESG frameworks, this is the difference between a defensible Scope 3 inventory and a gap that investors, auditors, and regulators will flag. The RCP does not solve the entire contractor Scope 3 problem — but it solves the most unpredictable piece of it, and it does so in a format property owners can actually use.
California’s Climate Corporate Data Accountability Act (SB 253) has been widely discussed in the context of large manufacturers and technology companies. Less discussed — but equally significant — is the exposure it creates for real estate entities. Property owners, REITs, and asset managers with California operations and revenues above the threshold face mandatory Scope 3 disclosure beginning with fiscal year 2026 data, due in 2027.
For BOMA members managing California commercial real estate, SB 253 changes the contractor relationship in a material way. The restoration contractor who responds to a water loss event at your San Francisco office tower, your Los Angeles industrial park, or your San Diego mixed-use development is generating Scope 3 Category 1 emissions that will need to appear in a mandatory public disclosure. And that contractor almost certainly has no mechanism for providing you that data today.
Who SB 253 Applies To
Who SB 253 applies to.
SB 253 applies to entities doing business in California with total annual revenues exceeding $1 billion. The law is administered by the California Air Resources Board (CARB). For Scope 3, the first reporting year is fiscal year 2026 — meaning data collection for Scope 3 needs to begin now for organizations that have not already started.
Many institutional real estate owners — national REITs, pension fund asset managers, sovereign wealth fund-backed property companies — clear the revenue threshold and have California assets. For these entities, SB 253 Scope 3 reporting is not a future consideration. It is an active compliance requirement with a defined first filing date.
The Reactive Vendor Problem for Real Estate
The reactive vendor problem for real estate.
SB 253’s Scope 3 requirement covers all fifteen GHG Protocol categories. For property owners, Category 1 (Purchased Goods and Services) includes every contractor engaged during the reporting year — planned maintenance vendors, capital project contractors, and reactive emergency-response vendors like restoration companies.
The planned vendor relationship is manageable. You can add ESG data reporting to your master service agreements with recurring maintenance contractors, HVAC firms, and janitorial services. You can build it into your RFP process and annual vendor reviews.
Reactive vendors are the structural problem. You do not choose when a pipe bursts or when a fire damages a tenant floor. You do not run a competitive procurement when a Category 1 water loss event hits your building at 2 AM. The restoration contractor who shows up is whoever your property manager calls — and the emissions from their equipment, materials, and transportation are your Scope 3 Category 1 obligation regardless of whether they provide data or not.
The Restoration Carbon Protocol as a Compliance Bridge
The Restoration Carbon Protocol (RCP) was developed specifically to address the reactive vendor data gap. It provides restoration contractors with a standardized methodology for calculating project-level GHG emissions across equipment fuel consumption, materials, waste, and transportation — and for communicating that data to property owner clients in a format aligned with GHG Protocol Category 1 requirements.
For SB 253 compliance purposes, an RCP report from your restoration contractor provides the documented, methodology-backed data needed to populate your Scope 3 Category 1 inventory for loss events. Without it, your organization faces the CARB-specified alternative: estimation using spend-based methods — which typically overstate emissions and provide no path to reduction.
What to Put in Your Vendor Agreements Now
What to put in vendor agreements now.
For California property owners preparing for SB 253 Scope 3 compliance, three vendor agreement changes directly address the restoration contractor gap. Add a GHG data delivery requirement to your preferred restoration vendor agreements, specifying RCP-compliant project emissions reports as a deliverable within 30 days of project completion. Add an ESG pre-qualification question to your emergency vendor panel selection process, asking whether candidates have adopted RCP or an equivalent methodology. And brief your property managers on the new data requirement — so that when a loss event occurs, GHG data collection is part of the project closeout process, not an afterthought six months later during annual reporting.
SB 253 enforcement has a ramp period, but the data collection requirement is retroactive to fiscal year 2026. The time to build the vendor data pipeline is now, before the loss events that will generate the data you need occur.
For property owners and asset managers in institutional real estate portfolios, the Global Real Estate Sustainability Benchmark (GRESB) is not optional — it is the standard by which your ESG performance is measured, scored, and reported to institutional investors. And as GRESB’s scoring methodology continues to align with TCFD, ISSB, and the GHG Protocol, Scope 3 supply chain data has moved from a nice-to-have to a measurable gap in your assessment score.
This article examines exactly where contractor Scope 3 data fits in the GRESB Real Estate Assessment, what the consequences of a data gap look like in practice, and how the Restoration Carbon Protocol (RCP) gives property owners a direct path to closing it.
How GRESB Measures Scope 3
How GRESB measures Scope 3.
The GRESB Real Estate Assessment is structured around two components: Management (governance, policy, targets, and reporting) and Performance (actual environmental and social data). Scope 3 emissions surface in both.
In the Management component, GRESB evaluates whether your organization has a GHG emissions reduction target that includes Scope 3, and whether your supply chain policies address emissions reporting from contractors and vendors. Property owners without explicit contractor emissions standards in their procurement policies lose points here.
In the Performance component, GRESB collects actual GHG data at the asset level — and Scope 3 Category 1 (Purchased Goods and Services, including contractors) is part of the expected data set for organizations reporting under GHG Protocol Corporate Standard.
The Contractor Data Gap in Practice
The contractor data gap in practice.
Most property owners managing large portfolios have reasonable visibility into Scope 1 (direct combustion at owned assets) and Scope 2 (purchased electricity). The contractor supply chain is where the inventory breaks down.
Restoration contractors are among the highest-emission vendor categories in a property owner’s supply chain — yet they are engaged reactively, after loss events, and almost universally lack any mechanism for providing GHG data to their clients. A commercial building fire or flood event that triggers a six-figure restoration project will generate significant Scope 3 Category 1 emissions. Those emissions belong in your GRESB data. In most cases, they are simply missing.
What RCP-Compliant Contractors Provide
The Restoration Carbon Protocol gives restoration contractors a standardized methodology for calculating and communicating project-level emissions data — covering equipment fuel consumption, materials with embedded carbon, waste generation, and transportation. RCP output maps directly to GHG Protocol Category 1 reporting requirements.
For GRESB participants, this means an RCP-compliant restoration contractor can provide the data needed to populate your Scope 3 Category 1 inventory for loss events — closing a gap that most property owner GHG inventories currently leave blank. That data supports your GRESB Performance score and demonstrates supply chain governance maturity in the Management component.
Tenant Emissions: The Category 13 Problem
While contractor data is the most actionable gap for most BOMA members, tenant emissions represent the largest Scope 3 exposure in most property portfolios. GRESB specifically evaluates whether property owners collect tenant energy and emissions data — and whether green lease clauses are in place to facilitate that collection.
The contractor and tenant problems are structurally similar: both involve third parties operating within your assets whose emissions appear in your Scope 3 inventory, but whose data collection you do not directly control. Green leases address the tenant side. Contractor ESG requirements in your procurement standards — and RCP adoption by your preferred vendor panel — address the contractor side.
Practical Steps for GRESB Participants
Practical steps for GRESB participants.
For property owners currently completing or preparing for GRESB assessments, three actions directly improve your Scope 3 contractor data position. First, add an ESG data reporting requirement to your preferred vendor agreements — specifying that contractors must provide project-level GHG data in a format compatible with GHG Protocol Category 1 reporting. Second, ask your preferred restoration contractors whether they have adopted the Restoration Carbon Protocol or a comparable methodology. Third, build contractor emissions data into your post-loss project closeout process — making GHG reporting a deliverable alongside cost documentation and certificate of completion.
These are not theoretical improvements. They are the specific steps that convert a data gap in your GRESB Performance section into a documented, improving metric — the kind institutional investors recognize as evidence of genuine ESG program maturity rather than checkbox compliance.
When the sustainability conversation turns to Scope 3 emissions, property owners and facility managers are often lumped together. Both manage buildings. Both hire contractors. Both face regulatory pressure from California SB 253, CSRD, and investor frameworks like GRESB and CDP. But the obligations, the data gaps, and the strategic levers are fundamentally different depending on which side of the lease you sit on.
BOMA members — building owners, asset managers, and property managers — occupy a distinct position in the Scope 3 landscape. You own or control the asset. Your tenants generate Scope 3 emissions inside your buildings under Category 13 (Downstream Leased Assets). Your contractors generate Scope 3 emissions during capital projects and maintenance under Category 1 (Purchased Goods and Services). And your investors increasingly require you to disclose both — through GRESB assessments, CDP supply chain requests, and emerging mandatory frameworks.
The Core Distinction: Asset Owner vs. Building User
Asset owner vs building user — the core Scope 3 distinction.
IFMA’s membership is primarily the corporate occupier — the facility manager who runs operations inside a building their employer leases or owns for non-real-estate purposes. Their Scope 3 exposure is Category 1: what they buy, including the contractors they hire for restoration, maintenance, and capital projects.
BOMA’s membership is the asset side of that equation. As a property owner, your Scope 3 inventory is more complex:
Category 1 (Purchased Goods and Services): Contractors you hire — restoration companies, mechanical contractors, janitorial services, construction firms during capital improvements
Category 13 (Downstream Leased Assets): Your tenants’ energy consumption and operations inside your building — the hardest Scope 3 category to measure and the one GRESB scrutinizes most closely
Category 11 (Use of Sold Products): For REITs and developers who sell or transfer properties
The tenant emission problem is uniquely a BOMA problem. Your tenants control the space. They set the thermostat, they bring in their own contractors, they determine actual energy consumption. But under GHG Protocol rules for property owners, their emissions may appear in your Scope 3 inventory — and GRESB will ask about them.
The Contractor Data Gap: Where BOMA and IFMA Converge
Where BOMA and IFMA converge on contractor data.
Here is where BOMA and IFMA face the same structural problem: restoration contractors, mechanical service firms, and specialty trade vendors who perform work on your properties have no standardized mechanism for reporting their Scope 3 emissions data back to you.
When a water damage event triggers a restoration project — emergency extraction, structural drying, mold remediation — the contractor mobilizes equipment that burns diesel, deploys materials with embedded carbon, and generates waste. All of that falls under your Scope 3 Category 1. And almost none of it gets captured in any formal emissions inventory.
The Restoration Carbon Protocol (RCP) is an emerging industry self-standard designed to fix this. It gives restoration contractors a structured methodology for calculating and communicating Scope 3 emissions data to their property owner clients — in a format that maps directly to GHG Protocol Category 1 reporting requirements.
GRESB and the Asset Manager Accountability Stack
GRESB and the asset-manager accountability stack.
For BOMA members managing assets in institutional portfolios, GRESB is the primary accountability mechanism. The GRESB Real Estate Assessment scores assets on environmental, social, and governance performance — and Scope 3 supply chain data is an increasingly weighted component.
GRESB participants who cannot provide contractor Scope 3 data leave points on the table. More importantly, as GRESB scoring evolves to align with TCFD and ISSB frameworks, the absence of supply chain data will increasingly flag as a material gap to institutional investors.
Green Leases: The BOMA Lever IFMA Doesn’t Have
One strategic lever available to property owners that IFMA FMs typically lack is the lease itself. Green lease clauses — requirements embedded in tenant agreements around energy reporting, contractor ESG standards, and waste management — give asset managers a contractual mechanism to drive Scope 3 data collection that facility managers simply cannot replicate.
The Institute for Market Transformation’s Green Lease Leaders program and BOMA’s own sustainability frameworks both provide templates. The opportunity is to extend the same logic to contractor agreements — requiring vendors like restoration companies to provide RCP-compliant emissions data as a condition of contract.
What This Series Covers
This BOMA Scope 3 series on Tygart Media examines the Scope 3 challenge specifically through the property owner and asset manager lens. We cover GRESB reporting obligations, green lease strategy, SB 253 and CSRD compliance for real estate entities, and the contractor data gap that sits at the intersection of both the BOMA and IFMA worlds.
The RCP thread runs through all of it — because whether you are a corporate occupier FM or a property owner, the restoration contractor showing up after a loss event is generating Scope 3 emissions that belong in someone’s inventory. This series is about making sure yours is complete.
Does GRESB require Scope 3 Category 1 contractor data?
GRESB’s Real Estate Assessment includes supply chain and contractor emissions as part of its environmental data collection. While the specific weighting evolves annually, institutional investors using GRESB increasingly expect property owners to demonstrate Scope 3 supply chain visibility. Gaps in contractor data weaken your GRESB score and signal portfolio risk to asset managers.
How is a property owner’s Scope 3 different from a tenant’s?
Property owners report Scope 3 from the asset ownership perspective — including downstream tenant emissions (Category 13), upstream contractor supply chain (Category 1), and capital project emissions. Tenants report from the occupier perspective — primarily Category 1 for their own purchased services. The same building can appear in both inventories under different Scope 3 categories.
What is the Restoration Carbon Protocol and why does it matter to BOMA members?
The Restoration Carbon Protocol (RCP) is an industry self-standard that gives restoration contractors a structured framework for calculating and reporting the Scope 3 Category 1 emissions associated with their work. For BOMA members, RCP-compliant contractors provide the data needed to close the contractor gap in your GHG inventory — supporting GRESB reporting, CDP responses, and SB 253 compliance.
Direct answer: A restoration company’s profitability is determined more by service mix than by total revenue. Industry references consistently show water mitigation gross margins of 70-80%, mold remediation 40-50%, fire damage 25-30% with some references showing 20-25%, and reconstruction commonly cited around 10% with high-capacity volume shops achieving up to 50%. Two shops with the same $5 million revenue and the same operational competence can produce radically different profit dollars depending on whether the mix is mitigation-heavy or reconstruction-heavy. The well-run shop measures gross margin by line, prices each line to absorb appropriate overhead, and chooses mix deliberately rather than letting it drift based on whatever walks through the door.
The previous article in this cluster framed the AR cycle as the foundation discipline. This article frames service mix as the most important strategic decision an operator makes. The decisions are linked — the cycle problem is harder to solve in a reconstruction-heavy mix than in a mitigation-heavy mix, because reconstruction billing cycles are inherently longer and reconstruction margin is inherently thinner. An operator working on both at once will find that fixing service mix actually compounds the AR cycle improvements from the previous article.
The case for thinking carefully about mix starts with arithmetic. Consider two restoration companies, both running $5 million in annual revenue with identical overhead structures, identical labor costs, and identical operational discipline. Company A runs 60 percent water mitigation at 75 percent gross margin and 40 percent reconstruction at 15 percent gross margin. Company B runs 30 percent water mitigation at 75 percent gross margin and 70 percent reconstruction at 15 percent gross margin. Same revenue, same competence — different financial outcomes. Company A produces roughly $2.55 million in gross profit; Company B produces roughly $1.65 million. The mix decision alone costs Company B about $900,000 in gross profit, which after fixed overhead becomes a far larger gap in net profit. The two companies look similar from the street and from the customer-facing pitch. They are not similar businesses.
This is the conversation most restoration owner-operators do not have with themselves. They think of revenue as the goal and mix as whatever happens. They take the work that comes in. The discipline this article describes is to invert that — to treat mix as the deliberate choice and revenue as the consequence of mix multiplied by efficient execution.
What each service line actually pays
Mix shifts margin more than slogans do.
Industry references including Restoration Profits, Kiwi Cashflow’s restoration CFO commentary, the Cost of Doing Business Survey covered by Restoration & Remediation Magazine, and restoration franchise public materials produce a consistent directional picture of gross margin by service line. The numbers vary by region, geography, and company-specific factors, but the relative ordering is robust.
Water mitigation. Gross margin 70-80 percent. The highest-margin line in restoration. The economic engine: equipment does most of the work. Air movers, dehumidifiers, and air scrubbers run on 24-hour cycles with limited human attendance. Xactimate’s mitigation pricing rewards the equipment-heavy model. A typical mitigation job has labor cost around 15-20 percent of revenue, equipment rental or amortization around 5-10 percent, materials and consumables around 2-5 percent, leaving roughly 70-80 percent for overhead absorption and profit. The math works because equipment, once owned, has marginal cost approaching zero per additional job day. Industry coverage from Claims Delegates and others has explicitly described high-margin mitigation strategies as “$1,000 per hour” lines when Xactimate is used correctly.
Mold remediation. Gross margin 40-50 percent. Lower than water mitigation because the labor content is heavier and the protective cost (PPE, containment, disposal) is real. Mold work is also more documentation-intensive, more regulated, and often more disputed by carriers, all of which add cost without proportional revenue. Mitigation-style equipment (HEPA filtration, negative-air, dehumidification) supplements but does not replace skilled hand labor for source removal and structural cleaning. Mold is a real margin line for shops with the capability, but it is not the equipment-leveraged windfall that water mitigation can be.
Fire damage restoration. Gross margin 25-30 percent commonly cited; 20-25 percent in some references. The work is labor-intensive, slow, contents-heavy, and odor-and-soot-management-heavy. Fire jobs are larger and more complex than water jobs, requiring skilled project management and coordination layered on the technical work. The pricing in Xactimate supports the work but does not provide the equipment-leverage that water enjoys. Fire-damage restoration is good revenue at honest margin, but it does not produce the windfall margin that an underloaded mitigation crew can produce on the right water job.
Reconstruction. Gross margin 10-20 percent in typical operator references; up to 50 percent for high-volume operators per Cleanfax-published commentary on the most efficient operators. The wide range reflects two different business models. The standard model treats reconstruction as a service line layered onto the restoration relationship — the restoration company handles the rebuild because the customer is already in their hands, but margins are construction-industry margins (10-15 percent) plus general overhead absorption. The high-volume model treats reconstruction as a primary business with restoration relationships as the customer acquisition channel — these shops have invested in subcontractor management, project management depth, scheduling systems, and supplier relationships that allow them to run reconstruction at 30-50 percent gross margin through volume efficiency and subcontractor leverage. Most owner-operator restoration shops run reconstruction in the 10-20 percent range. A few have built the operational discipline to run it higher.
Contents cleanup. Gross margin around 50-65 percent for shops with capability. Per the same Cleanfax operator commentary, high-capacity contents shops achieve 65 percent gross margin on cleaning and around 50 percent on packouts when subcontractor pricing is doubled into invoiced cost. Contents work is real margin for shops that specialize, more variable for shops that treat it as ancillary to structure work. This line has the largest gap between specialist operators and generalist operators.
Specialty services. Gross margin variable but often strong on coordination revenue. As covered in the specialty restoration cluster, specialty work performed through a vetted subcontractor bench produces coordination revenue at high effective margin (the coordination fee is high-margin because the direct work cost is the specialist’s, not the restoration company’s). Specialty work performed in-house by the restoration company is rare and is its own business model.
Biohazard, trauma, and crime scene cleanup. Gross margin commonly cited 40-60 percent for trained operators with appropriate licenses. This is a smaller volume, higher-emotional-stakes line that pays at a premium because few operators are equipped or willing to do it. Operators who specialize here can run profitable practices at relatively low total revenue.
The overhead absorption problem
Pure gross margin numbers do not tell the full story because each service line absorbs a different proportional share of fixed overhead. A shop that runs at $5 million revenue with $1.5 million in fixed overhead (rent, salaried staff, fleet, equipment depreciation, insurance, software, marketing) has to allocate that overhead across the work it produces.
The well-run shop allocates overhead to service lines based on the share of resources each line consumes, not based on revenue share. A reconstruction job uses substantially more project-management time, more office support, more procurement effort, and more accounting time per revenue dollar than a water mitigation job. If overhead is allocated by revenue share, reconstruction looks more profitable than it actually is and mitigation looks less profitable than it actually is.
The accounting fix is service-line P&L with deliberately allocated overhead. The shop sets up its accounting to track direct cost (labor, materials, equipment, subs) by service line, then allocates fixed overhead using a cost-driver methodology — project-management time, billing time, office support time, fleet usage — that reflects actual consumption. The result is service-line contribution margin that shows what each line is actually earning after overhead absorption, not just what it earns before overhead.
Most restoration shops do not run this analysis. Most operators are surprised by the answer when they do. Reconstruction often emerges as a marginal contributor or actual loser after appropriate overhead allocation, even when its gross margin looks acceptable. Water mitigation often emerges as a much larger contributor than its revenue share suggests. The strategic implications follow from the analysis — and they are usually different from what the gut-feel running of the business produced.
How mix actually shifts in the day-to-day operation
Day-to-day mix shifts are decisions — not accidents.
Mix is not chosen in a strategy session. It shifts based on a series of small decisions made across the operation, often without anyone realizing they are shifting mix.
Marketing channels favor specific lines. Google Ads bids on emergency water keywords drive water mitigation calls. Roofer partnerships drive storm-damage reconstruction. Insurance preferred-vendor program leads come in line-mix patterns specific to each program. The marketing decisions made in the prior cluster (Marketing Stack on Tygart Media) directly shape mix.
Sales scripts favor specific lines. The way the call-taker scopes the conversation, the way the on-site rep frames the work, and the way the project manager presents options to the customer all subtly steer the work mix. A shop whose sales conversation centers on “let us handle everything” tends to capture more reconstruction. A shop whose sales conversation centers on “we are the mitigation specialist” tends to keep more focused mix.
Staffing tilts the mix. A shop that has hired heavily on reconstruction project managers will sell more reconstruction because that is what the team is configured to deliver. A shop with deep mitigation lead techs and a thin reconstruction PM bench will lean toward mitigation. The org structure and the work mix shape each other.
Carrier program enrollments drive specific line mixes. Some carrier programs are mitigation-heavy, others are reconstruction-heavy, others are biohazard-and-emergency-response-heavy. The shop’s program portfolio shapes its inbound mix more than most operators recognize.
Customer relationship behaviors drive mix. A shop that subcontracts reconstruction to trade partners on relationship terms (offering them the rebuild work in exchange for emergency referral flow) keeps mitigation margin while passing through reconstruction. A shop that holds reconstruction in-house captures both lines but absorbs both margin profiles.
Recognizing that mix is the cumulative result of these small decisions is the first step. Choosing to make those decisions deliberately is the second.
Strategic mix archetypes
Most well-run shops fall into one of four mix archetypes, each with its own logic and its own trade-offs.
Mitigation specialist. Mix heavily weighted toward water mitigation and mold remediation, with reconstruction passed through to trade partners or refused entirely. Highest gross margin profile of the four archetypes; smallest revenue per claim; highest claim volume requirement to hit a given revenue target. This model works well in metro markets with high water-loss frequency and a reliable network of reconstruction partners. The trade-off is that the specialist sees a smaller share of total restoration spend per claim — the rebuild work and the contents work go to others — and the customer relationship is shorter.
Full-service generalist. Mix balanced across mitigation, reconstruction, and contents. Most common archetype in mid-size independent shops. Captures the full claim economically but at blended margin that includes the lower reconstruction line. Works in most geographies. Trade-offs: requires operational depth across multiple service lines, requires management depth to run reconstruction at acceptable margin, and tends to produce lower overall gross margin than the specialist model.
Specialty commercial wedge. Mix weighted toward commercial accounts with specialty recovery components (documents, electronics, art, medical equipment) plus the general mitigation and reconstruction those accounts produce. The model described in the previous specialty restoration cluster. Higher revenue per relationship, higher complexity, higher operational bar. Trade-offs: longer sales cycles, regulatory and compliance overhead, and dependency on a smaller number of larger accounts.
High-volume reconstruction operator. Mix weighted toward reconstruction at scale, with mitigation as a feeder. Less common as a deliberate strategy but possible — these are the operators who have built reconstruction operational discipline equivalent to a homebuilder or commercial GC and who run reconstruction at 30-50 percent gross margin. The Cleanfax-cited high-capacity volume shops fall in this archetype. Trade-offs: requires substantial management investment in reconstruction operations, exposes the business to construction-cycle dynamics, and runs into the long-cycle AR problem from the prior article harder than the mitigation-led models.
The choice of archetype is not permanent. Many shops evolve from one to another as they grow, change ownership, or respond to market shifts. The point is to choose deliberately, build the operations to support the chosen archetype, and resist drift back to whatever-walks-through-the-door because that drift is what produces undisciplined service mix and the lower margins that follow.
Pricing each line to absorb appropriate overhead
The 10-and-10 myth — that restoration contractors should bill 10 percent overhead and 10 percent profit on top of direct costs as the standard markup — is one of the most damaging conventions in the industry. Industry coverage from Restoration & Remediation Magazine has covered this extensively under the “10 and 10 myth” framing. The math simply does not work. A shop with $5 million in revenue and $1.5 million in fixed overhead is running at 30 percent overhead, not 10 percent. Pricing at 10-and-10 means the shop is losing money on every job and making it up only when extreme volume covers the gap.
The disciplined alternative is to know the shop’s actual overhead rate as a percentage of direct cost and to price each service line with a markup that absorbs an appropriate share. For a shop with 30 percent overhead, the minimum markup over direct cost is roughly 50 percent (which produces gross margin around 33 percent — exactly the breakeven before profit). For acceptable profit, markup of 75-100 percent over direct cost is more common. The Xactimate price list, when used correctly, supports this markup level on most service lines. The shop’s price list and Xactimate practice should reflect the true overhead structure and the target profit margin, not industry conventions that are decades out of date.
The pricing decision differs by service line. Water mitigation can support high markup because the equipment-heavy model produces low direct cost, leaving room. Reconstruction is harder to mark up because direct cost is dominated by subcontractor and material cost, both of which are visible to customers and adjusters. The well-run shop applies different markup logic to different lines and matches its pricing to its actual cost structure rather than to a uniform convention.
For shops that are uncertain whether their pricing is right, the diagnostic is simple. Pull twelve months of P&L. Compute gross margin by line. Compute fixed overhead as a percentage of revenue. Compute net margin. If net margin is below 8-10 percent, pricing or mix is wrong. If gross margin on water mitigation is below 70 percent, Xactimate practice is the likely culprit. If gross margin on reconstruction is positive at any level, the shop is doing better than many; the question is whether the reconstruction is absorbing its appropriate share of overhead. The numbers reveal the problem; the operator’s job is to diagnose specifically and intervene at the right point.
What to refuse
What to refuse is a margin decision wearing a values jacket.
The hardest discipline in service mix is refusing work that does not fit. Most restoration owner-operators struggle with this because every job feels like revenue and revenue feels like progress. But work that runs below contribution margin (revenue minus direct cost minus appropriate overhead allocation) actually subtracts from the business — every dollar of bad-fit revenue requires the next dollar of good-fit revenue to make up the loss.
Specific patterns of work that the disciplined shop is willing to refuse:
Reconstruction at price points that require the shop to break its actual cost structure. Customers and adjusters who insist on 10-and-10 markup on reconstruction are asking the shop to lose money on the rebuild. The discipline is to either decline or to pass the rebuild to a trade partner who can do it at the contemplated price.
Out-of-area work that requires excessive mobilization. The labor and equipment cost of crews working far from base eats margin in ways the customer does not see. A shop with capacity issues during a CAT event can sometimes justify out-of-area work at higher pricing, but routine out-of-area work at standard pricing is usually a margin loser.
Carrier programs whose pricing structure does not fit the shop’s cost structure. Some preferred-vendor programs price meaningfully below market with the expectation of volume making up for unit margin. Whether this trade is worth taking is operator-specific, but the shop that signs into every program offered without doing the math is signing into structural losses.
Customer relationships that consume management time at scale. Some customers and adjusters require an hour of phone time and three documentation revisions for every invoice. The shop’s project management cost on these accounts often exceeds the gross profit. The discipline is to identify these accounts and either reset the relationship or end it.
Work the shop does not have the operational depth to deliver well. Taking a fire job when the shop has no fire-experienced lead tech, or a commercial loss when the shop has no commercial PM, is taking work the shop will execute poorly and damage its reputation on. The work feels like revenue; the reputation cost compounds against future revenue.
The operator who can decline bad-fit work calmly and confidently is operating from financial clarity. The operator who cannot is operating from fear that the next call may not come. The financial clarity is what comes from running this analysis and knowing the numbers cold.
How this article fits the cluster
Mix is the second foundation decision after AR cycle. With both in place, the rest of the cluster has solid ground to stand on. The next article — equipment economics — depends on understanding mix because equipment ROI is line-specific (water mitigation equipment has different utilization economics than reconstruction equipment). The crew structure and KPI dashboard articles that follow build on both foundation decisions.
If the prior article (AR cycle) is the highest-leverage operational improvement most restoration shops can make, this article (service-line mix) is the highest-leverage strategic improvement. They are different kinds of work — AR is a tactical, weekly operating discipline; mix is a quarterly and annual strategic discipline — but both produce outsized returns relative to the effort required.
Should I be running service-line P&L if my accounting system doesn’t support it natively?
Yes, with manual allocation if necessary. The first version can be a quarterly spreadsheet exercise — pull total revenue, total direct cost, and total overhead from the financial statements, then estimate the mix and the line-specific direct cost ratios. The numbers are imprecise but directionally accurate, and they will surface the strategic question even before the accounting system is reconfigured. Once you have decided that mix matters, invest in setting up the accounting to produce the analysis automatically.
Why is reconstruction so much harder to make money on?
Three structural reasons. First, the work is dominated by labor and materials, both of which are heavily benchmarked by competitors and carriers. Second, the cycle is long, so working capital cost is higher. Third, the customer can see the cost of the materials and the visible labor in ways they cannot for mitigation, which makes pricing pressure harder to absorb. The operators who run reconstruction at high margin have invested in subcontractor management, supplier relationships, and project-management efficiency that takes years to build.
Should an owner-operator pursue the high-volume reconstruction archetype?
Probably not as a starting strategy. The high-volume reconstruction model requires substantial management infrastructure that is expensive to build and difficult to maintain. Most owner-operators who try to evolve into this model end up with reconstruction-heavy mix at standard 10-15 percent margin rather than the 30-50 percent the well-built operators achieve. The honest assessment is that this archetype works for a small number of operators who have the construction-management capability, and most owner-operators are better served by mitigation specialist or full-service generalist archetypes.
What is a realistic mix to target if I want to maximize gross profit?
A mix-of-business analysis specific to your geography, capability, and capacity is needed for an actual answer. As a directional reference, mitigation specialists often run 60-75 percent mitigation and mold (combined), 15-25 percent contents and specialty, and 0-15 percent reconstruction (often passed through). Full-service generalists run 35-50 percent mitigation and mold, 15-20 percent contents and specialty, and 30-50 percent reconstruction. The right mix for a specific shop is a function of the local market, the shop’s operational depth, and the owner’s risk tolerance.
Does the specialty restoration wedge from the prior cluster fit into mix strategy?
Yes, directly. Specialty work is a high-coordination-margin add to the mix. The specialty cluster’s commercial-account focus produces relationships that generate mitigation, reconstruction, and specialty revenue together, and the specialty coordination component is high-margin in a way that lifts the blended profile. Operators who have built specialty capability typically see their mix shift toward more mitigation and specialty, less commodity reconstruction.
How often should I revisit the mix question?
At minimum, annually as part of business planning. More frequently if the shop is growing fast, going through ownership changes, expanding geography, or seeing significant changes in carrier program enrollments. A quarterly directional review is good discipline. Monthly is overkill. Weekly is panic.
What if I’m carrying lines I’m bad at because I haven’t done this analysis before?
The disciplined response is to either invest in becoming good at the line (hire, train, partner) or exit the line. Carrying lines you are bad at is carrying work that produces below-average margin and below-average customer experience. It is the worst of both worlds. The annual review process should produce these decisions explicitly.
Are biohazard, trauma scene, and unattended death cleanup really good margin work?
For shops with proper licensing and trained crews, yes. The pricing supports the work and the competitive density is low because most operators do not want the work. The trade-offs are emotional weight on the crew, careful customer-facing communication, and licensing and disposal compliance overhead. For shops with the right operational fit, this is a legitimate niche.
What’s the relationship between mix and consolidator interest in acquiring my shop?
Consolidators value mix-driven margin profile. A shop with disciplined mitigation-heavy mix at clean margin is a more attractive acquisition target than a shop with the same revenue but lower margin from undifferentiated reconstruction-heavy mix. The mix work this article describes is also exit-positioning work, and operators who run it well over a few years are positioning for a stronger acquisition outcome whether or not they intend to sell.
What is the single move I should make this week from this article?
Pull last quarter’s P&L, estimate revenue and direct cost by service line, compute the implied gross margin per line, and compare to the industry directional ranges in this article. If your mitigation gross margin is below 70 percent, your reconstruction gross margin is below 10 percent, or your overall mix is reconstruction-heavy without operational depth supporting it, the analysis has identified the largest profitability lever in your business. Treat the answer as the agenda for the next quarter.