If you run a business in Mason County, two developments from this week deserve your attention — one because it may change where you source your branding and marketing work, and one because it signals what north Mason County’s commercial infrastructure might look like in five years.
OneStop Northwest: A Local Vendor for Services You Likely Source Outside the County
Most Mason County small businesses currently piece together their marketing, print, and IT needs from a mix of vendors — some local, some remote. OneStop Northwest LLC, a Union-based minority-owned company, is making a direct case that this doesn’t have to be true.
When its new downtown Shelton showroom opens on May 22, the company will offer Mason County businesses a single local vendor for: promotional products and branded apparel, commercial printing, custom company stores, website development, SEO and social media marketing, digital marketing, IT support, payroll automation, and government contracting for internet and phone services.
For a business spending time and money coordinating multiple service providers, consolidation has real value — not just in vendor management overhead, but in brand consistency. A company that handles your promotional merchandise, your website, and your social media from one platform produces a more coherent brand presence than three separate vendors working independently.
The grand opening is Friday, May 22, 2026, from 4:30 to 7:00 p.m. at 124 N. 2nd St., Suite A in Shelton. The event is free; RSVP at onestopnw.com. This is a genuine opportunity to meet the team, tour the showroom, and assess whether the full-service model fits your operation — before committing to anything.
OneStop Northwest is a member of the Shelton-Mason County Chamber of Commerce. The company has operated for more than 20 years out of Union; the Shelton showroom is its first visible, central county address.
The SR-3 Port Investment: What It Means for the North Mason Business Environment
North Mason County — Belfair, Allyn, Grapeview — has seen steady residential growth without proportional commercial development. The Port of Allyn and Port of Grapeview are now exploring a joint purchase that could start to change that equation.
The property in question is a $2 million commercial and light industrial site on SR-3 near East Harding Hill Road. It has existing tenants, some vacancy, and room for future expansion. Port of Allyn Executive Director Travis Merrill has estimated that after expenses, each district could earn $15,000 to $18,000 per year from the property.
That’s not a transformative number. But the conversation Merrill is having with Port of Grapeview Commissioner Mike Blaisdell is about more than immediate cash flow. Industrial development is a core statutory purpose of Washington port districts — and a jointly owned commercial asset on SR-3 could eventually attract the kind of anchor tenants that support a broader business ecosystem in the corridor.
For business owners already located in north Mason County, or considering it, the SR-3 discussion is worth following. Port of Allyn and Port of Grapeview both hold regular public meetings open to the community. The commissioners agreed to schedule a site visit before making any purchase decision.
Frequently Asked Questions
What services does OneStop Northwest offer small businesses in Mason County?
OneStop Northwest provides promotional products and branded apparel, commercial printing, custom company stores, website development, SEO and social media marketing, digital marketing, IT support, payroll automation, and government contracting for internet and phone services. The company positions itself as a one-stop vendor for businesses that currently manage multiple service providers.
How do I connect with OneStop Northwest before the grand opening?
Visit onestopnw.com or find the company through the Shelton-Mason County Chamber of Commerce member directory. The grand opening RSVP is also at onestopnw.com. The event on May 22 is a free, public celebration with tours, introductions to the team, and prizes.
What is the SR-3 property the north Mason ports are considering?
It is a commercial and light industrial property on State Route 3 near East Harding Hill Road in the Allyn area, assessed at approximately $2 million. The Port of Allyn and Port of Grapeview are researching a joint purchase to generate rental income and support future industrial development in the corridor.
Why does the SR-3 deal matter for north Mason County businesses?
Port districts in Washington state have a statutory mandate for economic development, including industrial uses. If the Port of Allyn and Port of Grapeview complete a joint acquisition of the SR-3 site, it could anchor commercial and light industrial activity in the Allyn-Grapeview corridor — an area that has lagged in commercial development relative to residential growth.
How can Mason County business owners stay informed about the SR-3 port project?
Attend public meetings held by both the Port of Allyn and the Port of Grapeview. Both are publicly noticed in advance. The commissioners agreed to visit the property and report back to their respective boards before proceeding with any purchase.
Mason County’s economic picture this spring runs from downtown Shelton to the shores of Hood Canal. A minority-owned branding and marketing firm is opening its first showroom in the county seat, and two north Mason port districts are exploring a $2 million joint investment on State Route 3 that could anchor commercial activity in the Allyn-Grapeview corridor for decades.
OneStop Northwest Opens Downtown Shelton Showroom — Grand Opening May 22
OneStop Northwest LLC, a Union-based company with more than 20 years in business, hosts its grand opening celebration at 124 N. 2nd St., Suite A in Shelton on Friday, May 22, 2026, from 4:30 to 7:00 p.m. The event is free to attend, with tours of the new showroom, a ribbon-cutting ceremony, introductions to the team, light refreshments, and prize giveaways. Attendees are asked to RSVP in advance at onestopnw.com.
The company positions itself as a “360° Brand Management” partner for businesses across Mason County. That means a single vendor for promotional products and branded apparel, commercial printing, custom company stores, website development, SEO and social media marketing, digital marketing, IT support, payroll automation, and government contracting for internet and phone services. For a small business juggling multiple vendors for these functions, that consolidation has real operational value.
OneStop Northwest is a member of the Shelton-Mason County Chamber of Commerce. The new downtown Shelton address — visible and central in the county seat — marks a meaningful step out from its Union roots and into the county’s commercial center. Businesses in Shelton, Belfair, Allyn, Hoodsport, Matlock, and any community in Mason County now have a local resource for professional branding and business technology without leaving the county.
Ports of Allyn and Grapeview Eye $2 Million SR-3 Property Together
Forty miles north and east of downtown Shelton, on State Route 3 near East Harding Hill Road, a commercial and light industrial property is drawing interest from two of north Mason County’s smallest public agencies. Port of Allyn Executive Director Travis Merrill raised the opportunity with Port of Grapeview Commissioner Mike Blaisdell, and at the Port of Grapeview’s April regular meeting, commissioners agreed the property warranted a closer look.
The property carries an assessed value of approximately $2 million. Built by a family from Stretch Island, it has a history of commercial and light industrial use. Currently some of the building is occupied by tenants; part of it sits vacant with room for future expansion.
The financial case is modest but meaningful for small ports. Merrill estimated that after expenses, each port district could earn $15,000 to $18,000 per year from the property through leasing and rental income.
“That alone is something that puts us on better footing,” Merrill said.
Port of Grapeview Commissioner Doug Jones acknowledged the price tag is significant but agreed it was worth a site visit. “It’s something we should at least talk about,” Jones said. Port of Grapeview Managing Official Amanda Montgomery agreed to research how other port districts have structured shared asset ownership arrangements.
Merrill was candid about why the search for new revenue matters. “There is no way that either of our ports, or even any of the ports in Mason County except the Port of Shelton, is going to be able to weather the storm that seems to be coming without some sort of financial assets,” he said during the April meeting.
The Port of Allyn came into 2026 on solid footing by other measures — receiving a clean state accountability audit with no findings, and recouping $99,731 in full from Washington State’s DNR Derelict Vessels Program after removing the sunken vessel Sea Bear from Hood Canal waters.
The SR-3 site represents something bigger than a balance sheet line. Industrial development is part of any port district’s core statutory purpose under Washington state law, and a jointly owned commercial asset on SR-3 could anchor the kind of business activity in the Allyn-Grapeview corridor that has been slow to materialize even as residential growth in north Mason County has accelerated.
What This Means for Mason County
Both stories, at opposite ends of the county, represent the same underlying trend: local economic actors are investing in infrastructure — showrooms, shared assets, consolidated services — rather than waiting for outside capital to arrive.
Mason County’s small ports and small businesses face genuine financial headwinds, from inflation to limited revenue streams to the rising cost of insurance and operations. Moves like the OneStop showroom and the SR-3 property discussion reflect a community building its own commercial depth.
For residents in downtown Shelton, the OneStop Northwest grand opening on May 22 is a free community event worth attending. For residents in the Allyn-Grapeview corridor, the Port of Allyn and Port of Grapeview hold regular public meetings open to the community — the SR-3 decision process will play out in those rooms over the coming months.
Frequently Asked Questions
When is the OneStop Northwest grand opening in Shelton?
The grand opening celebration is Friday, May 22, 2026, from 4:30 to 7:00 p.m. at 124 N. 2nd St., Suite A in Shelton. Admission is free; RSVP at onestopnw.com.
What services does OneStop Northwest offer Mason County businesses?
OneStop Northwest offers promotional products and branded apparel, commercial printing, custom company stores, website development, SEO and social media marketing, digital marketing, IT support, payroll automation, and government contracting for internet and phone services — all under one roof.
What is the SR-3 property the Port of Allyn and Port of Grapeview are exploring?
It is a commercial and light industrial property on State Route 3 near East Harding Hill Road in north Mason County, assessed at approximately $2 million. The two port districts are researching a joint purchase that could generate $15,000 to $18,000 per port per year in rental income.
Why are small Mason County port districts looking for new revenue sources?
Port of Allyn Executive Director Travis Merrill cited financial pressures facing small public ports — including inflation, limited revenue streams, and rising costs — that make diversified income sources increasingly necessary. The Port of Allyn received a clean 2026 state audit and recouped $99,731 from the DNR Derelict Vessels Program earlier this year.
When can I learn more about the SR-3 port project?
Both the Port of Allyn and the Port of Grapeview hold regular public meetings open to Mason County residents. The commissioners agreed to schedule a site visit to the SR-3 property before making any purchase decisions. Watch for agenda items at both ports’ regular meetings.
Is OneStop Northwest a local Mason County company?
Yes. OneStop Northwest LLC is based in Union, Washington, in Mason County, and is a member of the Shelton-Mason County Chamber of Commerce. The company has operated for more than 20 years and the new Shelton location is its first downtown showroom.
Mason County’s business landscape is seeing fresh momentum this spring, with a downtown Shelton showroom grand opening on the south end of the county and two north Mason port districts joining forces to explore a significant commercial real estate investment — developments that reflect the county’s broad economic ambitions stretching from Shelton’s main street to the shores of Hood Canal.
OneStop Northwest Opens Downtown Shelton Showroom — Grand Opening May 22
A Mason County-rooted business is expanding its footprint with a brand-new showroom in downtown Shelton, and the ribbon-cutting is just weeks away. OneStop Northwest LLC — a minority-owned company based in Union, Washington, with more than 20 years of industry experience — will host a grand opening celebration on Friday, May 22, 2026, from 4:30 to 7:00 p.m. at 124 N. 2nd St., Suite A in Shelton.
The event is free to attend, though attendees are asked to RSVP in advance. The evening will feature a ribbon-cutting ceremony, tours of the new showroom space, an opportunity to meet the team, light refreshments, and prize giveaways.
OneStop Northwest describes itself as a “360° Brand Management” partner, offering a wide menu of services under one roof: promotional products and branded apparel, commercial printing, custom company stores, website development, SEO and social media marketing, digital marketing, IT support, payroll automation, and government contracting for internet and phone services. The company serves organizations ranging from small local businesses to larger operations seeking integrated branding and technology solutions.
The company is a member of the Shelton-Mason County Chamber of Commerce, and the new downtown Shelton location marks a meaningful expansion from its Union-area roots — bringing its full lineup of services to a visible, central address accessible to businesses across the county. For organizations in Shelton, Belfair, Allyn, Hoodsport, Matlock, or any community in Mason County looking to elevate their brand presence or streamline business operations, the new showroom offers a genuine one-stop resource right in the county seat.
Founder and team information will be featured at the grand opening event. Attendees can explore the full range of services, including the company’s branded merchandise catalog and print shop, which operates under the onestopnw.com umbrella alongside digital and IT service lines. The expansion into a dedicated Shelton showroom signals confidence in Mason County’s small business community and a recognition that local businesses increasingly want professional marketing and branding support without having to go outside the county.
To RSVP or learn more, visit onestopnw.com or find OneStop Northwest LLC on the Shelton-Mason County Chamber of Commerce member directory.
Ports of Allyn and Grapeview Explore $2 Million Commercial Investment on SR-3
In north Mason County, two small port districts are taking a serious look at a commercial and light industrial property on state Route 3 near East Harding Hill Road — a potential joint investment that could reshape how both the Port of Allyn and the Port of Grapeview generate revenue for years to come.
Port of Allyn Executive Director Travis Merrill brought the opportunity to Port of Grapeview Commissioner Mike Blaisdell’s attention, and at the Port of Grapeview’s April regular meeting, commissioners agreed to set up a visit to the property. The site carries an assessed value of approximately $2 million.
“It may present an opportunity for revenue generation through leasing or rental space as well as longer term potential for industrial development,” Blaisdell told fellow commissioners. The property has a history of commercial and light industrial use, according to Merrill, and was built by a family from Stretch Island. The building currently has some tenants, though part of it is vacant, and there is potential for future expansion on the site.
The financial case is straightforward but meaningful for small public ports. Merrill estimated that, after expenses, each port could earn $15,000 to $18,000 per year from the property. For two port districts with limited revenue streams, that kind of steady return matters.
“That alone is something that puts us on better footing,” Merrill said.
Port of Grapeview Commissioner Doug Jones, who also spoke with Merrill about the property, agreed it was worth a closer look. “It’s something we should at least talk about,” Jones said, acknowledging the $2 million price tag is “a significant amount of money.”
Merrill was candid about the urgency behind finding new revenue sources for small ports. “There is no way that either of our ports, or even any of the ports in Mason County except the Port of Shelton, is going to be able to weather the storm that seems to be coming without some sort of financial assets,” he said during the April meeting.
Blaisdell and fellow commissioners agreed to research models for shared asset ownership between port districts and schedule an in-person visit to the SR-3 property before making any decisions. Merrill noted the idea of two port districts sharing an asset isn’t unprecedented — “ports have previously worked together in many frames and fashions,” he said — and Port of Grapeview’s Managing Official Amanda Montgomery confirmed she would explore how other port districts have handled similar arrangements.
For north Mason County residents, the property discussion carries implications beyond dollars-per-year returns. Industrial development is part of any port district’s core statutory purpose, and a joint commercial asset on SR-3 could anchor future business activity in the Allyn-Grapeview corridor — one of the county’s quieter economic zones that has seen steady residential growth without proportional commercial development.
What to Watch
Mason County residents can mark their calendars for the OneStop Northwest grand opening on Friday, May 22 at 124 N. 2nd St., Suite A in Shelton — RSVP at onestopnw.com. On the north end of the county, watch for updates from the Port of Allyn and Port of Grapeview as the two districts schedule their site visit to the SR-3 property and report back at future public meetings. Both the Port of Allyn and Port of Grapeview hold regular public meetings open to Mason County residents.
Quick answer: On Boeing’s April 22, 2026 Q1 earnings call, CEO Kelly Ortberg reaffirmed full-year free cash flow guidance of $1 billion to $3 billion and said the company is on track for the upper end of that range. Reaching the upper end depends on Boeing Commercial Airplanes ramping 737 production from a stabilized 42 per month today to 47 per month this summer, and ultimately to 52 per month — a rate Boeing has said publicly cannot be reached without activating the new 737 North Line in Everett. Q1 itself was a $1.5 billion free cash flow usage, in line with seasonal first-quarter patterns and ahead of Boeing’s own prior guidance.
Why this matters specifically to Everett
Most Boeing financial coverage skips the geography. The Q1 numbers are reported as a corporate aggregate — $22.2 billion in revenue, all three segments growing simultaneously, free cash flow recovery from the wiring rework. But the production math the company is committing to publicly only works if a specific factory in Snohomish County starts producing 737 MAX jets at a meaningful rate before the end of 2026.
That factory is the 737 North Line, the second 737 final assembly line Boeing is standing up inside the Everett widebody factory — the same building that has historically built the 747, 767, 777, and 787. The North Line is not adding factory floor; it is repurposing capacity inside the existing building. And it is the structural piece that turns 47 jets per month (Renton’s current ceiling under the FAA cap, raising to 47 this summer) into 52 jets per month at the company level.
The Q1 2026 numbers, in context
According to Boeing’s April 22, 2026 first-quarter results release and the earnings call transcript:
Revenue: $22.2 billion, with growth across all three segments (Commercial Airplanes, Defense Space & Security, and Global Services).
Q1 free cash flow: A usage of approximately $1.5 billion, reflecting seasonal corporate expenditures and planned capital spending tied to growth investments at other Boeing sites. Ortberg called the cash result “notably better” than the company had communicated the prior month.
737 deliveries momentum: 143 commercial deliveries in the quarter as 737 production ramps toward 47.
Full-year FCF guidance: Reaffirmed at $1 billion to $3 billion. CEO targets the upper end.
The production rate ladder
Boeing has been explicit on three rate steps:
42 per month — today. Boeing Commercial Airplanes has been producing at this stabilized rate since the FAA-imposed cap that followed the January 2024 Alaska Airlines door plug incident.
47 per month — this summer. Ortberg told analysts this rate moves up at Renton this summer.
52 per month — enabled by Everett’s North Line. Boeing has said publicly that the move to 52 per month is enabled by activating the 737 North Line in Everett. The North Line will start later this year at a low initial rate to demonstrate conformity to the FAA under Boeing’s current production certificate, then ramp “when the entire production system is ready.”
Translation: every dollar of incremental free cash flow above the $1 billion floor depends on rate progression. Every meaningful jump in the rate ladder above 47 per month depends on a building in Everett.
How free cash flow actually gets generated on a 737
The mechanism Boeing has explained on multiple earnings calls works roughly like this. A 737 takes cash to build — supplier payments, labor, components — starting roughly 12-18 months before delivery. Cash comes back at delivery, when the customer pays the bulk of the contract price. The company is also working through inventory of jets built during the prior production pause, which converts into cash as those jets are delivered without requiring new build expense.
That is why production rate matters disproportionately for free cash flow rather than just revenue. Each additional jet delivered at a stable cost structure converts more directly to cash than the revenue line might suggest. The Everett North Line’s contribution to free cash flow shows up about 12-18 months after it produces its first jets at meaningful rate — which means the upper end of 2026 guidance is partially priced on Renton hitting 47 cleanly, while the second-half-2027 free cash flow run rate is what gets unlocked by Everett.
Snohomish County’s stake in this number
Boeing is the largest private employer in Snohomish County. The Everett factory is the largest building in the world by volume. Adding the 737 North Line to that footprint does not require a new building permit, but it does require staffing, training, supplier coordination, and what Boeing has called “production system readiness” across the wider Puget Sound aerospace ecosystem.
The free cash flow target is the public-facing number that Wall Street tracks. The signal it sends to Everett is operational: ramp the North Line successfully and the city’s aerospace economy gets a structurally larger production base for the first time since the 787 program. Miss the ramp and the upper end of 2026 guidance slips, which puts pressure on capital spending and hiring decisions at every Boeing site — Everett included.
What changes between now and the end of 2026
Three milestones to watch from Everett’s vantage point. First, Renton hitting 47 per month this summer — the company has framed this as the precondition for the second-half cash inflection. Second, the North Line achieving its initial low-rate production demonstration to FAA standards under the existing production certificate. Third, the rate increase “when the entire production system is ready” — which is the language Ortberg used and is meaningfully softer than committing to 52 per month by a date.
The Q2 earnings call in late July will be the next public update on whether Renton is at 47 yet and whether the North Line schedule still tracks to the year. That call is the next inflection point for the city’s most consequential employer.
Frequently asked questions
What is Boeing’s 2026 free cash flow guidance?
Boeing reaffirmed full-year 2026 free cash flow guidance of $1 billion to $3 billion on its April 22 Q1 earnings call. CEO Kelly Ortberg said the company is on track for the upper end of that range.
What was Boeing’s Q1 2026 free cash flow?
A usage of approximately $1.5 billion, reflecting seasonal first-quarter patterns and capital spending. Ortberg said the cash result was “notably better” than the company had communicated the prior month.
What is Boeing’s 737 production rate today?
Stabilized at 42 per month, with a planned increase to 47 per month this summer at the Renton factory. The next step to 52 per month requires activating the new 737 North Line in Everett.
When will the 737 North Line in Everett start producing?
Boeing has said the North Line will start later in 2026 at a low initial rate to demonstrate conformity to the FAA under the current production certificate, with rate increases to follow when the production system is ready.
How does the 737 North Line affect Boeing’s free cash flow?
Free cash flow scales with delivery rate. The Renton ramp to 47 is what supports the upper end of 2026 guidance. The Everett North Line is what enables the next step to 52 per month and the structurally higher cash run rate that follows in 2027.
Why is Boeing’s Everett factory important for the 737 program?
The 737 North Line is being stood up inside the existing Everett widebody factory — the same building that has historically built the 747, 767, 777, and 787. It is repurposing existing factory capacity to add a second 737 final assembly line that the FAA-capped Renton site cannot itself accommodate.
What’s the next public update on this?
Boeing’s Q2 2026 earnings call in late July, which will provide the next public read on whether Renton is at 47 yet and whether the North Line schedule still tracks to the year.
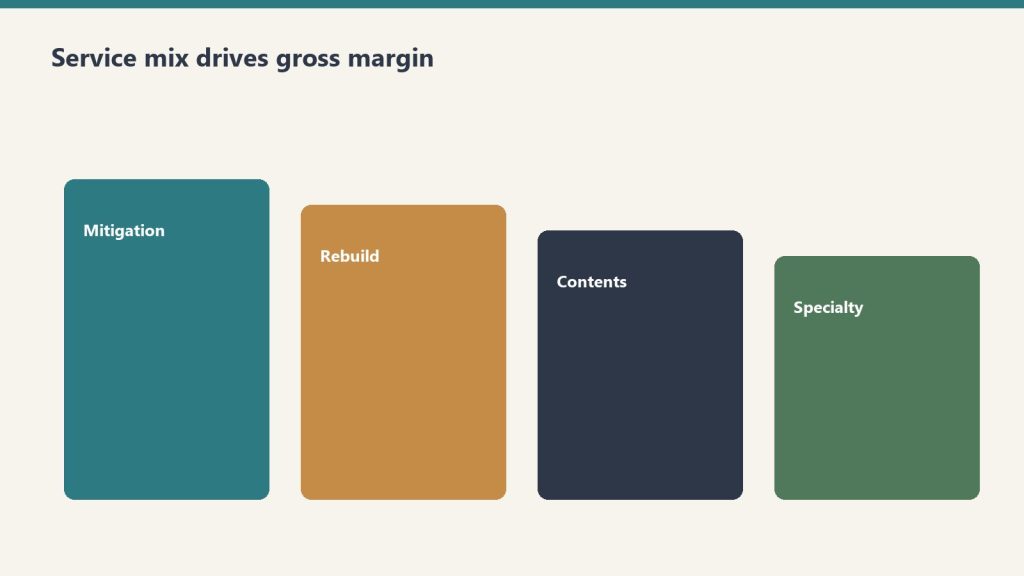
Direct answer: A restoration company’s profitability is determined more by service mix than by total revenue. Industry references consistently show water mitigation gross margins of 70-80%, mold remediation 40-50%, fire damage 25-30% with some references showing 20-25%, and reconstruction commonly cited around 10% with high-capacity volume shops achieving up to 50%. Two shops with the same $5 million revenue and the same operational competence can produce radically different profit dollars depending on whether the mix is mitigation-heavy or reconstruction-heavy. The well-run shop measures gross margin by line, prices each line to absorb appropriate overhead, and chooses mix deliberately rather than letting it drift based on whatever walks through the door.
The previous article in this cluster framed the AR cycle as the foundation discipline. This article frames service mix as the most important strategic decision an operator makes. The decisions are linked — the cycle problem is harder to solve in a reconstruction-heavy mix than in a mitigation-heavy mix, because reconstruction billing cycles are inherently longer and reconstruction margin is inherently thinner. An operator working on both at once will find that fixing service mix actually compounds the AR cycle improvements from the previous article.
The case for thinking carefully about mix starts with arithmetic. Consider two restoration companies, both running $5 million in annual revenue with identical overhead structures, identical labor costs, and identical operational discipline. Company A runs 60 percent water mitigation at 75 percent gross margin and 40 percent reconstruction at 15 percent gross margin. Company B runs 30 percent water mitigation at 75 percent gross margin and 70 percent reconstruction at 15 percent gross margin. Same revenue, same competence — different financial outcomes. Company A produces roughly $2.55 million in gross profit; Company B produces roughly $1.65 million. The mix decision alone costs Company B about $900,000 in gross profit, which after fixed overhead becomes a far larger gap in net profit. The two companies look similar from the street and from the customer-facing pitch. They are not similar businesses.
This is the conversation most restoration owner-operators do not have with themselves. They think of revenue as the goal and mix as whatever happens. They take the work that comes in. The discipline this article describes is to invert that — to treat mix as the deliberate choice and revenue as the consequence of mix multiplied by efficient execution.
What each service line actually pays
Mix shifts margin more than slogans do.
Industry references including Restoration Profits, Kiwi Cashflow’s restoration CFO commentary, the Cost of Doing Business Survey covered by Restoration & Remediation Magazine, and restoration franchise public materials produce a consistent directional picture of gross margin by service line. The numbers vary by region, geography, and company-specific factors, but the relative ordering is robust.
Water mitigation. Gross margin 70-80 percent. The highest-margin line in restoration. The economic engine: equipment does most of the work. Air movers, dehumidifiers, and air scrubbers run on 24-hour cycles with limited human attendance. Xactimate’s mitigation pricing rewards the equipment-heavy model. A typical mitigation job has labor cost around 15-20 percent of revenue, equipment rental or amortization around 5-10 percent, materials and consumables around 2-5 percent, leaving roughly 70-80 percent for overhead absorption and profit. The math works because equipment, once owned, has marginal cost approaching zero per additional job day. Industry coverage from Claims Delegates and others has explicitly described high-margin mitigation strategies as “$1,000 per hour” lines when Xactimate is used correctly.
Mold remediation. Gross margin 40-50 percent. Lower than water mitigation because the labor content is heavier and the protective cost (PPE, containment, disposal) is real. Mold work is also more documentation-intensive, more regulated, and often more disputed by carriers, all of which add cost without proportional revenue. Mitigation-style equipment (HEPA filtration, negative-air, dehumidification) supplements but does not replace skilled hand labor for source removal and structural cleaning. Mold is a real margin line for shops with the capability, but it is not the equipment-leveraged windfall that water mitigation can be.
Fire damage restoration. Gross margin 25-30 percent commonly cited; 20-25 percent in some references. The work is labor-intensive, slow, contents-heavy, and odor-and-soot-management-heavy. Fire jobs are larger and more complex than water jobs, requiring skilled project management and coordination layered on the technical work. The pricing in Xactimate supports the work but does not provide the equipment-leverage that water enjoys. Fire-damage restoration is good revenue at honest margin, but it does not produce the windfall margin that an underloaded mitigation crew can produce on the right water job.
Reconstruction. Gross margin 10-20 percent in typical operator references; up to 50 percent for high-volume operators per Cleanfax-published commentary on the most efficient operators. The wide range reflects two different business models. The standard model treats reconstruction as a service line layered onto the restoration relationship — the restoration company handles the rebuild because the customer is already in their hands, but margins are construction-industry margins (10-15 percent) plus general overhead absorption. The high-volume model treats reconstruction as a primary business with restoration relationships as the customer acquisition channel — these shops have invested in subcontractor management, project management depth, scheduling systems, and supplier relationships that allow them to run reconstruction at 30-50 percent gross margin through volume efficiency and subcontractor leverage. Most owner-operator restoration shops run reconstruction in the 10-20 percent range. A few have built the operational discipline to run it higher.
Contents cleanup. Gross margin around 50-65 percent for shops with capability. Per the same Cleanfax operator commentary, high-capacity contents shops achieve 65 percent gross margin on cleaning and around 50 percent on packouts when subcontractor pricing is doubled into invoiced cost. Contents work is real margin for shops that specialize, more variable for shops that treat it as ancillary to structure work. This line has the largest gap between specialist operators and generalist operators.
Specialty services. Gross margin variable but often strong on coordination revenue. As covered in the specialty restoration cluster, specialty work performed through a vetted subcontractor bench produces coordination revenue at high effective margin (the coordination fee is high-margin because the direct work cost is the specialist’s, not the restoration company’s). Specialty work performed in-house by the restoration company is rare and is its own business model.
Biohazard, trauma, and crime scene cleanup. Gross margin commonly cited 40-60 percent for trained operators with appropriate licenses. This is a smaller volume, higher-emotional-stakes line that pays at a premium because few operators are equipped or willing to do it. Operators who specialize here can run profitable practices at relatively low total revenue.
The overhead absorption problem
Pure gross margin numbers do not tell the full story because each service line absorbs a different proportional share of fixed overhead. A shop that runs at $5 million revenue with $1.5 million in fixed overhead (rent, salaried staff, fleet, equipment depreciation, insurance, software, marketing) has to allocate that overhead across the work it produces.
The well-run shop allocates overhead to service lines based on the share of resources each line consumes, not based on revenue share. A reconstruction job uses substantially more project-management time, more office support, more procurement effort, and more accounting time per revenue dollar than a water mitigation job. If overhead is allocated by revenue share, reconstruction looks more profitable than it actually is and mitigation looks less profitable than it actually is.
The accounting fix is service-line P&L with deliberately allocated overhead. The shop sets up its accounting to track direct cost (labor, materials, equipment, subs) by service line, then allocates fixed overhead using a cost-driver methodology — project-management time, billing time, office support time, fleet usage — that reflects actual consumption. The result is service-line contribution margin that shows what each line is actually earning after overhead absorption, not just what it earns before overhead.
Most restoration shops do not run this analysis. Most operators are surprised by the answer when they do. Reconstruction often emerges as a marginal contributor or actual loser after appropriate overhead allocation, even when its gross margin looks acceptable. Water mitigation often emerges as a much larger contributor than its revenue share suggests. The strategic implications follow from the analysis — and they are usually different from what the gut-feel running of the business produced.
How mix actually shifts in the day-to-day operation
Day-to-day mix shifts are decisions — not accidents.
Mix is not chosen in a strategy session. It shifts based on a series of small decisions made across the operation, often without anyone realizing they are shifting mix.
Marketing channels favor specific lines. Google Ads bids on emergency water keywords drive water mitigation calls. Roofer partnerships drive storm-damage reconstruction. Insurance preferred-vendor program leads come in line-mix patterns specific to each program. The marketing decisions made in the prior cluster (Marketing Stack on Tygart Media) directly shape mix.
Sales scripts favor specific lines. The way the call-taker scopes the conversation, the way the on-site rep frames the work, and the way the project manager presents options to the customer all subtly steer the work mix. A shop whose sales conversation centers on “let us handle everything” tends to capture more reconstruction. A shop whose sales conversation centers on “we are the mitigation specialist” tends to keep more focused mix.
Staffing tilts the mix. A shop that has hired heavily on reconstruction project managers will sell more reconstruction because that is what the team is configured to deliver. A shop with deep mitigation lead techs and a thin reconstruction PM bench will lean toward mitigation. The org structure and the work mix shape each other.
Carrier program enrollments drive specific line mixes. Some carrier programs are mitigation-heavy, others are reconstruction-heavy, others are biohazard-and-emergency-response-heavy. The shop’s program portfolio shapes its inbound mix more than most operators recognize.
Customer relationship behaviors drive mix. A shop that subcontracts reconstruction to trade partners on relationship terms (offering them the rebuild work in exchange for emergency referral flow) keeps mitigation margin while passing through reconstruction. A shop that holds reconstruction in-house captures both lines but absorbs both margin profiles.
Recognizing that mix is the cumulative result of these small decisions is the first step. Choosing to make those decisions deliberately is the second.
Strategic mix archetypes
Most well-run shops fall into one of four mix archetypes, each with its own logic and its own trade-offs.
Mitigation specialist. Mix heavily weighted toward water mitigation and mold remediation, with reconstruction passed through to trade partners or refused entirely. Highest gross margin profile of the four archetypes; smallest revenue per claim; highest claim volume requirement to hit a given revenue target. This model works well in metro markets with high water-loss frequency and a reliable network of reconstruction partners. The trade-off is that the specialist sees a smaller share of total restoration spend per claim — the rebuild work and the contents work go to others — and the customer relationship is shorter.
Full-service generalist. Mix balanced across mitigation, reconstruction, and contents. Most common archetype in mid-size independent shops. Captures the full claim economically but at blended margin that includes the lower reconstruction line. Works in most geographies. Trade-offs: requires operational depth across multiple service lines, requires management depth to run reconstruction at acceptable margin, and tends to produce lower overall gross margin than the specialist model.
Specialty commercial wedge. Mix weighted toward commercial accounts with specialty recovery components (documents, electronics, art, medical equipment) plus the general mitigation and reconstruction those accounts produce. The model described in the previous specialty restoration cluster. Higher revenue per relationship, higher complexity, higher operational bar. Trade-offs: longer sales cycles, regulatory and compliance overhead, and dependency on a smaller number of larger accounts.
High-volume reconstruction operator. Mix weighted toward reconstruction at scale, with mitigation as a feeder. Less common as a deliberate strategy but possible — these are the operators who have built reconstruction operational discipline equivalent to a homebuilder or commercial GC and who run reconstruction at 30-50 percent gross margin. The Cleanfax-cited high-capacity volume shops fall in this archetype. Trade-offs: requires substantial management investment in reconstruction operations, exposes the business to construction-cycle dynamics, and runs into the long-cycle AR problem from the prior article harder than the mitigation-led models.
The choice of archetype is not permanent. Many shops evolve from one to another as they grow, change ownership, or respond to market shifts. The point is to choose deliberately, build the operations to support the chosen archetype, and resist drift back to whatever-walks-through-the-door because that drift is what produces undisciplined service mix and the lower margins that follow.
Pricing each line to absorb appropriate overhead
The 10-and-10 myth — that restoration contractors should bill 10 percent overhead and 10 percent profit on top of direct costs as the standard markup — is one of the most damaging conventions in the industry. Industry coverage from Restoration & Remediation Magazine has covered this extensively under the “10 and 10 myth” framing. The math simply does not work. A shop with $5 million in revenue and $1.5 million in fixed overhead is running at 30 percent overhead, not 10 percent. Pricing at 10-and-10 means the shop is losing money on every job and making it up only when extreme volume covers the gap.
The disciplined alternative is to know the shop’s actual overhead rate as a percentage of direct cost and to price each service line with a markup that absorbs an appropriate share. For a shop with 30 percent overhead, the minimum markup over direct cost is roughly 50 percent (which produces gross margin around 33 percent — exactly the breakeven before profit). For acceptable profit, markup of 75-100 percent over direct cost is more common. The Xactimate price list, when used correctly, supports this markup level on most service lines. The shop’s price list and Xactimate practice should reflect the true overhead structure and the target profit margin, not industry conventions that are decades out of date.
The pricing decision differs by service line. Water mitigation can support high markup because the equipment-heavy model produces low direct cost, leaving room. Reconstruction is harder to mark up because direct cost is dominated by subcontractor and material cost, both of which are visible to customers and adjusters. The well-run shop applies different markup logic to different lines and matches its pricing to its actual cost structure rather than to a uniform convention.
For shops that are uncertain whether their pricing is right, the diagnostic is simple. Pull twelve months of P&L. Compute gross margin by line. Compute fixed overhead as a percentage of revenue. Compute net margin. If net margin is below 8-10 percent, pricing or mix is wrong. If gross margin on water mitigation is below 70 percent, Xactimate practice is the likely culprit. If gross margin on reconstruction is positive at any level, the shop is doing better than many; the question is whether the reconstruction is absorbing its appropriate share of overhead. The numbers reveal the problem; the operator’s job is to diagnose specifically and intervene at the right point.
What to refuse
What to refuse is a margin decision wearing a values jacket.
The hardest discipline in service mix is refusing work that does not fit. Most restoration owner-operators struggle with this because every job feels like revenue and revenue feels like progress. But work that runs below contribution margin (revenue minus direct cost minus appropriate overhead allocation) actually subtracts from the business — every dollar of bad-fit revenue requires the next dollar of good-fit revenue to make up the loss.
Specific patterns of work that the disciplined shop is willing to refuse:
Reconstruction at price points that require the shop to break its actual cost structure. Customers and adjusters who insist on 10-and-10 markup on reconstruction are asking the shop to lose money on the rebuild. The discipline is to either decline or to pass the rebuild to a trade partner who can do it at the contemplated price.
Out-of-area work that requires excessive mobilization. The labor and equipment cost of crews working far from base eats margin in ways the customer does not see. A shop with capacity issues during a CAT event can sometimes justify out-of-area work at higher pricing, but routine out-of-area work at standard pricing is usually a margin loser.
Carrier programs whose pricing structure does not fit the shop’s cost structure. Some preferred-vendor programs price meaningfully below market with the expectation of volume making up for unit margin. Whether this trade is worth taking is operator-specific, but the shop that signs into every program offered without doing the math is signing into structural losses.
Customer relationships that consume management time at scale. Some customers and adjusters require an hour of phone time and three documentation revisions for every invoice. The shop’s project management cost on these accounts often exceeds the gross profit. The discipline is to identify these accounts and either reset the relationship or end it.
Work the shop does not have the operational depth to deliver well. Taking a fire job when the shop has no fire-experienced lead tech, or a commercial loss when the shop has no commercial PM, is taking work the shop will execute poorly and damage its reputation on. The work feels like revenue; the reputation cost compounds against future revenue.
The operator who can decline bad-fit work calmly and confidently is operating from financial clarity. The operator who cannot is operating from fear that the next call may not come. The financial clarity is what comes from running this analysis and knowing the numbers cold.
How this article fits the cluster
Mix is the second foundation decision after AR cycle. With both in place, the rest of the cluster has solid ground to stand on. The next article — equipment economics — depends on understanding mix because equipment ROI is line-specific (water mitigation equipment has different utilization economics than reconstruction equipment). The crew structure and KPI dashboard articles that follow build on both foundation decisions.
If the prior article (AR cycle) is the highest-leverage operational improvement most restoration shops can make, this article (service-line mix) is the highest-leverage strategic improvement. They are different kinds of work — AR is a tactical, weekly operating discipline; mix is a quarterly and annual strategic discipline — but both produce outsized returns relative to the effort required.
Should I be running service-line P&L if my accounting system doesn’t support it natively?
Yes, with manual allocation if necessary. The first version can be a quarterly spreadsheet exercise — pull total revenue, total direct cost, and total overhead from the financial statements, then estimate the mix and the line-specific direct cost ratios. The numbers are imprecise but directionally accurate, and they will surface the strategic question even before the accounting system is reconfigured. Once you have decided that mix matters, invest in setting up the accounting to produce the analysis automatically.
Why is reconstruction so much harder to make money on?
Three structural reasons. First, the work is dominated by labor and materials, both of which are heavily benchmarked by competitors and carriers. Second, the cycle is long, so working capital cost is higher. Third, the customer can see the cost of the materials and the visible labor in ways they cannot for mitigation, which makes pricing pressure harder to absorb. The operators who run reconstruction at high margin have invested in subcontractor management, supplier relationships, and project-management efficiency that takes years to build.
Should an owner-operator pursue the high-volume reconstruction archetype?
Probably not as a starting strategy. The high-volume reconstruction model requires substantial management infrastructure that is expensive to build and difficult to maintain. Most owner-operators who try to evolve into this model end up with reconstruction-heavy mix at standard 10-15 percent margin rather than the 30-50 percent the well-built operators achieve. The honest assessment is that this archetype works for a small number of operators who have the construction-management capability, and most owner-operators are better served by mitigation specialist or full-service generalist archetypes.
What is a realistic mix to target if I want to maximize gross profit?
A mix-of-business analysis specific to your geography, capability, and capacity is needed for an actual answer. As a directional reference, mitigation specialists often run 60-75 percent mitigation and mold (combined), 15-25 percent contents and specialty, and 0-15 percent reconstruction (often passed through). Full-service generalists run 35-50 percent mitigation and mold, 15-20 percent contents and specialty, and 30-50 percent reconstruction. The right mix for a specific shop is a function of the local market, the shop’s operational depth, and the owner’s risk tolerance.
Does the specialty restoration wedge from the prior cluster fit into mix strategy?
Yes, directly. Specialty work is a high-coordination-margin add to the mix. The specialty cluster’s commercial-account focus produces relationships that generate mitigation, reconstruction, and specialty revenue together, and the specialty coordination component is high-margin in a way that lifts the blended profile. Operators who have built specialty capability typically see their mix shift toward more mitigation and specialty, less commodity reconstruction.
How often should I revisit the mix question?
At minimum, annually as part of business planning. More frequently if the shop is growing fast, going through ownership changes, expanding geography, or seeing significant changes in carrier program enrollments. A quarterly directional review is good discipline. Monthly is overkill. Weekly is panic.
What if I’m carrying lines I’m bad at because I haven’t done this analysis before?
The disciplined response is to either invest in becoming good at the line (hire, train, partner) or exit the line. Carrying lines you are bad at is carrying work that produces below-average margin and below-average customer experience. It is the worst of both worlds. The annual review process should produce these decisions explicitly.
Are biohazard, trauma scene, and unattended death cleanup really good margin work?
For shops with proper licensing and trained crews, yes. The pricing supports the work and the competitive density is low because most operators do not want the work. The trade-offs are emotional weight on the crew, careful customer-facing communication, and licensing and disposal compliance overhead. For shops with the right operational fit, this is a legitimate niche.
What’s the relationship between mix and consolidator interest in acquiring my shop?
Consolidators value mix-driven margin profile. A shop with disciplined mitigation-heavy mix at clean margin is a more attractive acquisition target than a shop with the same revenue but lower margin from undifferentiated reconstruction-heavy mix. The mix work this article describes is also exit-positioning work, and operators who run it well over a few years are positioning for a stronger acquisition outcome whether or not they intend to sell.
What is the single move I should make this week from this article?
Pull last quarter’s P&L, estimate revenue and direct cost by service line, compute the implied gross margin per line, and compare to the industry directional ranges in this article. If your mitigation gross margin is below 70 percent, your reconstruction gross margin is below 10 percent, or your overall mix is reconstruction-heavy without operational depth supporting it, the analysis has identified the largest profitability lever in your business. Treat the answer as the agenda for the next quarter.
Direct answer: A restoration company’s profit and loss statement and its bank account tell two different stories, and the gap between them is the AR cycle. Industry data references show construction-sector DSO averaging around 83 days — the highest of any major industry — and restoration claim cycles stretching well beyond 60-90 days are common. The well-run shop measures days sales outstanding by carrier, by service line, and by job size, builds working capital reserves sized to the actual aging profile rather than the optimistic version, and runs documentation discipline that removes the most common reasons adjusters delay payment. Compressing days-to-cash from 90+ down to a defensible 45-60 is worth more to most restoration companies than a 5-point margin improvement, because it directly funds growth without external capital.
The single most common silent killer of growing restoration companies is not bad work, bad marketing, or bad people. It is the gap between when the cash goes out and when the cash comes in. A restoration company growing at 30 percent per year is, by definition, funding 30 percent more labor, more equipment, more materials, and more subcontractor invoices than the previous year — out of working capital that has not yet been replenished by the carrier checks for last quarter’s work. The math compounds. Every additional dollar of revenue requires roughly the same proportional dollar of working capital. A growth rate that exceeds the working-capital cycle eventually exhausts the bank account, even while the P&L looks healthy and the owner cannot understand why payroll is suddenly hard to make.
The first move toward fixing this is recognizing that the AR cycle is not a back-office annoyance. It is the central operational metric of the restoration business model. Operators who understand and manage it correctly run growing companies without external capital. Operators who do not understand it either grow slower than their market opportunity allows or take on debt they do not need to take on. The well-run shop treats AR cycle as a strategic discipline.
This article is the first cluster piece in the finance and operations stack and is the one most operators should attack first. The rest of the cluster builds on the assumption that the AR cycle is under control. Without it, the other improvements in service mix, equipment economics, crew structure, and KPI hygiene cannot compound.
Instant Operational Field Downloads
Fix Your Restoration Cash Cycle & Compress Days-to-Cash
First-clean submission checklists, 5–14 day adjuster delay preventers, 3-way DSO slicing worksheets, and AI-run claim audit routines built directly from this guide.
Field Quick CardFREE
Xactimate-to-Cash Quick Card
2-page field card: the cycle on one card — Day 0–180 timeline at a glance, why single DSO fails, 3-way slicing matrix, and operator-controllable vs external delay levers.
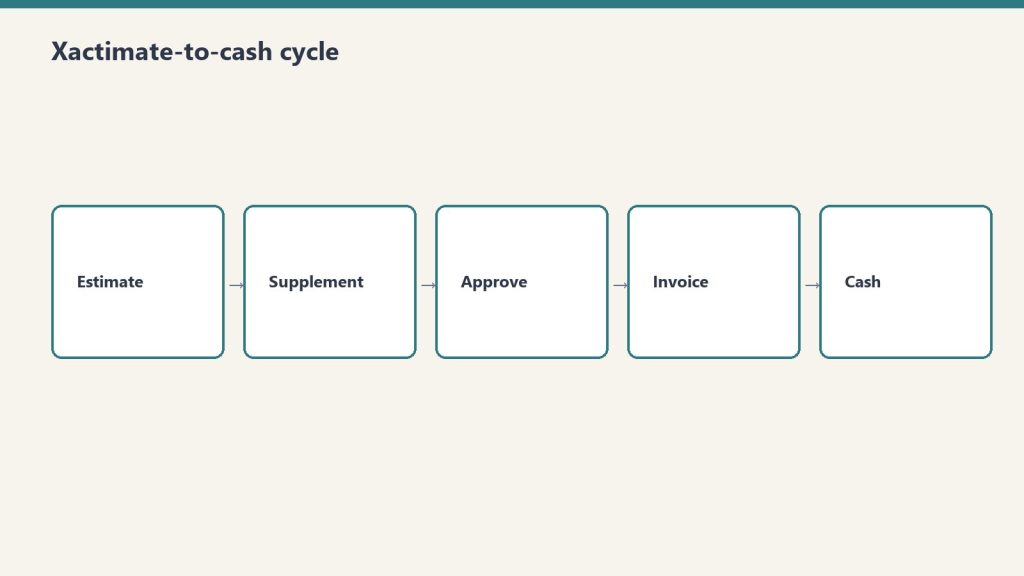
What the Xactimate-to-cash cycle actually looks like
What the Xactimate-to-cash cycle actually looks like.
The Xactimate-to-cash cycle has more steps than most operators map out. Each step is a place where days accumulate. The full sequence on a typical commercial or residential insurance claim:
Loss event and dispatch. Day zero. Restoration company arrives, performs emergency mitigation, begins documentation.
Mitigation completion. Days three to seven on a typical water loss. Drying complete, dry standards verified, mitigation invoice ready to assemble.
Mitigation invoice submission. Days seven to fourteen. Restoration company assembles the mitigation invoice — Xactimate estimate, photos, moisture logs, daily reports, work authorization, certificate of completion — and submits to the adjuster.
Adjuster review and approval. Days fourteen to thirty-five. Adjuster reviews the submission, may request additional documentation, may negotiate scope or pricing, eventually approves the invoice in whole or in part. Independent industry references from restoration billing services note that documentation gaps are the most common reason adjusters extend this window — missing photos, incomplete moisture logs, inconsistent line items, or scope items that cannot be supported by the documentation.
Carrier payment processing. Days thirty-five to sixty. Carrier processes the approved invoice and issues payment. For claims involving a mortgaged residential property, the check is typically made out jointly to the policyholder and the contractor, which means the homeowner has to endorse and forward, and lender involvement is required for claims above a threshold (commonly $10,000-$15,000) where mortgage companies release funds in stages.
Reconstruction or repair phase. Begins after mitigation phase. The reconstruction scope is developed, approved, and executed. The cycle for reconstruction billing repeats — invoice assembly, adjuster review, carrier processing — but on a longer cycle because reconstruction work itself takes longer.
Final invoice and closing. Days ninety to one-hundred-eighty for a fully reconstructed loss. Final scope reconciliation, depreciation holdback recovery on RCV claims, retainage release if applicable.
The aggregated cycle on a typical mid-size residential or commercial loss runs sixty to one-hundred-twenty days from loss to full payment. On larger commercial losses with multiple phases, scope disputes, or coverage issues, it stretches to one-hundred-eighty days or more. On problematic claims with denied items, public adjuster involvement, or litigation, it can stretch into multi-year territory.
For working-capital math, the simple version is that every dollar of revenue requires roughly the proportional dollars of cash held in AR for the average cycle length. A shop with $10 million in annual revenue and a 90-day cash cycle is carrying roughly $2.5 million in average AR — and that AR is funding the labor, equipment, materials, and subcontractor cost the shop is incurring on the next set of jobs. Compress the cycle to 60 days and the shop’s working-capital requirement drops to roughly $1.65 million, freeing $850,000 in cash for growth, debt reduction, equipment investment, or distribution. Compress further to 45 days and the freed cash hits $1.25 million. These are real, recoverable numbers, and they show up in the bank account, not just on the spreadsheet.
Why DSO is the wrong single metric and the right multi-metric
Most restoration companies that measure AR at all measure a single overall DSO number, calculated as accounts receivable divided by total revenue, multiplied by the number of days in the period. This is the standard cross-industry calculation and it produces a useful directional read — but on its own it is not actionable, because the underlying AR is not homogenous. The well-run shop measures DSO three ways simultaneously.
DSO by carrier. The DSO with State Farm is different from the DSO with USAA, which is different from the DSO with Allstate, which is different from the DSO with the local independent commercial carriers. Some carriers pay reliably in 30-45 days; some stretch to 60-90; some stretch beyond 90 routinely. The shop that knows its DSO by carrier can make rational decisions — which programs to lean into, which to pull back from, which to limit exposure on. The shop that knows only its blended DSO is making aggregate decisions on heterogeneous data.
DSO by service line. Mitigation invoices typically pay faster than reconstruction invoices because they are smaller, simpler, and structured to industry-standard mitigation Xactimate line items. Reconstruction invoices pay slower because they involve more scope negotiation and more adjuster review. Specialty work — documents, electronics, art, medical — pays in patterns that depend on the carrier’s familiarity with the specialty pricing and on whether the specialist bills direct or through the prime restoration company. A shop that knows DSO by service line can spot whether the cycle problem lives in mitigation, reconstruction, or specialty.
DSO by job size. Small jobs (under a few thousand dollars) often pay quickly because adjusters approve them with minimal review. Mid-size jobs ($10,000-$50,000) often hit the worst of both worlds — large enough to require full documentation review, small enough to lack the executive attention that moves large losses through the system. Large jobs (over $100,000) often have dedicated adjuster attention, large-loss specialists involved, and faster decision-making once scope is settled, although the cycle from loss to first payment can still be long. A shop that knows DSO by job size can identify the band where the cycle is most painful and target documentation and follow-up effort there.
The combined picture — DSO by carrier, by service line, by job size — is what produces actionable management information. Most restoration companies do not produce this view because their accounting systems are not configured to slice AR this way and their internal reporting effort has been on top-line metrics. Configuring the accounting system to support this slicing is a one-time investment that pays back almost immediately.
What is causing the long cycle, and which causes are operator-controllable
Operator-controllable causes of a long cycle.
The long restoration cycle has multiple causes, and the operator’s intervention point is different for each.
Documentation gaps. Operator-controllable, high impact. Industry references from restoration billing services consistently identify documentation as the single largest cause of payment delays. An invoice missing photos, moisture logs, daily reports, signed work authorizations, or scope justification gives the adjuster a defensible reason to delay payment with a request for more information. Each round trip costs five to fourteen days. A shop that submits complete, clean, defensible documentation on the first submission collects faster than a shop that submits incomplete documentation and chases revisions.
Xactimate scope quality. Operator-controllable, high impact. An Xactimate estimate that uses incorrect line items, that prices outside the standard price list without justification, or that includes scope items not supported by the documentation will be reduced or returned. Real Xactimate proficiency — Level 1 certification at minimum, Level 2 ideal, in-house or contracted — pays for itself on the first half-dozen invoices. Operators who use Xactimate as a glorified word processor without understanding the underlying line-item logic submit estimates that produce avoidable disputes.
Carrier program structure. Partially operator-controllable. Different carrier preferred-vendor programs have different documentation requirements, different review cycles, and different payment-processing timelines. Some require submission through specific portals (Verisk’s claims platforms, Symbility, carrier-specific systems) that produce faster cycles than email-based submission. Some require pre-approval at scope thresholds. The operator’s intervention point is to learn the program’s specifications cold and submit to specification, and to selectively de-prioritize programs whose cycle structure does not work for the shop’s working-capital tolerance.
Mortgage company involvement. Limited operator-controllability. On residential losses where the property is mortgaged, the lender’s check-handling protocol adds a cycle layer the contractor cannot eliminate. The intervention is to communicate the lender process to the homeowner early, provide the documentation the lender will require (final invoices, work completion certificates, lien waivers) ahead of need, and follow up actively rather than passively waiting.
Public adjuster involvement. Mixed operator-controllability. When a PA is on the file, scope is scrutinized harder and disputes take longer. The contractor’s intervention is to maintain documentation discipline strict enough to survive PA scrutiny, communicate professionally with the PA on scope questions, and avoid behaviors that escalate the file unnecessarily.
Coverage disputes. Limited operator-controllability. When the carrier disputes coverage on items the contractor has performed, the cycle stretches indefinitely. The intervention is upfront — confirming coverage on questionable items before performing the work, getting written authorization on scope expansions, and avoiding work the policy clearly does not cover.
Litigation. Not operator-controllable except by avoidance. Once a claim is in litigation, the cycle is governed by the legal process rather than the claims process. The contractor’s defense is to not get into litigation in the first place, which means honest scope, complete documentation, professional communication, and a willingness to walk away from disputes that are not worth litigating.
The pattern in this list: the highest-impact causes are operator-controllable. Documentation discipline and Xactimate scope quality are the two largest levers, and they are entirely within the shop’s control. Operators who blame the long cycle on the carriers without first auditing their own documentation and Xactimate practice are diagnosing the wrong problem.
The operational moves that compress the cycle
Operational moves that compress the AR cycle.
The well-run shop runs a specific set of operational practices that compress the AR cycle. These are not novel and they are not glamorous. They are the practices that produce the difference between a 90-day cycle and a 45-60 day cycle.
Document at the job level, in real time. Not at invoice time. Photos taken on day one, moisture logs updated daily, daily reports completed by the lead tech before leaving site, scope-of-loss documented progressively as the work develops. Documentation assembled at invoice time is documentation that has gaps. Documentation assembled in real time is documentation that is complete on day seven when the mitigation invoice is ready to go out.
Use a documentation platform. Several industry-standard platforms — including CompanyCam for photos, MICA and ENCIRCLE for full documentation packages, and proprietary platforms from larger carriers’ preferred-vendor programs — automate documentation capture. Operators using these platforms submit cleaner invoices and submit them faster than operators relying on phone photos and paper logs.
Build the Xactimate estimate as the work progresses, not after. The mitigation Xactimate estimate should be largely written by the time the drying is finished. The reconstruction Xactimate estimate should be developed during the mitigation phase, not after the customer authorizes the rebuild. Operators who treat Xactimate as a billing-time activity add days to the cycle that the operators who treat it as a project-execution activity do not.
Submit the invoice on a schedule. The shop’s standard should be invoice within seven days of mitigation completion, with no exceptions for shop-side delays. Customers and adjusters pay invoices that arrive promptly faster than they pay invoices that arrive late, partly because the file is fresh and partly because prompt invoicing signals professional operations.
Follow up on a schedule. Adjuster contact at day fourteen post-submission if not approved, day twenty-one with escalation request, day thirty with escalation to the carrier’s claims service line. Adjusters have hundreds of files. The files that get attention are the ones the contractor stays present on. The files that drift are the ones where the contractor submits and waits silently.
Reconcile cash to invoices weekly, not monthly. The accounting team should know which invoices are open, by carrier and by adjuster, every week. Stale aging that is not reviewed is aging that gets older. Weekly review with explicit follow-up assignments produces faster collections than monthly review.
Use a billing service when in-house capacity does not exist. Restoration-industry-specific billing services — companies like Restoration Insurance Billing, Blackwater Billing Services, NetClaimsNow, and others — exist specifically to handle Xactimate invoice assembly, submission, and follow-up. For shops that do not have in-house Xactimate competence or in-house collections discipline, outsourcing this function to a specialist often produces a faster cycle than handling it in-house at the shop’s current capability level. The fee is paid out of the cash-cycle compression.
Submitting an invoice that triggers an adjuster RFI costs 5 to 14 days per revision loop. Arm your lead techs and billing coordinators with print-ready first-time-clean submission QA sheets, line-item scope audits, and AI-driven aging diagnostics.
Compressing the AR cycle reduces but does not eliminate working capital intensity. Even at a defensible 45-60 day cycle, a growing restoration company carries substantial cash in receivables. The well-run shop has a deliberate working capital strategy that funds this intensity without surprises.
Cash reserve sized to the actual aging profile. A shop with a 60-day cycle should carry cash reserves sufficient to operate for at least 60 days at current burn rate, plus a buffer for delayed collections on specific files. Many operators size reserves to 30 days of operating cost, which is too thin for restoration’s cycle. Sizing reserves to 75-90 days of operating cost, with a clear policy on when reserves can be drawn down for growth investment versus when they must be held, gives the shop room to absorb a slow collection month without payroll stress.
Line of credit as a flex tool, not a permanent funding source. Most growing restoration shops should have a working-capital line of credit with a commercial bank, sized to cover one to two months of operating cost. The line is a tool for absorbing month-to-month variation in collections, not a tool for funding ongoing operations. Shops that operate continuously on the line of credit are shops with a structural cash problem they have papered over with debt.
Customer financing as a deliberate tool. On residential reconstruction work where insurance does not cover the full scope, customer financing can be offered through restoration-industry-specific finance partners or general home-improvement finance platforms. This converts a payment-cycle question into a marketing question and shifts the cycle off the shop’s balance sheet.
Avoid AOB-driven cash flow models. Some restoration companies build their cash flow on aggressive use of assignments of benefits, where the carrier pays the contractor directly. AOBs solve the homeowner-endorsement step but do not address the underlying claim cycle, and several states have passed AOB reform that complicates or restricts the practice. Building working capital strategy around AOBs is fragile both legally and operationally.
Factoring as last resort, not first option. Specialty receivables-factoring firms exist that will advance against restoration AR, but the cost is meaningful (often 2-4 percent per month effective rate) and using factoring routinely indicates that the underlying cycle problem has not been fixed. Use factoring only as a bridge while implementing the operational improvements that compress the cycle, not as a permanent solution.
What the AR cycle reveals about the rest of the business
The AR cycle is a diagnostic tool as much as it is an operational metric. Specific patterns in the AR aging report point to specific underlying issues elsewhere in the operation.
Long cycle on a specific carrier. The carrier’s program structure may not fit the shop’s working-capital tolerance, or the shop’s documentation may not fit the carrier’s submission requirements. Either way, this is a focused intervention point.
Long cycle on a specific service line. The Xactimate competence in that service line may be weaker, or the documentation discipline may be looser. Investigate the lead tech and project manager on that service line and compare practice to the better-performing service lines.
Long cycle on a specific job size. Process gaps in the size band — possibly insufficient project-management attention on mid-size jobs or insufficient documentation rigor on small jobs that get treated casually. Address process at the size band rather than the job level.
Long cycle on jobs led by a specific project manager. The PM’s documentation, communication, or follow-up practice may be substandard. Coachable, often quickly.
Spike in cycle in a specific month. Look for upstream issues — was a billing person out, did a software change disrupt invoice generation, did a regulatory change affect a common scope item, did a carrier change its program. The cycle is the downstream symptom of upstream operations.
The shop that uses AR aging as a diagnostic produces continuous improvement. The shop that uses AR aging only as a financial-statement input misses most of the management information the metric carries.
How this article fits the cluster
The AR cycle is the foundation. The next article in the cluster — gross margin by service line — depends on the AR cycle being defensible, because service-line economics that look good on margin but fail on cash conversion are not actually good economics. The articles that follow on equipment economics, crew structure, KPI dashboards, and the rest all assume the operator has working capital under control. An operator who works through the rest of the cluster without first fixing the AR cycle is building on sand.
If you take only one operational improvement from this entire cluster, take this one. The investment is modest — documentation discipline, Xactimate competence, scheduled follow-up, weekly cash review. The return is direct, measurable, and recurring. Compressing days-to-cash from 90 to 60 frees roughly two months of revenue in working capital. For a $5 million shop, that is roughly $830,000 in cash. For a $20 million shop, it is roughly $3.3 million. Those are not theoretical numbers. They are sitting in your AR right now.
Choose Your Restoration Cash-Cycle Compression Tier
Select the operational depth that matches your annual revenue, billing capability, and carrier mix:
Field ReferenceFREE
Quick Card
2-page field card: the complete Xactimate-to-cash timeline map, 3-way slicing matrix, and operator-controllable vs external delay levers on one printable sheet.
What is a realistic DSO target for a restoration company?
For mitigation-heavy work with disciplined operations, 45-60 days is achievable. For mixed mitigation and reconstruction work, 60-75 days is realistic. For reconstruction-heavy work, 75-90 days is realistic. Operators running 90+ days have specific operational issues that should be diagnosable from the by-carrier, by-service-line, by-job-size view. Targeting under 30 days is unrealistic in this industry; targeting under 45 is achievable on the mitigation side but not the reconstruction side.
Should I use a restoration-specific billing service or build in-house?
Depends on shop size and current capability. Shops under $3 million with no in-house Xactimate-certified estimator typically benefit from a billing service — the cost is roughly offset by the cycle compression. Shops over $5 million should generally have in-house capability because the service fees become a real expense at scale and because in-house ownership of the cycle produces better discipline. Shops in between can go either way; the deciding factor is whether in-house capacity is genuinely competent or whether it is the owner-operator’s spouse doing it on weekends.
How do I get my AR aging by carrier, service line, and job size if my accounting system doesn’t slice it that way?
This is a one-time configuration project. Most accounting systems used by restoration companies (QuickBooks Online, QuickBooks Enterprise, Sage Intacct, NetSuite, restoration-specific platforms like Albi, KnowHow, and others) support custom fields or class tracking that can produce this slicing. The configuration takes a few days of accountant time and pays back permanently. If your current system genuinely cannot support this, the system is the bottleneck.
What about retainage on commercial work?
Commercial reconstruction often involves retainage (commonly 5-10 percent held until project completion) which extends the cycle on the retained portion well beyond the standard cycle. Build retainage into the AR aging view as a separate category so the operating cycle on the non-retained portion is visible cleanly. Retainage release is its own follow-up activity that should be treated as a managed process, not as something that happens automatically.
What if a specific carrier program is producing a long cycle but represents a meaningful portion of revenue?
This is a strategic decision, not just an operational one. The cycle math is real — if a carrier program produces revenue at acceptable margin but stretches AR by an extra 30 days, that’s a working-capital cost that the program revenue should justify. Quantify the cost (roughly the additional AR carried at the cost of capital), compare to the program’s contribution to gross profit, and decide whether the program is net positive on cash-adjusted economics. Many operators discover that programs they thought were valuable are actually drag once the cycle cost is accounted for.
How do I handle homeowners who do not endorse the joint check from the mortgage company?
This is a customer-service issue layered on a cash-cycle issue. Communicate the joint-check process to the homeowner before the loss is even mitigated, get them comfortable with the workflow, and follow up actively when the check is issued. Most customers cooperate; the few who do not usually have a deeper issue (dispute over scope, dispute over quality, financial distress) that needs to be addressed directly. Avoid letting these accounts age silently.
Is a line of credit absolutely necessary, or can a shop run without one?
Smaller shops under $1-2 million can sometimes run without one if reserves are healthy and growth is moderate. Shops over $3 million typically benefit from having one even if it sits unused most months — the optionality is worth the modest commitment fee. The decision is risk tolerance: a line of credit is insurance against a slow collection month, and like all insurance, it is most valuable when not needed.
How do I know if my Xactimate practice is the bottleneck?
Pull your most recent ten mitigation invoices and ten reconstruction invoices. For each, document the date submitted, the date approved, and any back-and-forth requests from the adjuster. If more than 30 percent of submissions trigger requests for revisions, your Xactimate practice has gaps. The specific gaps will be visible in the revision requests — line items used incorrectly, pricing outside standard with insufficient justification, scope items unsupported by documentation. Address those gaps directly, and the cycle compresses.
Can compressing the AR cycle actually replace the need for outside capital on a growing shop?
For most shops in the $1-30 million range, yes. The math works because each dollar of cycle compression frees a proportional dollar of working capital, and that capital recurs every cycle. Compressing cycle from 90 to 60 days on a $10 million shop frees roughly $830,000 in cash; on a $20 million shop, roughly $1.7 million. Those numbers fund meaningful growth without any external capital. Operators with cleaner AR cycles typically do not borrow for working capital because they do not need to.
What is the single most important practice I can install this week?
Daily documentation by the lead tech on every job, completed before the tech leaves site. Photos of pre-mitigation and post-mitigation conditions, moisture readings logged with timestamps, daily report covering work performed and conditions encountered, signed work authorization on file from day one. This single practice will compress your invoice submission time and reduce documentation-driven adjuster delays by more than any other change. Everything else in this article matters; this is where to start.
Updated Oct 31, 2026 — added the free Xactimate-to-cash quick card, cash-cycle fix pack, and AR cash-cycle bot book downloads to this guide.
Direct answer: A restoration company is not just a service company. It is a working-capital-intensive, claims-cycle-dependent, equipment-rich, labor-leveraged business where gross margin varies from 70 percent on water mitigation to 10 percent on reconstruction, where net margin compresses as revenue grows, and where the gap between the average operator and the well-run operator is several multiples of profitability. The discipline that separates the two is not heroic effort; it is financial and operational rigor applied consistently to a small set of decisions about service mix, AR cycle, equipment leverage, crew structure, KPI hygiene, carrier-program exposure, multi-location structure, and exit posture. This pillar introduces those eight decisions and frames the cluster that explores each one in depth.
The restoration industry sits in a strange place. Industry analysts cite a market range from $7.1 billion to $80 billion in U.S. revenue, depending on how the boundary is drawn — water mitigation only, all property restoration, all property and remediation including mold and biohazard, or the full disaster-recovery economy including reconstruction and contents. The Restoration Industry Association and Restoration & Remediation Magazine have referenced the wider range publicly, and the consensus growth rate sits at 4-6 percent CAGR. Within that aggregate market, the operator-level reality is that the industry is fragmented — thousands of independent shops in the $1M to $30M range, several hundred regional operators in the $30M to $200M range, and a small set of national consolidators with revenue over $200M. The fragmentation is the opportunity. It is also the trap.
The opportunity is that no national brand has captured commodity property restoration the way ServiceMaster did in dry cleaning or Home Depot did in retail. Independent operators with discipline can build $5M to $50M businesses with strong margins and durable client relationships. The trap is that fragmentation lets bad businesses survive longer than they should. A restoration company can run for a decade with sloppy AR, undisciplined service mix, and informal operations and still pay the owner well in good years — until a CAT-event swing, a carrier-program change, or a key-employee departure exposes the underlying weakness and the business loses years of compounding to the cleanup. The well-run shop avoids this not by being smarter on the day of the event but by having installed financial and operational discipline before the event ever arrived.
This article is the pillar for the cluster that follows. The cluster covers eight specific decisions where finance and operations rigor moves the needle the most: AR aging and the Xactimate-to-cash cycle, gross margin by service line, equipment economics, crew structure and labor cost, KPI dashboards, preferred-vendor program economics, multi-location growth, and M&A and exit dynamics. This pillar walks through each at altitude so an owner-operator can see how they connect before deciding which to attack first.
The unit economics that actually drive a restoration company
Unit economics that actually drive a restoration company.
The restoration industry’s unit economics are unusual in three specific ways that operators frequently miss until they are scaling and the math stops working.
Service-line gross margin is wildly different by line. Water mitigation typically runs 70-80 percent gross margin because equipment does most of the work — air movers and dehumidifiers run on 24-hour cycles with limited human labor — and the Xactimate price list rewards this with strong unit pricing. Mold remediation runs 40-50 percent gross margin because the labor content is heavier and the protective and disposal cost is real. Fire damage restoration runs 25-30 percent gross margin because the work is labor-intensive, slow, and contents-heavy. Reconstruction runs around 10 percent gross margin because it is a construction business with construction margins layered on top of the restoration relationship.
That spread — 70 percent on the front of the loss to 10 percent on the back — means that two restoration companies with the same revenue can have radically different profitability depending on the mix. A $5 million shop with 60 percent water and mold and 40 percent reconstruction makes meaningfully more money than a $5 million shop with 30 percent water and mold and 70 percent reconstruction, even if both are running competent operations. Mix is the single most important financial decision an operator makes, and it is rarely an explicit decision — it tends to drift based on what comes through the door. Treating mix as a deliberate strategic choice is the first move a finance-aware operator makes.
Net margin compresses as revenue grows. Independent industry references — including operator surveys cited by Restoration & Remediation Magazine and analysis from restoration-industry CFO advisors like Kiwi Cashflow — show that smaller restoration shops under $1M revenue can sustain gross margins near 70 percent, while shops over $50M typically run net margins in the 6 percent range and shops in the $30-50M band typically run net margins around 15 percent. The shape of the curve is consistent across multiple sources: the smaller the shop, the higher the gross margin and the more variable the net margin; the larger the shop, the more compressed the gross margin and the more stable but lower the net margin.
Why? Three structural reasons. First, smaller shops do less reconstruction proportionally — they pass it off — which keeps gross margin high. Second, smaller shops carry less overhead because the owner is doing the management work; larger shops require professional management layers that show up in SG&A. Third, larger shops carry more carrier-program exposure, which compresses pricing through preferred-vendor program rate negotiation. The implication for an operator is that the path to higher absolute dollars is real but does not produce proportional margin gains, and the operator who thinks scale will solve a margin problem is usually wrong.
Working capital intensity is brutal. Restoration is a cash-out, cash-in-much-later business. The work is performed in days or weeks; the cash is collected in months. The operator advances labor cost, equipment depreciation, materials, and subcontractor payments out of pocket and waits for the carrier to settle the claim. AR aging in the 60-120 day range is normal in commercial work and not unusual in residential work either. A shop growing 30 percent year over year is funding that growth with working capital — and a shop that grows faster than its working capital cycle can support runs out of cash even while showing strong P&L performance. This is the most common silent killer of growing restoration companies, and it is the subject of the first article in the cluster that follows.
The eight decisions that separate compounders from plateaued operators
Eight decisions that separate compounders from plateaued operators.
The cluster that follows takes each of these decisions in depth. Here is the at-altitude framing of each so the operator can see the system before drilling into the parts.
AR aging and the Xactimate-to-cash cycle. The well-run shop measures Days Sales Outstanding by carrier, by service line, and by job size. It identifies the carrier programs whose AR cycle is acceptable and the ones that are not. It chooses to take or decline work based on cash-cycle math, not just margin math. It builds a working-capital reserve sized to the actual AR aging profile rather than the optimistic version. It treats AR as a strategic asset rather than a back-office annoyance.
Gross margin by service line. The well-run shop knows its gross margin to within a few points on each service line and uses that knowledge to manage mix deliberately. It chooses which service lines to lead with, which to accept opportunistically, and which to refuse — and it makes those choices based on the gross margin profile and the overhead-absorption requirements of each line, not on which work happens to come through the phone today.
Equipment economics. The well-run shop runs an equipment economic model that distinguishes between owning, leasing, and renting. It tracks equipment utilization, depreciation, and reinvestment cadence. It avoids both under-investment (forcing crews to wait for equipment that should already be on hand) and over-investment (carrying equipment that sits idle and burns capital). It treats the equipment fleet as a financial asset whose ROI is measurable rather than as a vague necessary cost.
Crew structure and labor cost. The well-run shop has a deliberate org structure that includes lead-tech tracks, supervisor tracks, and project-management tracks with explicit progression criteria, compensation bands, and productivity targets. It measures revenue per technician hour by service line. It manages labor as the largest controllable cost and treats hiring, training, and retention as strategic activities rather than reactive ones.
KPI dashboards. The well-run shop runs on a dashboard that includes job-level revenue, gross margin, AR aging, equipment utilization, labor productivity, customer acquisition cost by source, retention by source, and the small set of operational metrics that drive financial outcomes. The dashboard is simple, current, and reviewed weekly. It is the difference between an operator who is reacting to last quarter’s numbers and an operator who is steering against this week’s.
Preferred-vendor program economics. The well-run shop knows the true economics of each carrier preferred-vendor program — the rate concessions, the volume commitments, the documentation overhead, the AR cycle, and the program’s strategic risk. It distinguishes programs that produce profitable revenue from programs that produce activity at margin levels that do not justify the operational overhead. It uses preferred-vendor work as one channel among several rather than as the foundation of the business, because the operator who is dependent on a single carrier’s program is one underwriting decision away from a revenue cliff.
Multi-location growth. The well-run shop knows that the second location is structurally different from the first, the fifth is structurally different from the second, and the model that worked at $5 million breaks at $15 million and again at $50 million. It scales deliberately by building management depth ahead of revenue growth, by standardizing operations and financial reporting before geographic expansion, and by recognizing that multi-location restoration is a different business — a portfolio of operating businesses rather than a single business with multiple offices.
M&A and the consolidator landscape. The well-run shop understands the consolidator landscape — the strategic acquirers including BluSky (Partners Group and Kohlberg), ATI Restoration (TSG Consumer Partners), BMS CAT (AEA Investors), BELFOR, First Onsite, ServiceMaster Restore, Paul Davis, PuroClean, DKI, and the broader set of more than fifty private-equity platforms that have entered restoration since 2018 — and the deal mechanics that drive valuations. It positions early so that when an exit makes sense, the company is sellable at a premium. Or it positions to acquire small competitors itself. Or it makes the deliberate choice to remain independent, with a clear understanding of what that choice means for the owner’s long-term wealth.
These eight decisions are not equally important to every operator at every stage. An operator at $2 million revenue should focus on AR cycle, service mix, and labor cost — KPI dashboards and M&A are premature. An operator at $30 million revenue should focus on multi-location structure, preferred-vendor program economics, and exit positioning — basic AR discipline should already be in place. The cluster takes each decision in turn and explains the moves that matter most at each stage.
What this pillar is not
This pillar is not a financial-modeling primer. There are good resources for that — restoration-industry CFOs like Kiwi Cashflow publish accessible content for operators, and broader trade publications like Restoration & Remediation Magazine and Cleanfax run regular benchmarking surveys. The cluster references these where useful and does not duplicate them.
This pillar is not a substitute for working with a CPA who understands the restoration industry. The tax structure of a restoration company — the choice of S-corp vs. C-corp, the equipment depreciation strategy, the inventory accounting for materials, the treatment of subcontractor versus W-2 labor — is jurisdiction-specific and operator-specific. An operator running a finance and operations discipline without a real CPA relationship is missing the most important piece of the system. Find one early.
This pillar is not financial advice for any individual company. The numbers cited in the cluster are industry references, not specific recommendations. Every operator’s economics differ based on geography, mix, scale, carrier exposure, and dozens of other variables. Use the cluster as a framework to think with, not as a template to copy from.
How to read the cluster
Read the cluster with the van in mind — field reality first.
The cluster of eight articles that follows can be read in sequence — and there is some logic to reading it that way, since AR cycle and service-line economics are the foundation that the later articles build on. But it can also be read selectively. An operator who already has clean AR discipline can skip article one. An operator at $3 million revenue can skip the multi-location and M&A articles for now. An operator who is exit-curious can skip directly to the M&A piece and work backwards from there.
The articles share a structural pattern. Each opens with the operator-level question the article answers. Each names the specific moves the well-run shop makes on the question. Each acknowledges where the answer is genuinely operator-specific and where the answer is industry-generalizable. Each ends with what to read next inside this cluster and what to read elsewhere on Tygart Media.
The cluster is meant to function as the operator’s reference library on the financial and operational side of running a restoration company — the way the Marketing Stack cluster functions as the reference library on the demand side, and the way the Specialty Restoration cluster functions as the reference library on commercial wedge strategy. Together those three clusters cover the major operating axes of the restoration business: how you get work, how you do high-margin commercial work, and how you run the company you have built.
Where the consolidator industry is going
A note on the broader industry context that frames the entire cluster, and especially the M&A article at the end. The restoration industry is in the middle of a consolidation cycle. As referenced by Cleanfax in operator coverage, approximately three brands operate above the $2 billion revenue threshold today, and industry leaders predict that by 2030 the count of $2 billion-plus brands will roughly double. Private equity has been active in the space for several years; industry M&A coverage from sources like The Deal Sheet and Hyde Park Capital identifies more than fifty PE platforms acquiring restoration operators since 2018, with deals at platform-level transacting in the 4x-7x EBITDA range and smaller-company deals transacting in the 3-4x range. The strategic acquirers — BluSky, ATI, BELFOR, BMS CAT, First Onsite, ServiceMaster Restore, Paul Davis, PuroClean, DKI — are buyers across multiple deal sizes. Carrier preferred-vendor programs reward national footprints, which structurally favors the consolidators. Insurance program economics increasingly require the documentation, technology, and reporting capabilities that smaller shops struggle to maintain.
For owner-operators, this trajectory matters in two ways. First, it raises the value of independent shops that have built defensible operations — clean financial reporting, defensible service-mix discipline, durable customer relationships that are not dependent on a single carrier program, professional management depth — because these are the targets the consolidators want to buy. Second, it raises the difficulty of staying independent in a commodity-restoration market position, because the consolidators have scale advantages on carrier-program economics, technology, and back-office cost. The defensible independent posture is to specialize, professionalize, and build differentiated capability — the specialty wedge from the prior cluster, plus the operational discipline this cluster discusses.
The owner-operator who reads this cluster should be doing so with a clear strategic intent. Either build to scale, build to exit, or build to remain durably independent in a defensible niche. All three are legitimate. None of them happen by accident, and all of them require the financial and operational discipline this cluster describes.
What does this cluster cover that the marketing stack and partner industries clusters do not?
The marketing stack covers demand generation — how a restoration company gets work in the door. The partner industries cluster covers referral relationships — how a restoration company gets work from adjacent service providers. The specialty restoration cluster covers the commercial-account wedge. This cluster covers what happens after work comes in: how the company is financed, how its operations are structured, how its profitability is managed, and how the owner positions the business for long-term value creation. All four clusters are needed to run a complete restoration business.
What revenue range is this cluster aimed at?
Primarily $2 million to $30 million in annual revenue — the owner-operator independent segment. The articles acknowledge what changes above $30 million and at $50-million-plus scale, particularly in the multi-location and M&A pieces, but the core advice is calibrated to operators who own the business they are running.
Why are the gross margin numbers cited so different from what I see in my own books?
Because every operator’s mix, geography, labor structure, and equipment posture is different. The numbers cited — water 70-80 percent, mold 40-50 percent, fire 25-30 percent, reconstruction around 10 percent — are industry directional ranges from public benchmarks and CFO commentary, not specific predictions for any individual company. Use them as a sanity check on your own numbers. If your water mitigation gross margin is 50 percent, that is a real signal worth investigating — likely a labor-cost issue, an Xactimate pricing issue, or an overhead-allocation issue. If your reconstruction margin is 25 percent, that is also a real signal worth investigating — likely a scoping or labor-attribution issue. The benchmarks are the start of a conversation, not the end of one.
Should I be running this cluster’s discipline before pursuing the specialty wedge from the prior cluster?
Yes, in most cases. The specialty wedge is a growth strategy for commercial accounts. The financial and operational discipline in this cluster is the foundation that lets a restoration company actually capture and sustain that growth. An operator who pursues commercial specialty work with sloppy AR, undisciplined service mix, and informal operations will win some accounts and then implode under the weight of work they cannot service profitably. The order is: get the operating system clean, then expand into commercial specialty. There are exceptions — operators who already have clean operations and are specifically growth-constrained should pursue the specialty wedge in parallel — but for most operators, the cluster sequencing is operations first, growth second.
Do consolidators pay enough that an exit makes financial sense for an owner-operator?
It depends on the company, the buyer, the structure, and the timing. Industry deal multiples in restoration vary widely — public references from Viking Mergers, Peak Business Valuation, and First Page Sage show small-shop SDE multiples typically in the 2.3x-3.5x range, smaller EBITDA deals in the 3x-4x range, and PE platform-level deals in the 4x-7x range, with the highest multiples reserved for differentiated, well-managed operators with national-scale appeal. The M&A article in this cluster covers what drives the spread and what an owner can do over a two-to-three-year horizon to position for the higher end. For most owner-operators, the answer is that exit is a real wealth-creation event when the company has been built deliberately for it, and a disappointment when the owner has run the business well operationally but never thought about exit value until they were ready to sell.
What if my company is already at $50 million-plus revenue — is this cluster useful?
The pillar and several articles still apply at any scale. The AR cycle, service-line economics, and KPI dashboard articles are scale-agnostic. The labor and crew article scales with adaptation. The equipment article scales with adaptation. The multi-location and M&A articles are written specifically for the upper end. The cluster is calibrated to the owner-operator segment but does not pretend that the lessons stop there.
Why is this published on Tygart Media rather than packaged as a paid product?
Because Tygart Media’s content thesis is that the most valuable operator-level intelligence in the restoration industry is given away to readers who become long-term operating partners with Tygart. The companies that read this cluster, find it useful, and hire Tygart for managed marketing operations are the ones who become five-year clients. The economics work. The cluster is free for the same reason the prior three clusters are free.
What should I read after this pillar?
Start with the AR aging and Xactimate-to-cash cycle article — it is the single highest-leverage operational improvement most restoration companies can make. From there, the gross margin by service line article naturally follows. After those two, sequencing is operator-dependent. An operator at $5 million should pick crew structure or KPI dashboards next. An operator at $25 million should pick multi-location growth or preferred-vendor program economics next. The cluster works in any order after the first two articles.
Is this cluster going to be updated as industry conditions change?
Yes. The restoration industry is in active consolidation, carrier-program economics are shifting, and the technology stack available to operators is changing rapidly. Tygart Media revisits the cluster on roughly an annual basis to update industry references, refresh the consolidator landscape, and incorporate new operator intelligence. Readers who subscribe via the email list at the bottom of any Tygart Media page will be notified when major updates occur.
What is the single most important takeaway from this pillar?
That a restoration company is a real business, not a service shop, and the operators who treat it as a real business — with deliberate financial discipline, deliberate operational structure, deliberate growth strategy, and deliberate exit positioning — compound their wealth at multiples of the operators who treat it as a service shop. The work is not glamorous. The discipline is not optional. The cluster that follows describes the work in detail.
For Everett-area businesses, importers, shippers, and logistics operators, the Port of Everett’s $11.25 million federal grant to rebuild Pier 3 is a supply chain story. Pier 3 — the port’s longest berth at 730 feet — has been operating well below its original structural capacity for years, limiting which cargo-handling equipment can run on it and therefore limiting what kinds of freight can move through it. The rebuild changes that. Here is what businesses need to know about what the project restores and why it matters for Snohomish County’s logistics position.
The Problem the Grant Solves
Pier 3 was built in 1973 with a design live load of 800 pounds per square foot — the rating that allows standard cargo-handling equipment to operate on it. Structural degradation over five decades has forced successive deratings. Today, the south side of the pier is rated at 600 lbs/sqft. The north side is 400 lbs/sqft. Some sections are lower.
In practice, that means the heavier cranes, forklifts, and handling equipment that would otherwise run on a full-capacity pier cannot be permitted. Cargo that requires that equipment has to be handled differently — or routed elsewhere. The rebuild installs new vertical piles and restores damaged structural elements, returning the pier to its full capacity and allowing normal heavy-equipment operations to resume.
What It Means for the Port’s Cargo Mix
The Port of Everett Seaport handles bulk commodities (alumina ore, cement), forest products, and general cargo. A fully restored Pier 3 expands the port’s ability to handle a more diverse mix of freight — particularly cargo requiring heavy handling equipment that the derated pier currently cannot support.
For businesses that import or export through Puget Sound, a stronger Port of Everett means more optionality. The port is already designated by MARAD as a Strategic Commercial Seaport — one of only 18 nationwide — based on its importance to Department of Defense logistics. The rebuild reinforces that designation and the port’s position as a viable alternative to Port of Seattle or Tacoma for certain cargo categories.
The Industrial Market Context
Snohomish County is currently the most affordable industrial and warehouse market in the Puget Sound region. Q1 2026 data from Kidder Mathews shows asking rents running $0.70 to $1.00 per square foot monthly on a triple-net basis — the value end of a market where Seattle-side King County runs up to $1.60/sqft. With 10.39% industrial vacancy across the Seattle metro, Snohomish County is in a tenant-favorable window that is unlikely to last.
A higher-capacity Pier 3 makes the Port of Everett a more competitive import/export hub for businesses already operating in those Snohomish County industrial parks. The supply chain logic is straightforward: affordable warehouse space plus a functioning deepwater port with full cargo-handling capacity is a logistics combination that the county’s industrial corridor — running along Highway 9, SR 9, and the I-5 corridor north of Everett — is well positioned to promote. The full Snohomish County industrial market analysis is at this site’s warehouse market guide for Q1 2026.
Defense Logistics: The DOD Connection
As a MARAD Strategic Commercial Seaport, the Port of Everett supports Department of Defense cargo movements — military equipment, supplies, and materiel that move through commercial ports during exercises, deployments, and mobilizations. The Navy’s presence at Naval Station Everett, combined with the Port’s Strategic Seaport designation, makes Everett a node in the military logistics network that extends from Puget Sound to the Pacific.
The Pier 3 rebuild strengthens that node. For contractors and businesses that support the defense supply chain — from aerospace suppliers in the Paine Field corridor to logistics companies that handle defense cargo — a fully operational Pier 3 is relevant infrastructure.
How to Engage With the Port
The Port of Everett’s seaport operations team handles cargo inquiries directly. The project covers planning, engineering, environmental review, permitting, and construction — a multi-year timeline. Businesses with active or planned cargo operations at Pier 3 should contact the Port directly at portofeverett.com for scheduling and operational impact information as the project progresses.
What types of cargo will Pier 3 handle after the rebuild? A more diverse cargo mix than the derated pier currently allows. Historically: bulk alumina ore, cement, general cargo, forest products. Full 800 lbs/sqft restoration allows heavier cargo-handling equipment to operate.
Does the Pier 3 rebuild affect current shipping operations? Construction phasing and operational impacts have not been announced. Contact the Port of Everett directly at portofeverett.com for scheduling questions.
What is the Port of Everett’s overall capacity? Washington’s third largest container port and a MARAD Strategic Commercial Seaport, supporting 40,000+ local jobs. Handles bulk, breakbulk, and general cargo.
How does the Pier 3 rebuild connect to Snohomish County’s industrial market? Snohomish County is the most affordable Puget Sound industrial market at $0.70–$1.00/sqft NNN. A stronger Pier 3 adds import/export capability that supports businesses in county industrial parks.
How does a business inquire about Port of Everett shipping services? Contact portofeverett.com directly. The Port handles bulk, breakbulk, and general cargo inquiries through its seaport operations team.
When Olympic Mountain Ice Cream outgrew its Skokomish Valley production facility, the company didn’t move out of Mason County. It moved to the Port of Shelton — four times the floor space, a loading dock, reliable power, and a location off Highway 101 that solved the flooding and outage risks that had periodically interrupted production. The move was funded in part by a $1.75 million low-interest loan through the Washington State Community Economic Revitalization Board. That combination — Port infrastructure plus state economic development capital — is available to other Mason County businesses, not just ice cream manufacturers.
What the Port of Shelton Offers Local Businesses
The Port of Shelton is a public port authority serving Mason County’s industrial and commercial development needs. Located off U.S. Highway 101 near Shelton’s industrial corridor, the Port owns and manages industrial warehouse space, commercial properties, and development parcels that it makes available for lease or partnership arrangements with businesses looking to expand, relocate, or establish operations in the county.
Olympic Mountain Ice Cream’s new home is an 11,500-square-foot Port-owned warehouse at 130 W. Corporate Drive, renovated specifically for food production and retail operations under a formal Port Commission resolution approving the CERB partnership. The Port doesn’t simply provide space — it can act as the applicant and co-investor in public funding mechanisms, as it did here by taking on the CERB application on behalf of the ice cream company.
For Mason County businesses in manufacturing, food production, light industrial, or distribution operations that have outgrown their current space, the Port of Shelton is worth a direct conversation. The Port can be reached through the Port Commission office or through the Shelton-Mason County Chamber of Commerce.
How the CERB Loan Works
The Community Economic Revitalization Board (CERB) is a Washington State program administered through the Department of Commerce. It provides low-interest loans and grants to support economic development projects in communities across the state — primarily infrastructure, facility improvements, and expansions that create or retain jobs.
CERB funding is typically applied for by a public entity (in this case the Port of Shelton) on behalf of or in partnership with a private business. The $1.75 million award for the Olympic Mountain Ice Cream project was approved by the Port Commission by formal resolution, with a private investment commitment of at least $1 million from the company and a projected job creation of 17 permanent positions over five years.
CERB loans are not grants — they are structured as low-interest loans to the public applicant, which then passes the terms to the private partner. The interest rates and repayment terms are significantly more favorable than conventional commercial financing, particularly for capital-intensive projects like facility construction or major equipment installation.
For Mason County business owners considering expansion projects in the $500,000–$5 million range, CERB is a mechanism worth understanding. Washington State’s Department of Commerce publishes the application requirements and funding cycles; the Shelton-Mason County Chamber and the Port of Shelton can both provide guidance on whether a given project may qualify.
The Business Succession Pattern Worth Watching
The spring 2026 business news also included a smaller but equally instructive story: the sale of T’s Café & Espresso to Shelton City Council member Eric Onisko, who reopened it as Tollie’s Café on April 1 without closing a single day of service, retaining all three employees, and keeping much of the menu intact. The only thing that changed substantially was the name — and the name reached for local history rather than corporate branding.
For Mason County’s small-business owners thinking about succession or exit, the Tollie’s Café model is useful. The seller (Theresa Landsiedel) ran T’s Café for six years; the buyer invested in community character rather than reinvention; the staff retained continuity and employment. That kind of transfer — a going concern passed intact rather than liquidated — is how small-town business ecosystems stay healthy. It also suggests there is a market in Mason County for well-run small businesses with established customer bases and good locations.
The Bigger Picture: Mason County’s Business Infrastructure
Both of this spring’s business stories point to the same underlying condition: Mason County has functional public-private infrastructure for business development that is often underutilized by the businesses it’s designed to serve. The Port of Shelton, CERB, the Chamber of Commerce, and county economic development resources don’t require you to be a large company to access. The Olympic Mountain Ice Cream expansion shows what’s possible when a local producer uses those tools deliberately — and the Tollie’s Café transition shows that smaller-scale successions are happening too.
The county’s next major business calendar event is the 2026 Expo & Bite of Mason County, scheduled for Friday, July 17 on Railroad Avenue in Shelton — a good venue for connections across the local business community.
Frequently Asked Questions — Mason County Business Expansion Tools
What is the CERB program and how does it help Mason County businesses?
CERB — the Community Economic Revitalization Board — is a Washington State program providing low-interest loans and grants for economic development projects. Mason County businesses typically access CERB through a partnership with a public entity like the Port of Shelton, which acts as the applicant. Olympic Mountain Ice Cream’s $1.75 million CERB loan, approved through the Port, is a recent example.
What kind of space does the Port of Shelton have available?
The Port of Shelton manages industrial and commercial properties in Shelton’s industrial corridor off Highway 101. Olympic Mountain Ice Cream’s new facility is an 11,500-square-foot warehouse at 130 W. Corporate Drive. Contact the Port Commission directly or through the Chamber of Commerce for current availability and lease terms.
How many jobs is Olympic Mountain Ice Cream expected to create?
The Olympic Mountain Ice Cream expansion at the Port of Shelton is projected to add 17 permanent jobs over five years, based on CERB application projections. Private investment in the project is at least $1 million in addition to the $1.75 million CERB loan.
Is the Port of Shelton only for manufacturing businesses?
The Port primarily focuses on industrial, manufacturing, and commercial development — the types of businesses that benefit from loading docks, warehouse space, and Highway 101 access. Retail and service businesses typically operate in downtown Shelton or other commercial corridors rather than the Port’s industrial area, though mixed-use development (like OMIC’s production + retail format) can work at Port-owned sites.
Where can Mason County small businesses get help with expansion planning?
The Shelton-Mason County Chamber of Commerce is a good first contact. The Port of Shelton Commission can discuss facility availability. Washington State’s Department of Commerce administers CERB and other economic development programs with published application guidance. The Mason County Economic Development Council also tracks business development resources.
**What does Boeing’s defense and cargo backlog mean for Everett’s economy through 2029?**
The combined KC-46 program (19 deliveries in 2026, Lot 12 through 2029, Air Force plan for 75 additional tankers beyond) and the 777-8F program (first jet rolled out April 23 2026, deliveries from 2028) provide multi-year production visibility at the Everett factory through and past the 2027 commercial 767 sundown. For Snohomish County, that means stable industrial employment, supplier demand, and commercial real estate floor demand around Paine Field through the end of the decade.
If you’re a Snohomish County business owner, a city economic development officer, or a commercial real estate broker watching what Paine Field tells you about the 2027–2029 economy, the most consequential single sentence to come out of Boeing in April 2026 is one most people missed.
It came on the Q1 2026 earnings call on April 22. CEO Kelly Ortberg, asked about defense, listed KC-46 production increases among the Pentagon-driven defense growth lines Boeing expects to benefit from — alongside F-47, F-15EX, enhanced SATCOM, and weapons system production. The KC-46 final assembly line is at Paine Field. The defense ramp Ortberg described is, at the operational level, an Everett economic story.
The next day, the first production-standard 777-8 Freighter rolled out of the Everett factory.
For business and civic readers, this is the read of what those two events mean for the county.
The Backlog Window Through 2029
Local economic development depends on multi-year demand visibility. Backlogs at Paine Field now provide that visibility through 2029:
KC-46: 19 deliveries targeted in 2026, Lot 12 funding 15 more tankers through 2029, Air Force plan to recapitalize 75 additional KC-135s beyond
777-8F: First aircraft rolled out April 23 2026, first deliveries 2028, 34-firm-order book with Qatar Airways plus Cargolux, Lufthansa Cargo, and ANA
737 North Line: First 737 MAX assembly outside Renton in Boeing’s history, ramping inside the Everett footprint
777-9 passenger: Working through certification
That is a fundamentally different mix from 2020, when the 747 line was active and the 787 had moved to South Carolina. The current mix is anchored by defense and cargo — both less cyclical than passenger airline orders.
Why Defense Production Is Different Floor for the Local Economy
For commercial real estate brokers and industrial landlords near Paine Field, the most important property of defense backlogs is that they don’t cycle on consumer demand.
Commercial airframes slow when airlines stop ordering. KC-46 production moves at the speed of Pentagon appropriations and Air Force fleet-age curves. The Air Force flies about 380 KC-135 tankers, the youngest of which is roughly 60 years old. The KC-46 is the chosen replacement. There is one production line in the world that builds it, and it is in Everett.
Even the cost overruns — over $7 billion cumulative since program inception, including a $565 million charge in Q4 2025 — do not slow the line. The Air Force needs the airframes. The county gets the workforce.
For business owners who lease, employ, or sell to households tied to that workforce, the defense ballast is the anchor.
Supplier Implications
The 5,200-worker aerospace shortage projected by the Aerospace Futures Alliance for Washington state is not happening into a flat backlog. It is happening into a backlog that is, between defense and cargo, growing.
For Snohomish County aerospace suppliers — and there are over 600 of them per the Economic Alliance Snohomish County — the operational signal from this week is:
KC-46 supply chain sees increased demand through Lot 12 (2029) and likely beyond if the 75-tanker recap plan moves
777-8F supply chain is actively ramping; the rollout-jet’s first flight, ground testing, and certification activities will pull supplier work forward through 2027
Hiring competition tightens — every supplier is competing for the same skilled trades the Boeing line is hiring; package and benefits become differentiators
For suppliers diversifying customer mix, the defense exposure is now demonstrably the more stable revenue line.
Commercial Real Estate Read
If you broker industrial, flex, or office space within 15 miles of Paine Field:
Industrial demand floor — Boeing supplier base needs floor space; a multi-year backlog floors that demand
Office demand near Paine Field — Snohomish County office vacancy ended Q1 2026 at 10.7% with $31.20 PSF asking rents and a third straight quarter of positive net absorption (per the most recent Q1 reporting)
Workforce housing pressure — 30,000 direct Boeing jobs at Paine Field plus supplier base; multi-year backlog means multi-year housing demand at every price point
Waterfront Place’s 447,500 SF office build-out has a clearer demand signal in this environment than it did 18 months ago when commercial cargo’s 2027 cliff looked unanswered.
What Civic Readers Should Track
For City of Everett economic development staff and Snohomish County Council members, the 2027 transition has been the policy uncertainty. April 2026 narrowed that uncertainty:
The 767 cliff is real, but the post-cliff plan is now operationally evidenced
The KC-46 contractual floor (Lot 12 through 2029) is multi-year stable
The 777-8F program has metal in the air with a customer book
That changes the framing of any tax-base, workforce-development, or housing decision tied to Paine Field employment. Aerospace exposure is, on net, a stable bet through the end of the decade.
Frequently Asked Questions
Q: How many direct aerospace jobs does the Everett Boeing factory support?
A: Roughly 30,000 direct jobs at Paine Field plus the supplier base across Snohomish County (over 600 suppliers per the Economic Alliance Snohomish County).
Q: What is the dollar value of Boeing’s KC-46 Lot 12 contract?
A: $2.47 billion, funding 15 additional tankers along with software licensing, subscriptions, and through-life support, with deliveries running through 2029.
Q: Will the 2027 commercial 767 sundown reduce Snohomish County aerospace employment?
A: Boeing’s announced plan absorbs the 767 commercial workforce into expanded KC-46 production and the ramping 777-8F program, both at Everett. The April 23 2026 777-8F rollout is the first physical evidence of that absorption underway. Net headcount depends on KC-46 ramp, 777-8F ramp speed, and supplier hiring.
Q: How does the Snohomish County office market relate to the Boeing footprint?
A: Q1 2026 office vacancy was 10.7% with $31.20 PSF asking rents and three consecutive quarters of positive net absorption — a tightening market consistent with stable Paine Field employment. Waterfront Place’s 447,500 SF office build-out absorbs into that market.
Q: Are KC-46 cost overruns an economic risk for Everett?
A: KC-46 cost overruns ($7 billion+ cumulative, $565 million charge in Q4 2025) affect Boeing’s corporate margins. They have not historically resulted in production slowdowns at Everett — the Air Force requires the airframes — and so the workforce and supplier base have been insulated from the margin pressure.
Q: What does the 777-8F rollout signal to commercial real estate near Paine Field?
A: A multi-year cargo airframe ramp anchors industrial, flex, and supplier-supporting office demand. Combined with KC-46 stability through 2029, the area has multi-year demand visibility through the end of the decade.
Q: What is the Air Force’s plan for the KC-135 fleet?
A: The Air Force still flies about 380 KC-135 tankers, an airframe that first flew in 1956. The plan is to extend KC-46 Pegasus production beyond the original 179-aircraft program of record and buy roughly another 75 tankers to recapitalize the KC-135 fleet — a multi-decade procurement runway, all running through Everett.
The Signal — Tygart Media's weekly brief. What we actually ran, what it measured, and what it means for a restoration shop.